The SPX index has now posted four consecutive sessions of gains, with a short-term appreciation of over 1.4%. Buying pressure intensified after the recent release of the annual U.S. CPI, which came in line with expectations. This outcome did not significantly alter the outlook for Federal Reserve policy decisions, helping to sustain the bullish momentum in the index. As long as this dynamic persists, demand is likely to remain relevant in the coming sessions.

Inflation Data Day
The annual CPI for the United States was reported at 2.9%, exactly matching forecasts. While a slight uptick in August inflation had been expected, it was not strong enough to meaningfully shift monetary policy decisions. Since April, inflation data has shown a gradual increase, rising from 2.3% to 2.9%. Although still close to the Fed’s 2.0% target, this uptick is not currently its main focus, as greater weight appears to be placed on the deterioration in employment data. Thus, with inflation data meeting expectations, the Fed’s outlook remained unchanged.
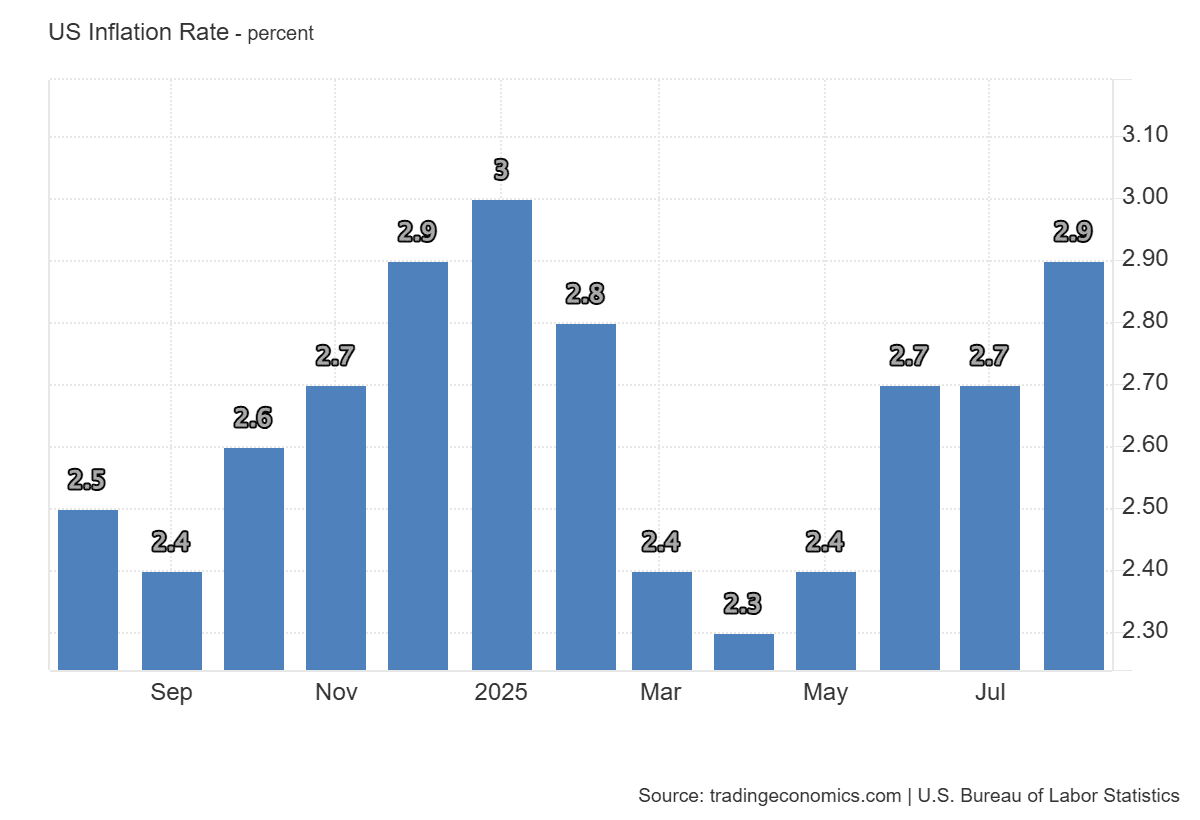
Source: Trading Economics
Indeed, the Fed’s policy stance has not shifted significantly. The CME Group continues to project the likelihood of three rate cuts of 0.25% each by the end of 2025, with probabilities of 88.9% for September 17, 82.6% for October 29, and 77.5% for December 10. This reinforces the expectation of a lower interest rate environment in the short term.
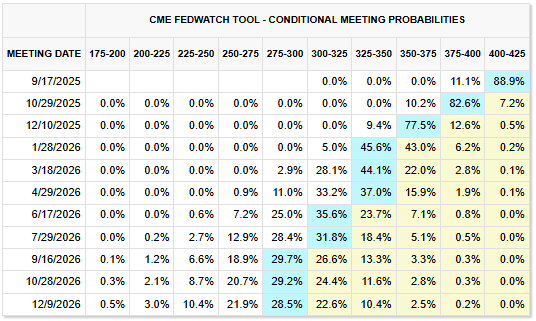
Source: CMEGROUP
The impact is also visible in 10-year U.S. Treasury bonds, where yields maintain a downward slope and now hover around 4.00%, a level not seen since April. This decline highlights the weaker appeal of fixed-income assets, which in turn benefits equities.
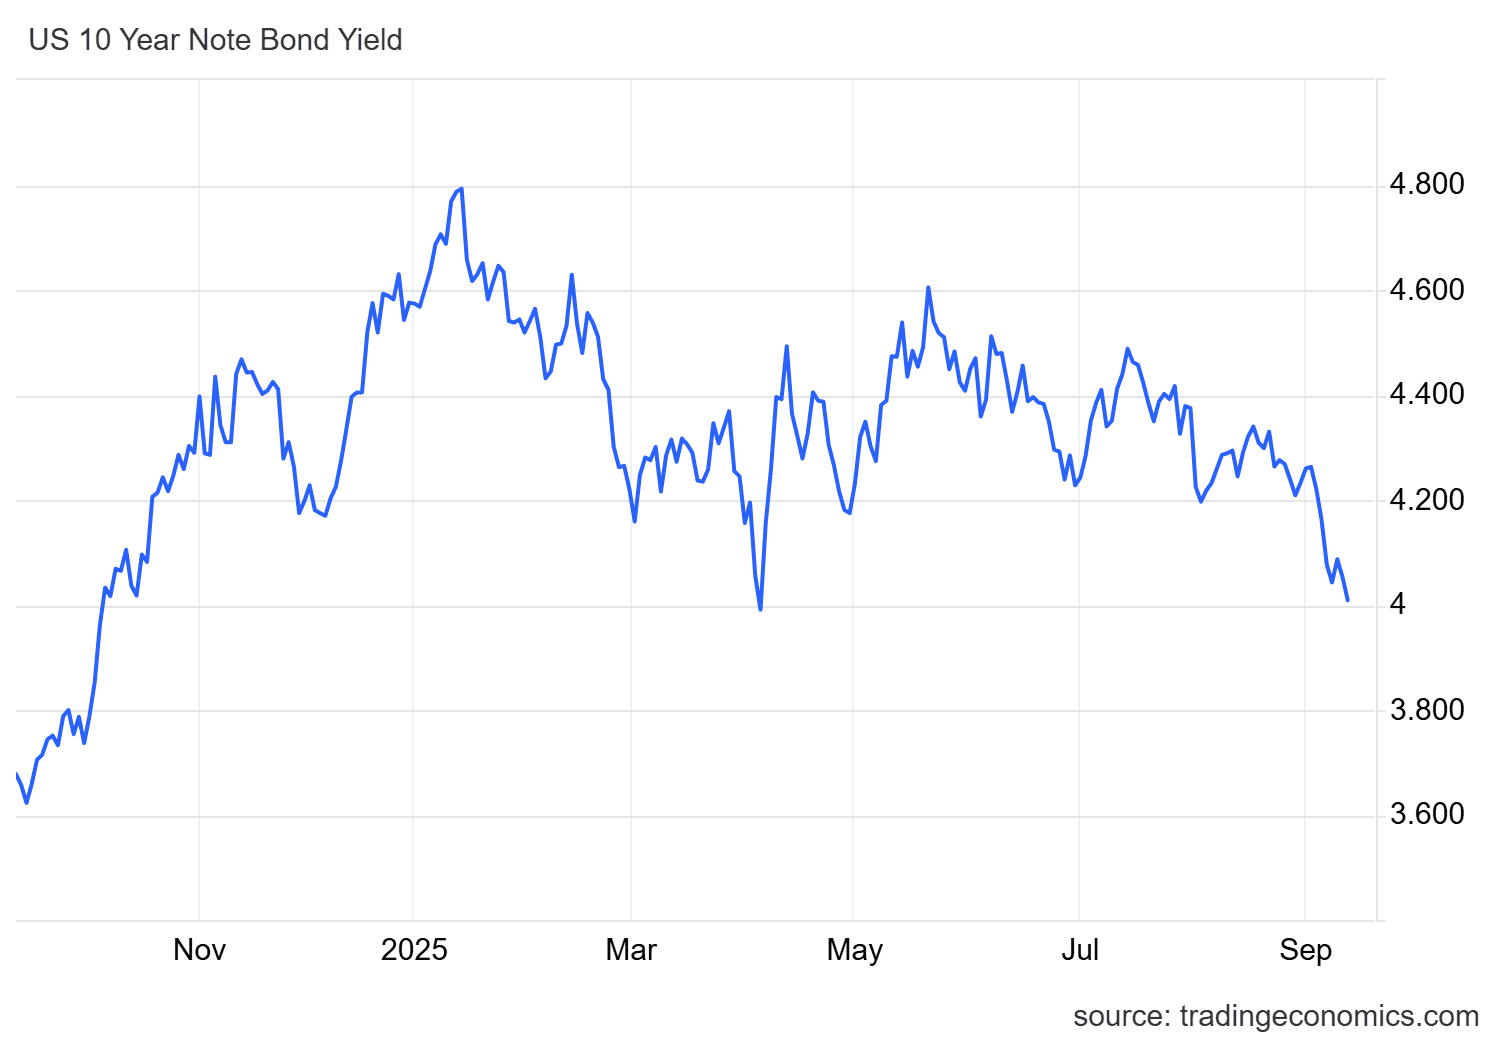
Source: Trading Economics
In this environment, the combination of lower interest rates and falling bond yields supports stock market demand. Lower rates reduce financing costs and stimulate economic activity, boosting corporate performance. At the same time, weaker bond yields —often seen as the equity market’s main rival— make fixed-income assets less attractive, opening more space for equities like the SPX. As long as this backdrop holds, the outlook remains favorable for sustained buying pressure in the index, potentially extending the rally in the sessions ahead.
S&P 500 Technical Outlook

Source: StoneX, Tradingview
- Uptrend remains intact: Since early April, the SPX has maintained a clear bullish trend, trading above 6,000 points. No significant corrections have emerged to threaten this formation, and as long as the index continues to set higher highs, the bullish structure will remain in place.
- RSI: The RSI is approaching the 70 level, entering overbought territory. While this underscores strong buying momentum, a bearish divergence has emerged, with price action setting higher highs while the RSI fails to follow at the same pace. This suggests a possible imbalance in bullish strength, raising the risk of a pause or short-term correction.
- ADX: The ADX line is beginning to rise, approaching the neutral 20 level. If the upward slope continues, it could signal increasing directional strength and support more consistent moves in the sessions ahead.
Key Levels:
- 6,700 points – Major Resistance: The most important psychological reference level in the absence of historical highs. A clear breakout above this zone would reinforce the bullish trend and could attract additional buying, supporting a move toward new highs.
- 6,460 points – Nearby Support: A zone of neutrality seen in recent weeks, which may act as the first barrier against short-term corrections.
- 6,200 points – Key Support: Corresponds to the lows of the last three months. A drop to this level would put the current uptrend at risk and open the door to a more relevant bearish bias.
Written by Julian Pineda, CFA – Market Analyst
Follow him: @julianpineda25