As 2026 begins, the currencies of the United States, Mexico, and Canada continue to be essential pillars of financial stability and sustained trade flows within the North American economic bloc. Heading into the first quarter of 2026, the USD/CAD and USD/MXN pairs face a landscape shaped by changes in interest rates, potential adjustments in trade relations, and ongoing uncertainty surrounding economic growth. Within this context, it is important to highlight that both the Canadian dollar and the Mexican peso remained notably strong through most of 2025—an outlook that could persist if the structural weakness of the U.S. dollar continues into early 2026.

What Can Be Expected from Central Banks Now?
As of this writing, North American central banks are beginning to show clear divergence in their monetary policy paths: some maintain expectations of additional rate cuts, while others have shifted to a more neutral stance. The Bank of Mexico stands out, having lowered its benchmark rate from 10.00% to 7.25% since January 2025—making it the only central bank in the region implementing a sustained easing cycle and the most accommodative monetary authority in North America over the past year.
The Bank of Canada, meanwhile, has followed a different path, alternating between rate cuts and periods of neutrality. Since January 2025, its policy rate has decreased from 3.00% to the current 2.25% (its latest decision of 2025), returning to a state of consistent neutrality, in line with the direction adopted through most of the year. This reflects a more modest rate-cut cycle, contrasting with the more flexible monetary paths observed in other regional economies.
The Federal Reserve, surprised markets with its September decision. Throughout most of 2025, it maintained a neutral rate posture at 4.5%, becoming the only central bank in the region that had not adjusted policy since the December 2024 cut. However, market expectations shifted toward a steady cutting cycle, and the policy rate ultimately fell to 3.75%.
North American Interest Rates Table – 2025
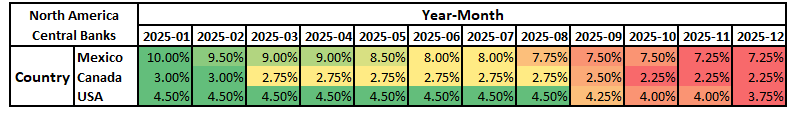
Colors: Green to red; green indicates higher rates and red indicates lower rates.
Source: Data - Tradingeconomics
North American Interest Rates Chart – 2025

Source: Tradingeconomics
With these shifts in mind, the key question is what monetary path North American central banks will take in 2026, as this will likely be decisive for the long-term behavior of their currencies:
- On December 10, the Bank of Canada held its rate at 2.25%, highlighting Canada’s economic resilience in 2025 after a 2.6% Q3 GDP reading. Stronger activity may increase inflationary pressures, leading the bank to maintain a neutral stance into year-end.
- On November 6, the Bank of Mexico lowered its rate to 7.25%, noting that—even after the cut—it remains high relative to other central banks. The decision was influenced by global uncertainty stemming from trade tensions. However, the bank warned that an uptick in inflation may require a policy reassessment in 2026.
- On December 10, the Federal Reserve reduced its rate by 25 basis points to 3.75%, marking its third cut of 2025. The move was driven by labor-market weakness and subdued inflation, keeping the door open for further easing if employment conditions deteriorate.
Thus, inflation data behavior could be critical in shaping upcoming policy decisions. In Canada, inflation rose to 2.2% in October, up from 1.7% in July, slightly above the 2% target. In Mexico, inflation reached 3.8% in November, above both the 3.51% recorded in October and the 3% target.
In the United States, inflation data has been distorted by the recent government shutdown. The latest figure shows a 3% reading in September, higher than the 2.3% in April 2025 and still far from the Fed’s 2% target.
North America Inflation Chart – 2025

Source: Tradingeconomics
Inflation’s upward trajectory has moved central banks further away from their targets. For the Bank of Mexico and the Bank of Canada, this could limit additional cuts, especially as both institutions emphasize the need to keep inflation contained. In fact, inflation was a key factor behind Canada’s decision to maintain a neutral rate stance into late 2025. If CPI continues rising, expectations for lower rates may be restricted during Q1 2026 in both countries.
In the United States, the situation differs: the Federal Reserve has prioritized the labor market, supporting a bias toward lower rates, especially given data disruptions caused by the government shutdown. Unless inflation increases meaningfully, the Fed may continue alternating between low and neutral rates through 2026, consistent with its messaging following the December meeting.
Taken together, the shifts in central bank policy stances could redefine the strength of North American currencies. Mexico continues to hold the highest interest rate in the region, which keeps the Mexican peso attractive in a global low-rate environment. In Canada, inflation concerns support a more neutral policy stance, providing ongoing support for the Canadian dollar. In contrast, the Federal Reserve’s more dovish approach leaves room for additional rate cuts in 2026, weakening demand for U.S. Treasuries and reducing overall appetite for the U.S. dollar. This suggests that, unlike Mexico and Canada—where monetary conditions still offer support—the U.S. dollar may continue to face downside pressure, as seen through much of 2025, which could ultimately lead to persistent selling pressure on both USD/MXN and USD/CAD over the longer term.
What to Expect from the U.S. Dollar?
The U.S. dollar remained broadly weak throughout 2025—first due to economic uncertainty and trade conflict, and later because of rate-cut announcements beginning in August, which marked a clear shift in Fed policy. The DXY index captured this trend, falling below 100 and even touching 96, a level not seen since 2022.

Source: TVC, Tradingview
Although the DXY experienced a partial recovery, it still exhibits a bearish outlook heading into late 2025, consistent with the Fed’s push toward lower rates. If this weakness and indecision persist, both the Mexican peso and Canadian dollar could continue strengthening, reinforcing the downside momentum seen in USD/MXN and USD/CAD across the year. However, the magnitude of the dollar’s decline during the year also suggests limited room for extended weakness, which may prompt short-term bullish corrections in both pairs.
Trade Negotiations Ahead
Throughout 2025, North American trade tensions escalated—driven largely by the administration’s trade war—deteriorating economic relations just ahead of the crucial 2026 USMCA (T-MEC) review. Mexico is reassessing its stance through public consultations and considering trade diversification, while Canada is seeking to strengthen domestic demand and explore new partnerships, including in Asia.
Despite these tensions, the USMCA remains a foundational agreement for both economies, ensuring trade facilitation and regulatory certainty. The 2026 review will be critical, determining whether the agreement is renewed for another 16 years. Government communications may begin signaling the probable direction of the decision.
If tensions lead to a non-renewal or to significant modifications of the agreement, resulting uncertainty could weaken investment confidence, reducing demand for both the Mexican peso and the Canadian dollar—similar to reactions seen during tariff escalations in 2025. Thus, early 2026 currency performance will depend, in part, on positive signals surrounding USMCA continuity. Otherwise, a stronger bearish bias could emerge for both currencies.
Written by Julian Pineda, CFA, CMT – Market Analyst
Follow him at: @julianpineda25