



25 11 EU PRE OPEN
European stocks report | Melrose Industries | Thyssenkrupp | Dassault Systemes...
Share this:

INDICES
Yesterday, European stocks also gained. The Stoxx Europe 600 rose 0.91%, Germany's DAX advanced 1.26%, France's CAC 40 increased 1.21%, and the U.K.'s FTSE 100 was up 1.55%.
EUROPE ADVANCE/DECLINE
56% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 79% Monday (above the 20D moving average).
84% of the shares trade above their 200D MA vs 84% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.12pt to 21.37, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Insurance, Autos, Banks, Travel & Leisure, Energy, Basic Resource
3mths relative low: Chemicals, Food & Beverage, Healthcare
Europe Best 3 sectors
energy, banks, basic resources
Europe worst 3 sectors
personal & household goods, health care, real estate
INTEREST RATE
The 10yr Bund yield was unchanged to -0.58% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -18bps (below its 20D MA).
ECONOMIC DATA
GE 08:40: Bundesbank Mauderer speech
EC 10:30: ECB Financial Stability Review
FR 12:00: Oct Jobseekers Total, exp.: 3606.3K
FR 12:00: Oct Unemployment Benefit Claims, exp.: -15.2K
GE 12:15: Bundesbank Wuermeling speech
UK 13:00: 2020 Spending Review
UK 13:00: OBR Economic and Fiscal Forecasts
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1904 and GBP/USD held gains at 1.3358. USD/JPY edged up to 104.51.
Spot gold was little changed at $1,806 an ounce.
#UK - IRELAND#
Melrose Industries, an investment group, posted a trading update for the four months to October 31: "Melrose is currently trading at the top end of the Board's expectations for 2020. (...) The performance of the Group in the Period reflected the faster than expected recovery in automotive markets, first seen over the summer, the continued strong performance in Nortek Air Management, and the more challenging, although currently stable, market conditions in Aerospace."
#GERMANY#
Thyssenkrupp, an industrial engineering group, was upgraded to "buy" from "hold" at Deutsche Bank.
#FRANCE#
Dassault Systemes, a software company, announced the acquisition of the remainder of cloud-native distributed SQL database company NuoDB equity, which it had a 16% ownership interest. Financial terms were not disclosed.
Air Liquide, an industrial gases supplier, was downgraded to "hold" from "buy" at HSBC.
#SPAIN#
CaixaBank and Bankia, the two Spanish banks, were downgraded to "hold" from "buy" at HSBC.
#BENELUX#
Unibail-Rodamco-Westfield, a commercial real estate company, was upgraded to "neutral" from "sell" at Goldman Sachs.
#SWEDEN#
Volvo, a vehicle manufacturer, was upgraded to "buy" from "hold" at HSBC.
Sandvik, a Swedish engineering group, was downgraded to "hold" from "buy" at HSBC.
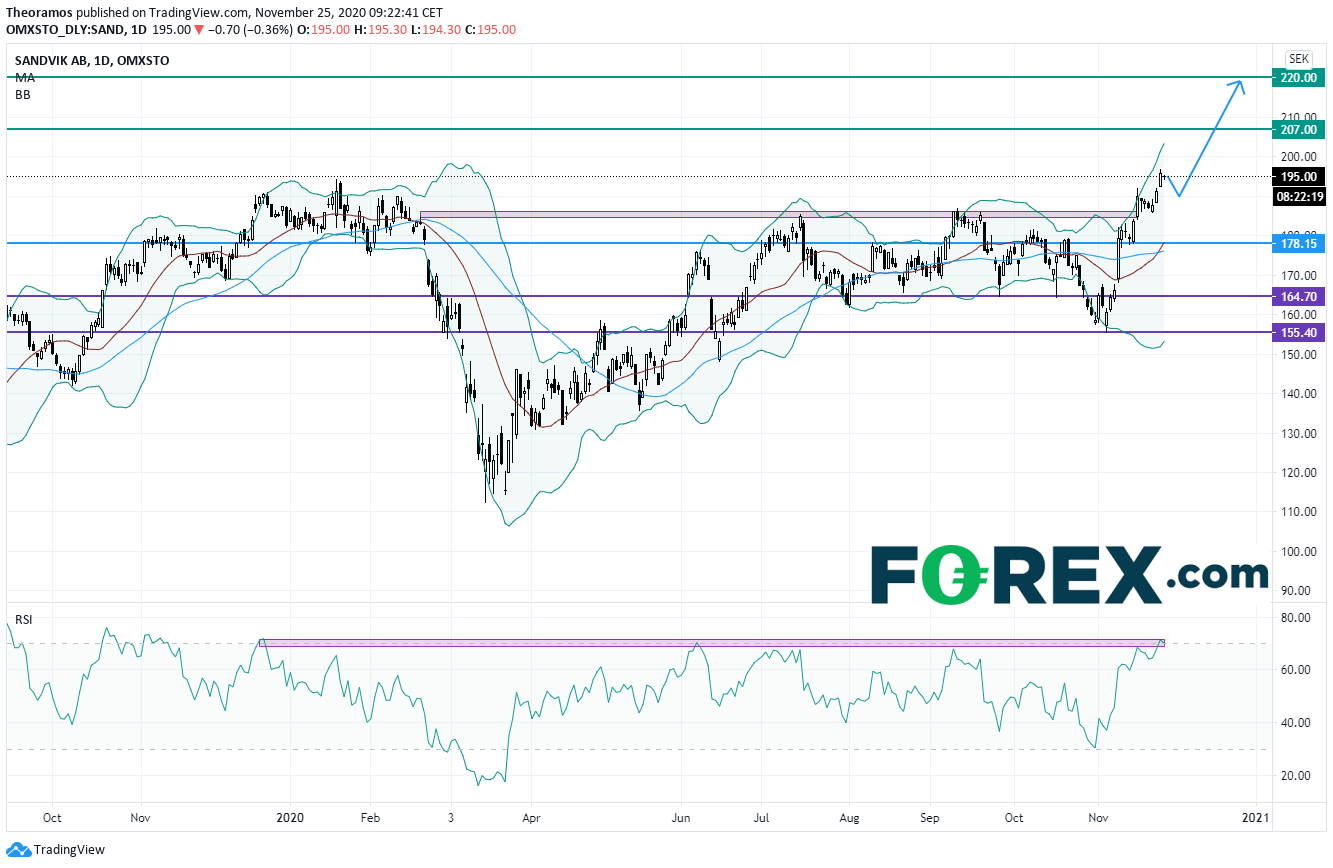
From a technical point of view, the share has broken above the key horizontal resistance around 185SEK, given us the signal of a new up leg and allowing the share price to reach a new all-time high. the RSI is now overbought and is calling for a slight pullback towards 190SEK. Above 178.15SEK, after the correction move, targets are set at 207SEK and 220SEK in extension.

EX-DIVIDEND
Assa Abloy: SEK1.85
Yesterday, European stocks also gained. The Stoxx Europe 600 rose 0.91%, Germany's DAX advanced 1.26%, France's CAC 40 increased 1.21%, and the U.K.'s FTSE 100 was up 1.55%.
EUROPE ADVANCE/DECLINE
56% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 79% Monday (above the 20D moving average).
84% of the shares trade above their 200D MA vs 84% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.12pt to 21.37, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Insurance, Autos, Banks, Travel & Leisure, Energy, Basic Resource
3mths relative low: Chemicals, Food & Beverage, Healthcare
Europe Best 3 sectors
energy, banks, basic resources
Europe worst 3 sectors
personal & household goods, health care, real estate
INTEREST RATE
The 10yr Bund yield was unchanged to -0.58% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -18bps (below its 20D MA).
ECONOMIC DATA
GE 08:40: Bundesbank Mauderer speech
EC 10:30: ECB Financial Stability Review
FR 12:00: Oct Jobseekers Total, exp.: 3606.3K
FR 12:00: Oct Unemployment Benefit Claims, exp.: -15.2K
GE 12:15: Bundesbank Wuermeling speech
UK 13:00: 2020 Spending Review
UK 13:00: OBR Economic and Fiscal Forecasts
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1904 and GBP/USD held gains at 1.3358. USD/JPY edged up to 104.51.
Spot gold was little changed at $1,806 an ounce.
#UK - IRELAND#
Melrose Industries, an investment group, posted a trading update for the four months to October 31: "Melrose is currently trading at the top end of the Board's expectations for 2020. (...) The performance of the Group in the Period reflected the faster than expected recovery in automotive markets, first seen over the summer, the continued strong performance in Nortek Air Management, and the more challenging, although currently stable, market conditions in Aerospace."
#GERMANY#
Thyssenkrupp, an industrial engineering group, was upgraded to "buy" from "hold" at Deutsche Bank.
#FRANCE#
Dassault Systemes, a software company, announced the acquisition of the remainder of cloud-native distributed SQL database company NuoDB equity, which it had a 16% ownership interest. Financial terms were not disclosed.
Air Liquide, an industrial gases supplier, was downgraded to "hold" from "buy" at HSBC.
#SPAIN#
CaixaBank and Bankia, the two Spanish banks, were downgraded to "hold" from "buy" at HSBC.
#BENELUX#
Unibail-Rodamco-Westfield, a commercial real estate company, was upgraded to "neutral" from "sell" at Goldman Sachs.
#SWEDEN#
Volvo, a vehicle manufacturer, was upgraded to "buy" from "hold" at HSBC.
Sandvik, a Swedish engineering group, was downgraded to "hold" from "buy" at HSBC.
From a technical point of view, the share has broken above the key horizontal resistance around 185SEK, given us the signal of a new up leg and allowing the share price to reach a new all-time high. the RSI is now overbought and is calling for a slight pullback towards 190SEK. Above 178.15SEK, after the correction move, targets are set at 207SEK and 220SEK in extension.
Source: TradingView, GAIN Capital
EX-DIVIDEND
Assa Abloy: SEK1.85
INDICES
Yesterday, European stocks also gained. The Stoxx Europe 600 rose 0.91%, Germany's DAX advanced 1.26%, France's CAC 40 increased 1.21%, and the U.K.'s FTSE 100 was up 1.55%.
EUROPE ADVANCE/DECLINE
56% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 79% Monday (above the 20D moving average).
84% of the shares trade above their 200D MA vs 84% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.12pt to 21.37, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Insurance, Autos, Banks, Travel & Leisure, Energy, Basic Resource
3mths relative low: Chemicals, Food & Beverage, Healthcare
Europe Best 3 sectors
energy, banks, basic resources
Europe worst 3 sectors
personal & household goods, health care, real estate
INTEREST RATE
The 10yr Bund yield was unchanged to -0.58% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -18bps (below its 20D MA).
ECONOMIC DATA
GE 08:40: Bundesbank Mauderer speech
EC 10:30: ECB Financial Stability Review
FR 12:00: Oct Jobseekers Total, exp.: 3606.3K
FR 12:00: Oct Unemployment Benefit Claims, exp.: -15.2K
GE 12:15: Bundesbank Wuermeling speech
UK 13:00: 2020 Spending Review
UK 13:00: OBR Economic and Fiscal Forecasts
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1904 and GBP/USD held gains at 1.3358. USD/JPY edged up to 104.51.
Spot gold was little changed at $1,806 an ounce.
#UK - IRELAND#
Melrose Industries, an investment group, posted a trading update for the four months to October 31: "Melrose is currently trading at the top end of the Board's expectations for 2020. (...) The performance of the Group in the Period reflected the faster than expected recovery in automotive markets, first seen over the summer, the continued strong performance in Nortek Air Management, and the more challenging, although currently stable, market conditions in Aerospace."
#GERMANY#
Thyssenkrupp, an industrial engineering group, was upgraded to "buy" from "hold" at Deutsche Bank.
#FRANCE#
Dassault Systemes, a software company, announced the acquisition of the remainder of cloud-native distributed SQL database company NuoDB equity, which it had a 16% ownership interest. Financial terms were not disclosed.
Air Liquide, an industrial gases supplier, was downgraded to "hold" from "buy" at HSBC.
#SPAIN#
CaixaBank and Bankia, the two Spanish banks, were downgraded to "hold" from "buy" at HSBC.
#BENELUX#
Unibail-Rodamco-Westfield, a commercial real estate company, was upgraded to "neutral" from "sell" at Goldman Sachs.
#SWEDEN#
Volvo, a vehicle manufacturer, was upgraded to "buy" from "hold" at HSBC.
Sandvik, a Swedish engineering group, was downgraded to "hold" from "buy" at HSBC.
From a technical point of view, the share has broken above the key horizontal resistance around 185SEK, given us the signal of a new up leg and allowing the share price to reach a new all-time high. the RSI is now overbought and is calling for a slight pullback towards 190SEK. Above 178.15SEK, after the correction move, targets are set at 207SEK and 220SEK in extension.
EX-DIVIDEND
Assa Abloy: SEK1.85
Yesterday, European stocks also gained. The Stoxx Europe 600 rose 0.91%, Germany's DAX advanced 1.26%, France's CAC 40 increased 1.21%, and the U.K.'s FTSE 100 was up 1.55%.
EUROPE ADVANCE/DECLINE
56% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 79% Monday (above the 20D moving average).
84% of the shares trade above their 200D MA vs 84% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.12pt to 21.37, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Insurance, Autos, Banks, Travel & Leisure, Energy, Basic Resource
3mths relative low: Chemicals, Food & Beverage, Healthcare
Europe Best 3 sectors
energy, banks, basic resources
Europe worst 3 sectors
personal & household goods, health care, real estate
INTEREST RATE
The 10yr Bund yield was unchanged to -0.58% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -18bps (below its 20D MA).
ECONOMIC DATA
GE 08:40: Bundesbank Mauderer speech
EC 10:30: ECB Financial Stability Review
FR 12:00: Oct Jobseekers Total, exp.: 3606.3K
FR 12:00: Oct Unemployment Benefit Claims, exp.: -15.2K
GE 12:15: Bundesbank Wuermeling speech
UK 13:00: 2020 Spending Review
UK 13:00: OBR Economic and Fiscal Forecasts
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1904 and GBP/USD held gains at 1.3358. USD/JPY edged up to 104.51.
Spot gold was little changed at $1,806 an ounce.
#UK - IRELAND#
Melrose Industries, an investment group, posted a trading update for the four months to October 31: "Melrose is currently trading at the top end of the Board's expectations for 2020. (...) The performance of the Group in the Period reflected the faster than expected recovery in automotive markets, first seen over the summer, the continued strong performance in Nortek Air Management, and the more challenging, although currently stable, market conditions in Aerospace."
#GERMANY#
Thyssenkrupp, an industrial engineering group, was upgraded to "buy" from "hold" at Deutsche Bank.
#FRANCE#
Dassault Systemes, a software company, announced the acquisition of the remainder of cloud-native distributed SQL database company NuoDB equity, which it had a 16% ownership interest. Financial terms were not disclosed.
Air Liquide, an industrial gases supplier, was downgraded to "hold" from "buy" at HSBC.
#SPAIN#
CaixaBank and Bankia, the two Spanish banks, were downgraded to "hold" from "buy" at HSBC.
#BENELUX#
Unibail-Rodamco-Westfield, a commercial real estate company, was upgraded to "neutral" from "sell" at Goldman Sachs.
#SWEDEN#
Volvo, a vehicle manufacturer, was upgraded to "buy" from "hold" at HSBC.
Sandvik, a Swedish engineering group, was downgraded to "hold" from "buy" at HSBC.
From a technical point of view, the share has broken above the key horizontal resistance around 185SEK, given us the signal of a new up leg and allowing the share price to reach a new all-time high. the RSI is now overbought and is calling for a slight pullback towards 190SEK. Above 178.15SEK, after the correction move, targets are set at 207SEK and 220SEK in extension.
Source: TradingView, GAIN Capital
EX-DIVIDEND
Assa Abloy: SEK1.85
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.


Gold Price Forecast: XAU/USD Plunges 12.4% Toward Critical Support 10 1 2026
Softer inflation has revived expectations for a Fed pause, but Friday’s payrolls could put gold’s recovery prospects to the test.


Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.