



Asia Morning Oct 2
Investors are eyeing closely the September U.S. Jobs Report due later today...
Share this:

On Thursday, U.S. stocks advanced further. The Dow Jones Industrial Average edged up 35 points (+0.13%) to 27816, the S&P 500 gained 17 points (+0.53%) to 3380, and the Nasdaq 100 jumped 165 points (+1.45%) to 11583.
S&P 500 Index: Daily Chart
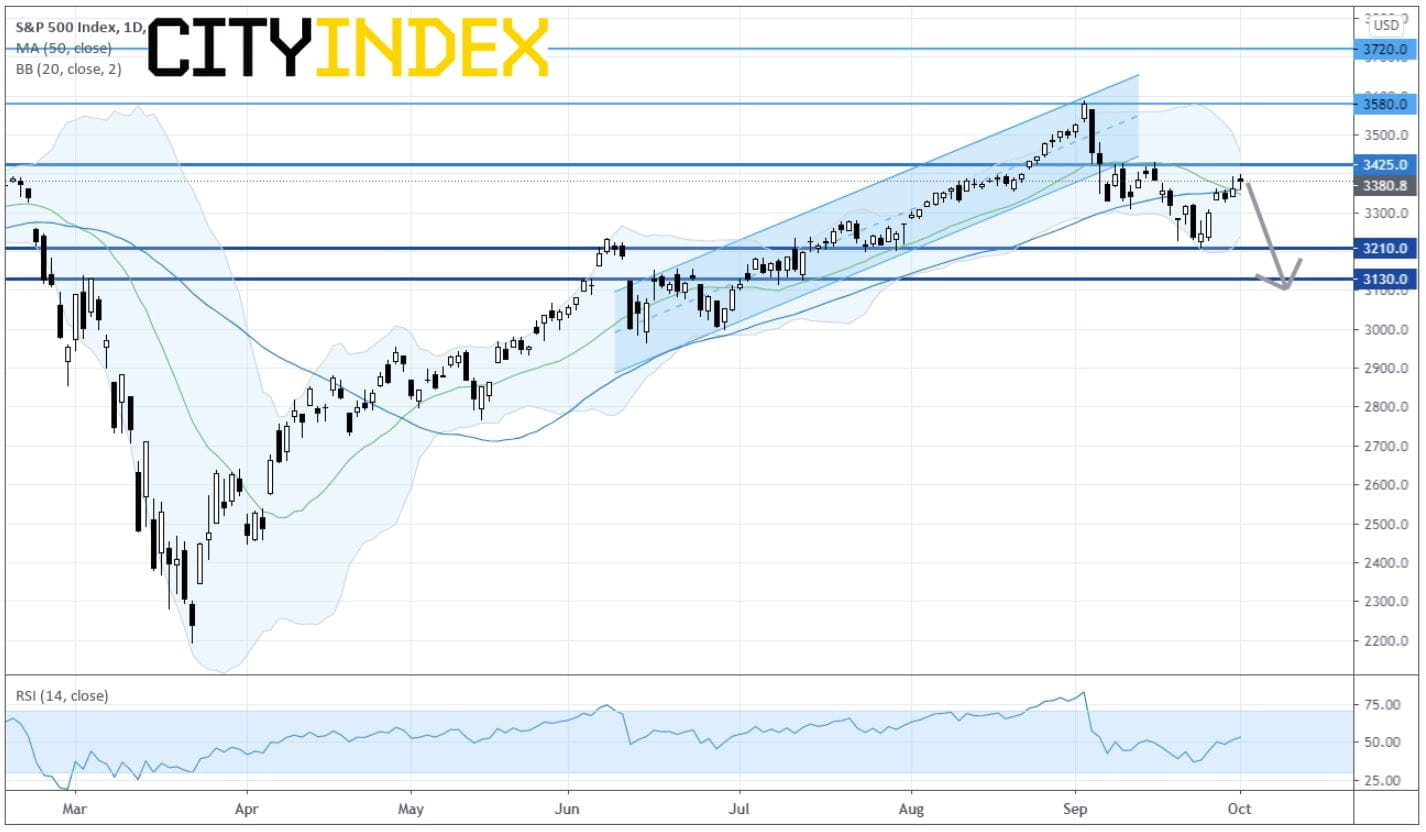
Sources: GAIN Capital, TradingView
The U.S. Labor Department reported that Initial Jobless Claims fell to 837,000 for the week ended September 26 (850,000 expected). Meanwhile, investors are eyeing closely the September Jobs Report due later today (an addition of 872,000 Nonfarm Payrolls, a drop in Jobless Rate to 8.2% expected).
Automobiles & Components (+2.18%), Retailing (+1.75%) and Media (+1.64%) sectors performed the best. Nordstrom (JWN +5.70%), Under Armour (UAA +5.61%), Coty (COTY +5.56%) and Netflix (NFLX +5.50%) were top gainers. Energy and related stocks, such as Halliburton (HAL -8.09%), Valero Energy (VLO -7.44%) and Marathon Petroleum (MPC -5.73%), lost big along with slumping oil prices.
Approximately 61% (59% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 49% (37% in the prior session) were trading above their 20-day moving average.
Official data showed that Personal Income slipped 2.7% on month in August (-2.5% expected). The Markit U.S. Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 in September (53.5 expected).
European stocks closed mixed. The Stoxx Europe 600 Index rose 0.20%, France's CAC 40 climbed 0.43% and the U.K.'s FTSE 100 was up 0.23%, while Germany's DAX 30 fell 0.23%,
In Japan, the Tokyo Stock Exchange halted all stock trading for an entire day Thursday citing a technical glitch. Normal trading is expected to resume on Friday.
The benchmark U.S. 10-year Treasury yield was little changed at 0.679%.
Spot gold rebounded $20 to $1,906 an ounce.
Crude oil encountered a sell-off for the second time this week. U.S. WTI crude oil futures (November) plunged 3.7% to $48.72 a barrel.
On the forex front, the U.S. dollar still lacked upward momentum. The ICE Dollar Index eased further to 93.72, extending its losing streak to a fourth session.
EUR/USD rose 0.24% to 1.1728. The Markit Germany Manufacturing Purchasing Managers' Index (PMI) for September posted at 56.4 (lower than 56.6 expected), and the Markit France Manufacturing PMI at 51.2 (higher than 50.9 expected).
GBP/USD declined 0.21% to 1.2892, halting a three-day rally. The Markit U.K. Manufacturing PMI for September was reported at 54.1 (lower than 54.3 expected).
USD/JPY edged up to 105.52. The Bank of Japan Tankan Large Manufacturers Index posted -27 for the third quarter (-24 expected) and the Outlook Index was -17 (-16 expected).
AUD/USD gained 0.31% to 0.7184, posting a four-day winning streak.
S&P 500 Index: Daily Chart
Sources: GAIN Capital, TradingView
The U.S. Labor Department reported that Initial Jobless Claims fell to 837,000 for the week ended September 26 (850,000 expected). Meanwhile, investors are eyeing closely the September Jobs Report due later today (an addition of 872,000 Nonfarm Payrolls, a drop in Jobless Rate to 8.2% expected).
Automobiles & Components (+2.18%), Retailing (+1.75%) and Media (+1.64%) sectors performed the best. Nordstrom (JWN +5.70%), Under Armour (UAA +5.61%), Coty (COTY +5.56%) and Netflix (NFLX +5.50%) were top gainers. Energy and related stocks, such as Halliburton (HAL -8.09%), Valero Energy (VLO -7.44%) and Marathon Petroleum (MPC -5.73%), lost big along with slumping oil prices.
Approximately 61% (59% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 49% (37% in the prior session) were trading above their 20-day moving average.
Official data showed that Personal Income slipped 2.7% on month in August (-2.5% expected). The Markit U.S. Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 in September (53.5 expected).
European stocks closed mixed. The Stoxx Europe 600 Index rose 0.20%, France's CAC 40 climbed 0.43% and the U.K.'s FTSE 100 was up 0.23%, while Germany's DAX 30 fell 0.23%,
In Japan, the Tokyo Stock Exchange halted all stock trading for an entire day Thursday citing a technical glitch. Normal trading is expected to resume on Friday.
The benchmark U.S. 10-year Treasury yield was little changed at 0.679%.
Spot gold rebounded $20 to $1,906 an ounce.
Crude oil encountered a sell-off for the second time this week. U.S. WTI crude oil futures (November) plunged 3.7% to $48.72 a barrel.
On the forex front, the U.S. dollar still lacked upward momentum. The ICE Dollar Index eased further to 93.72, extending its losing streak to a fourth session.
EUR/USD rose 0.24% to 1.1728. The Markit Germany Manufacturing Purchasing Managers' Index (PMI) for September posted at 56.4 (lower than 56.6 expected), and the Markit France Manufacturing PMI at 51.2 (higher than 50.9 expected).
GBP/USD declined 0.21% to 1.2892, halting a three-day rally. The Markit U.K. Manufacturing PMI for September was reported at 54.1 (lower than 54.3 expected).
USD/JPY edged up to 105.52. The Bank of Japan Tankan Large Manufacturers Index posted -27 for the third quarter (-24 expected) and the Outlook Index was -17 (-16 expected).
AUD/USD gained 0.31% to 0.7184, posting a four-day winning streak.
On Thursday, U.S. stocks advanced further. The Dow Jones Industrial Average edged up 35 points (+0.13%) to 27816, the S&P 500 gained 17 points (+0.53%) to 3380, and the Nasdaq 100 jumped 165 points (+1.45%) to 11583.
S&P 500 Index: Daily Chart

Sources: GAIN Capital, TradingView
The U.S. Labor Department reported that Initial Jobless Claims fell to 837,000 for the week ended September 26 (850,000 expected). Meanwhile, investors are eyeing closely the September Jobs Report due later today (an addition of 872,000 Nonfarm Payrolls, a drop in Jobless Rate to 8.2% expected).
Automobiles & Components (+2.18%), Retailing (+1.75%) and Media (+1.64%) sectors performed the best. Nordstrom (JWN +5.70%), Under Armour (UAA +5.61%), Coty (COTY +5.56%) and Netflix (NFLX +5.50%) were top gainers. Energy and related stocks, such as Halliburton (HAL -8.09%), Valero Energy (VLO -7.44%) and Marathon Petroleum (MPC -5.73%), lost big along with slumping oil prices.
Approximately 61% (59% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 49% (37% in the prior session) were trading above their 20-day moving average.
Official data showed that Personal Income slipped 2.7% on month in August (-2.5% expected). The Markit U.S. Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 in September (53.5 expected).
European stocks closed mixed. The Stoxx Europe 600 Index rose 0.20%, France's CAC 40 climbed 0.43% and the U.K.'s FTSE 100 was up 0.23%, while Germany's DAX 30 fell 0.23%,
In Japan, the Tokyo Stock Exchange halted all stock trading for an entire day Thursday citing a technical glitch. Normal trading is expected to resume on Friday.
The benchmark U.S. 10-year Treasury yield was little changed at 0.679%.
Spot gold rebounded $20 to $1,906 an ounce.
Crude oil encountered a sell-off for the second time this week. U.S. WTI crude oil futures (November) plunged 3.7% to $48.72 a barrel.
On the forex front, the U.S. dollar still lacked upward momentum. The ICE Dollar Index eased further to 93.72, extending its losing streak to a fourth session.
EUR/USD rose 0.24% to 1.1728. The Markit Germany Manufacturing Purchasing Managers' Index (PMI) for September posted at 56.4 (lower than 56.6 expected), and the Markit France Manufacturing PMI at 51.2 (higher than 50.9 expected).
GBP/USD declined 0.21% to 1.2892, halting a three-day rally. The Markit U.K. Manufacturing PMI for September was reported at 54.1 (lower than 54.3 expected).
USD/JPY edged up to 105.52. The Bank of Japan Tankan Large Manufacturers Index posted -27 for the third quarter (-24 expected) and the Outlook Index was -17 (-16 expected).
AUD/USD gained 0.31% to 0.7184, posting a four-day winning streak.
S&P 500 Index: Daily Chart
Sources: GAIN Capital, TradingView
The U.S. Labor Department reported that Initial Jobless Claims fell to 837,000 for the week ended September 26 (850,000 expected). Meanwhile, investors are eyeing closely the September Jobs Report due later today (an addition of 872,000 Nonfarm Payrolls, a drop in Jobless Rate to 8.2% expected).
Automobiles & Components (+2.18%), Retailing (+1.75%) and Media (+1.64%) sectors performed the best. Nordstrom (JWN +5.70%), Under Armour (UAA +5.61%), Coty (COTY +5.56%) and Netflix (NFLX +5.50%) were top gainers. Energy and related stocks, such as Halliburton (HAL -8.09%), Valero Energy (VLO -7.44%) and Marathon Petroleum (MPC -5.73%), lost big along with slumping oil prices.
Approximately 61% (59% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 49% (37% in the prior session) were trading above their 20-day moving average.
Official data showed that Personal Income slipped 2.7% on month in August (-2.5% expected). The Markit U.S. Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 in September (53.5 expected).
European stocks closed mixed. The Stoxx Europe 600 Index rose 0.20%, France's CAC 40 climbed 0.43% and the U.K.'s FTSE 100 was up 0.23%, while Germany's DAX 30 fell 0.23%,
In Japan, the Tokyo Stock Exchange halted all stock trading for an entire day Thursday citing a technical glitch. Normal trading is expected to resume on Friday.
The benchmark U.S. 10-year Treasury yield was little changed at 0.679%.
Spot gold rebounded $20 to $1,906 an ounce.
Crude oil encountered a sell-off for the second time this week. U.S. WTI crude oil futures (November) plunged 3.7% to $48.72 a barrel.
On the forex front, the U.S. dollar still lacked upward momentum. The ICE Dollar Index eased further to 93.72, extending its losing streak to a fourth session.
EUR/USD rose 0.24% to 1.1728. The Markit Germany Manufacturing Purchasing Managers' Index (PMI) for September posted at 56.4 (lower than 56.6 expected), and the Markit France Manufacturing PMI at 51.2 (higher than 50.9 expected).
GBP/USD declined 0.21% to 1.2892, halting a three-day rally. The Markit U.K. Manufacturing PMI for September was reported at 54.1 (lower than 54.3 expected).
USD/JPY edged up to 105.52. The Bank of Japan Tankan Large Manufacturers Index posted -27 for the third quarter (-24 expected) and the Outlook Index was -17 (-16 expected).
AUD/USD gained 0.31% to 0.7184, posting a four-day winning streak.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.
Gold Price Forecast: XAU/USD Plunges 12.4% Toward Critical Support 10 1 2026
Softer inflation has revived expectations for a Fed pause, but Friday’s payrolls could put gold’s recovery prospects to the test.

US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.