




ASX 200 analysis: I’m not banking on a record high despite softer CPI
The ASX 200 index is eyeing a record high. But with SPI 200 futures dragging its heels below resistance looms and the Fed unlikely to cut soon, an immediate breakout is not on my horizon. Even though an eventual breakout seems inevitable.
Share this:
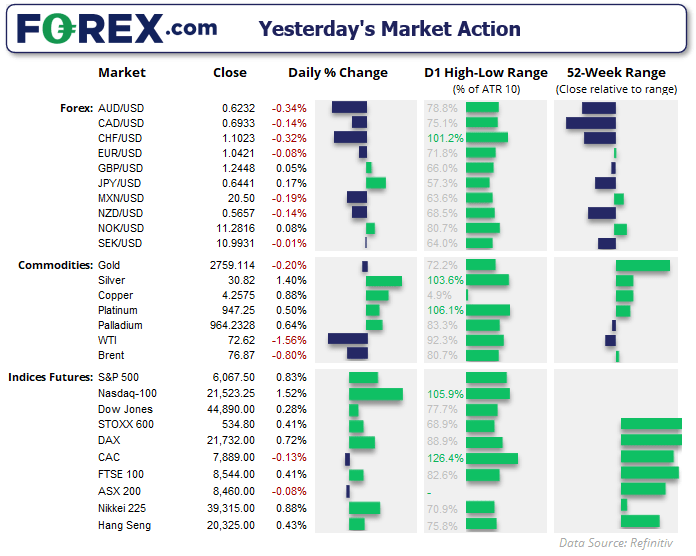
Central Bank policies regained the limelight this week, with Australia’s softer-than-expected CPI figures for Q4 paving the way for the RBA to cut rates by 25bp in February. The 3.2% y/y print for trimmed mean placed it beneath the consensus and RBA’s own forecasts, and the 0.5% q/q trimmed mean print was its slowest rate of growth since Q2 2021 (the post-pandemic average was 0.9%.
The Australian dollar was broadly lower against its FX major peers, with markets now pricing in four cuts this year. While I’ll concede a February cut (or at least signal of a cut) is due, I remain doubtful that we’ll see the level of easing money markets are pricing in. Especially when the Fed are in no rush to cut with an elevated interest rate themselves, as a lower AUD simply imports higher prices. And that could cap gains for the ASX 200, even if it is on the cusp of reaching a new record high.
There were no fireworks after Federal Reserve held interest rates at 4.25 – 4.5%, and as I suspected are in no rush to continue cutting rates. Economic data remains robust, inflationary pressures are building, and we’re yet to see how hawkish Trump’s policies could turn out to be.
The BOC (Bank of Canada) cut their cash rate by -25% to 3% as expected but warned that Trump’s tariffs could cause persistent inflation, lifted their CPI forecast to 2.3% from 2.2% in 2025. Markets now see a 50% chance of another 25bp cut in March, but it seems apparent that we’re at or near the end of the BOC’s easing cycle.

Economic events in focus (AEDT)
- 00:00 – Chinese New Year
- 10:50 – JP foreigner bond, stock purchases
- 11:00 – NZ business confidence (ANZ)
- 11:30 – AU import, export prices, RBA bulletin
- 14:20 – RBA Assistant Governor Jones peaks
- 21:00 – EU GDP, business sentiment (ESI)
- 00:15 – ECB interest rate decision
- 00:30 – US GDP, PCE prices, spending (Q4)
- 00:45 – ECN press conference
Indices FY
ASX 200, SPI 200 technical analysis:
With the ASX 200 cash index honing in on its all-time high, I want to assess the likelihood of it breaking about it. It is reasonable to think that it will eventually, but I am not convinced it will be immediately when I compare it to the ASX 200 futures chart (SPI 200 on the right).
Price action on the SPI shows a less enthusiastic rally to this week’s high, with less upside travel from its 10 and 20-day EMAs. The pullback on Tuesday also tested its 20-day EMA while the ASX 200 cash market remained above its own. A bearish divergence has formed on both of their daily RSI (2), and while the RSI (14) is confirming the move higher on the ASX cash market, a small bearish divergence has formed on the SPI RSI (14). The SPI has also stalled just beneath its monthly R1 pivot.
I therefore assume that upside potential for both is limited over the near-term, and that could favour bears seeking to fade into upside pops.
ASX 200 futures (SPI 200) technical analysis
The 1-hour chart shows the ASX 200 is grinding higher with a bearish divergence on the RSI (14). Support was found at the weekly VPOC (volume point of control), just above the weekly pivot point. A bullish hammer has also formed at the close to suggest a bounce over the near term. But due to the resistance levels overhead including the weekly R1 pivot (8450), monthly R1 pivot (8469) and historical weekly VPOC (8493), the preference is to seek evidence of a swing high or false break around the 8500 level. Bears could seek bearish reversal candles such as inverted hammers, or spikes that close back beneath one of the resistance levels.
Such a move could still allow the ASX 200 cash index to tease its own record high without committing to a full breakout. And should we see a momentum shift at the highs, it could signal a deeper pullback for the SPI 200.
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum
The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.


EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.