


ASX 200 Morning Market Outlook: Westpac (WBC) Leads Big 4 Lower Post-CPI
The ASX 200 slumped after hot CPI data dashed hopes of another RBA cut, with Westpac (WBC) leading the big four banks and Financials sector lower.
Share this:
The ASX 200 suffered its sharpest fall in eight weeks after hotter-than-expected CPI data killed hopes of another RBA rate cut this year. The index broke lower from a coiling pattern near record highs in a clear bearish range expansion day, with volatility spiking to a two-week high. Financials, Industrials, and Health Care led the declines, while Energy and Materials helped cushion the selloff.
View related analysis:
View related analysis:
CPI Shock Sends ASX 200 and Big 4 Banks Lower
ASX 200 Market Snapshot
- The ASX 200 suffered its worst day in eight weeks following a hot CPI report, which killed any hope of another RBA rate cut this year.
- This marked a clear bearish range expansion day from a coiling pattern near its record high, following a weekly spinning top doji and shooting star candle at the same level.
- Its 1.1% high-to-low range made it the most volatile session in two weeks.
- In sector breadth, 72 ASX 200 stocks advanced, 114 declined, and 14 were unchanged.
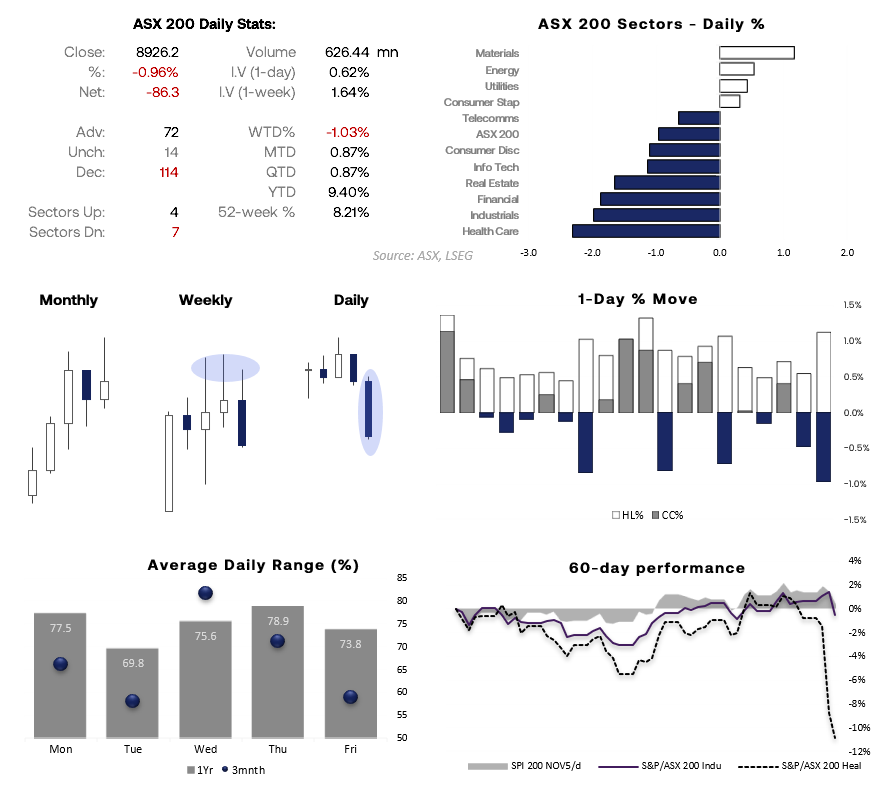
Credit: Chart analysis by Matt Simpson – Source: ASX, LSEG
ASX 200 Sector Analysis
- Seven of the eleven ASX 200 sectors declined, led by Health Care (XHJ), Industrials (XNJ), and Financials (XFJ).
- A bearish engulfing day formed in the Financials (XFJ) sector, with its -1.9% decline marking the worst session in eight weeks, as all four major banks closed lower.
- Industrials (XNJ) fell 2%, its worst day in 18 months, with Transurban (TCL) and Brambles (BXB) both down by a similar amount. Qantas (QAN) dropped 3.2% to a three-month low, also marking its worst day since June.
- Utilities (XUJ) reached a record high for a second consecutive session, with Origin Energy (ORG) climbing to a four-week high and APA Group (APA) to an eight-month high.
- Materials (XMJ) and Energy (XEJ) helped mitigate losses as two of the four sectors to advance on the day.
- Real Estate (XRE) fell 1.65%, its worst performance in eight weeks. Stockland Group (SGP) slumped 3.9% from its record high — also its worst day in 18 months — while Goodman Group (GMG) declined 1.4%, extending its losses for a second session.
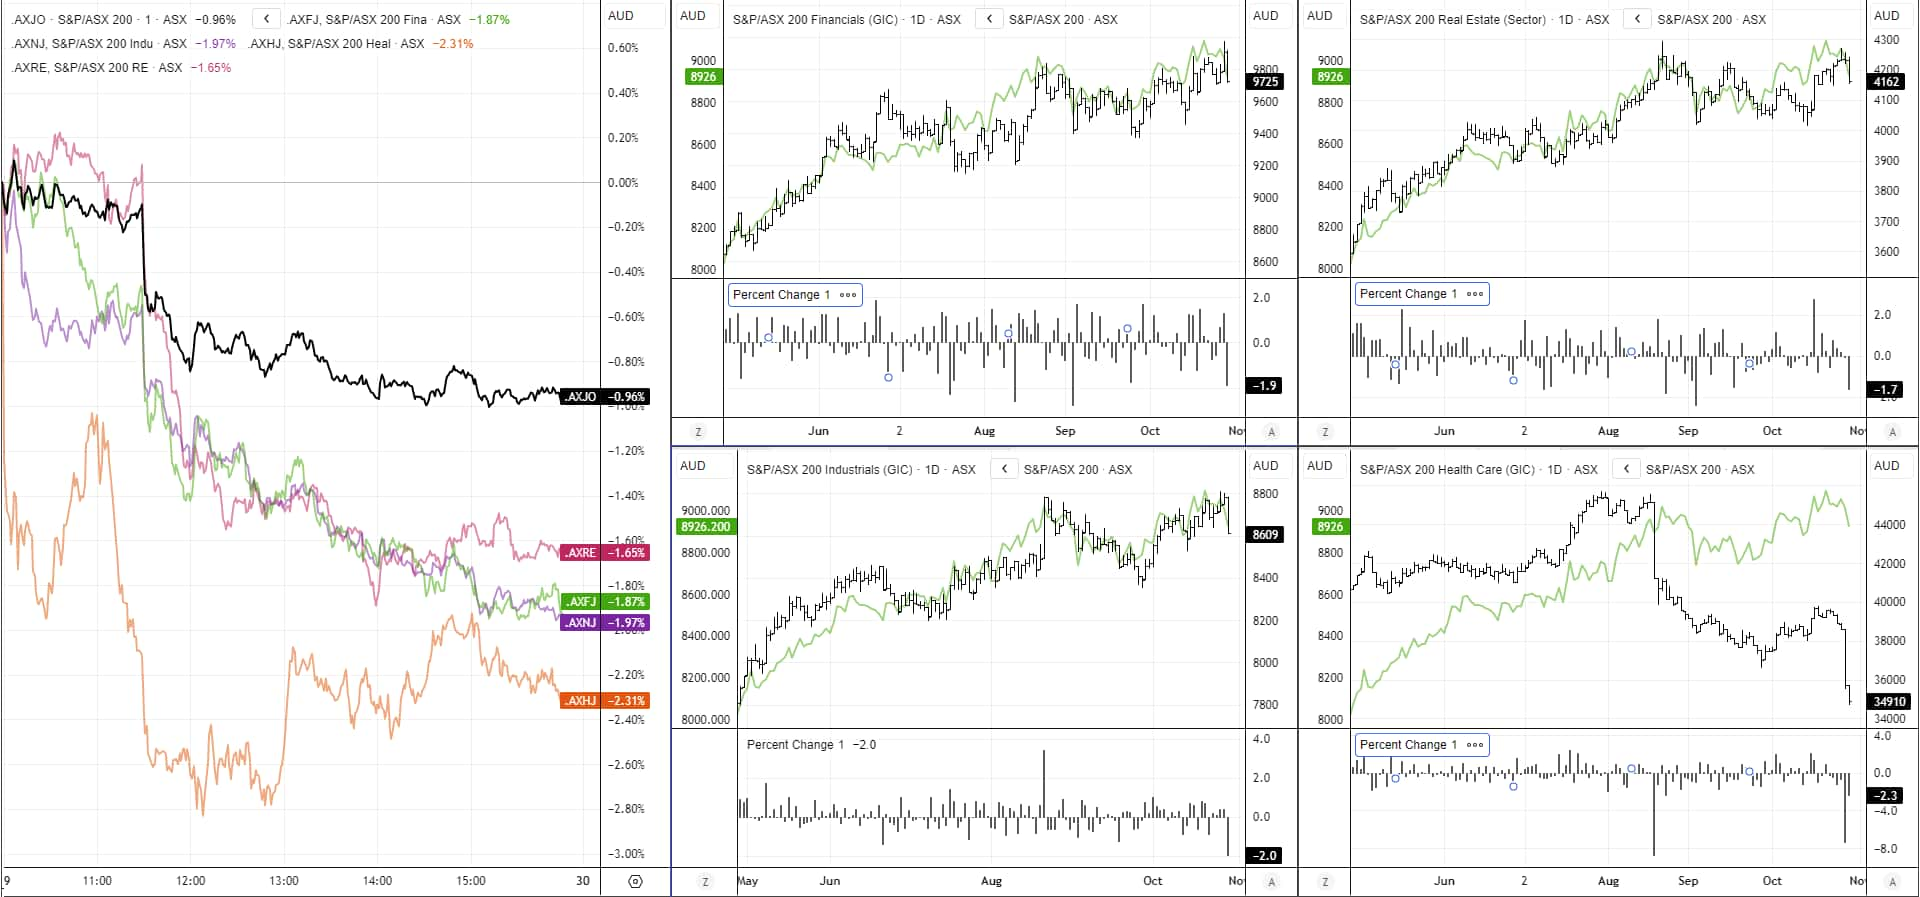
Chart analysis by Matt Simpson - source: ASX, LSEG


Westpac (WBC) Leads Financials Lower
All of the big four ASX banks declined on Wednesday as traders bet that the end of the RBA’s cutting cycle could eat into banking profits.
Westpac (WBC) fell 3% in its worst session in seven weeks, after a second shooting star candle below $40 signalled bulls may have run out of steam. It was the weakest performer of the big four, posting the largest negative delta volume, showing bears were firmly in control. The Westpac/Financials ratio also turned lower, forming a bearish divergence ahead of a potential double top below $40. This could suggest the best of Westpac’s rally is behind it, with a break below the September low potentially next in line.
National Australia Bank (NAB) was the second-weakest performer, down 2.6% by the close. A double top has formed just below $45, and the NAB/Financials ratio has also produced a bearish divergence, hinting at further downside potential.
Commonwealth Bank (CBA) has underperformed the financial sector since June, but the CBA/XFJ ratio has made a higher low while prices have hit new cycle highs. I retain a bullish medium-term bias, expecting dips to remain favourable for buyers.
ANZ Group (ANZ) remains the sector outperformer, showing the most bullish trend structure on both its stock price and ANZ/XFJ ratio. Dips are expected to be shallow and could remain attractive for bulls.
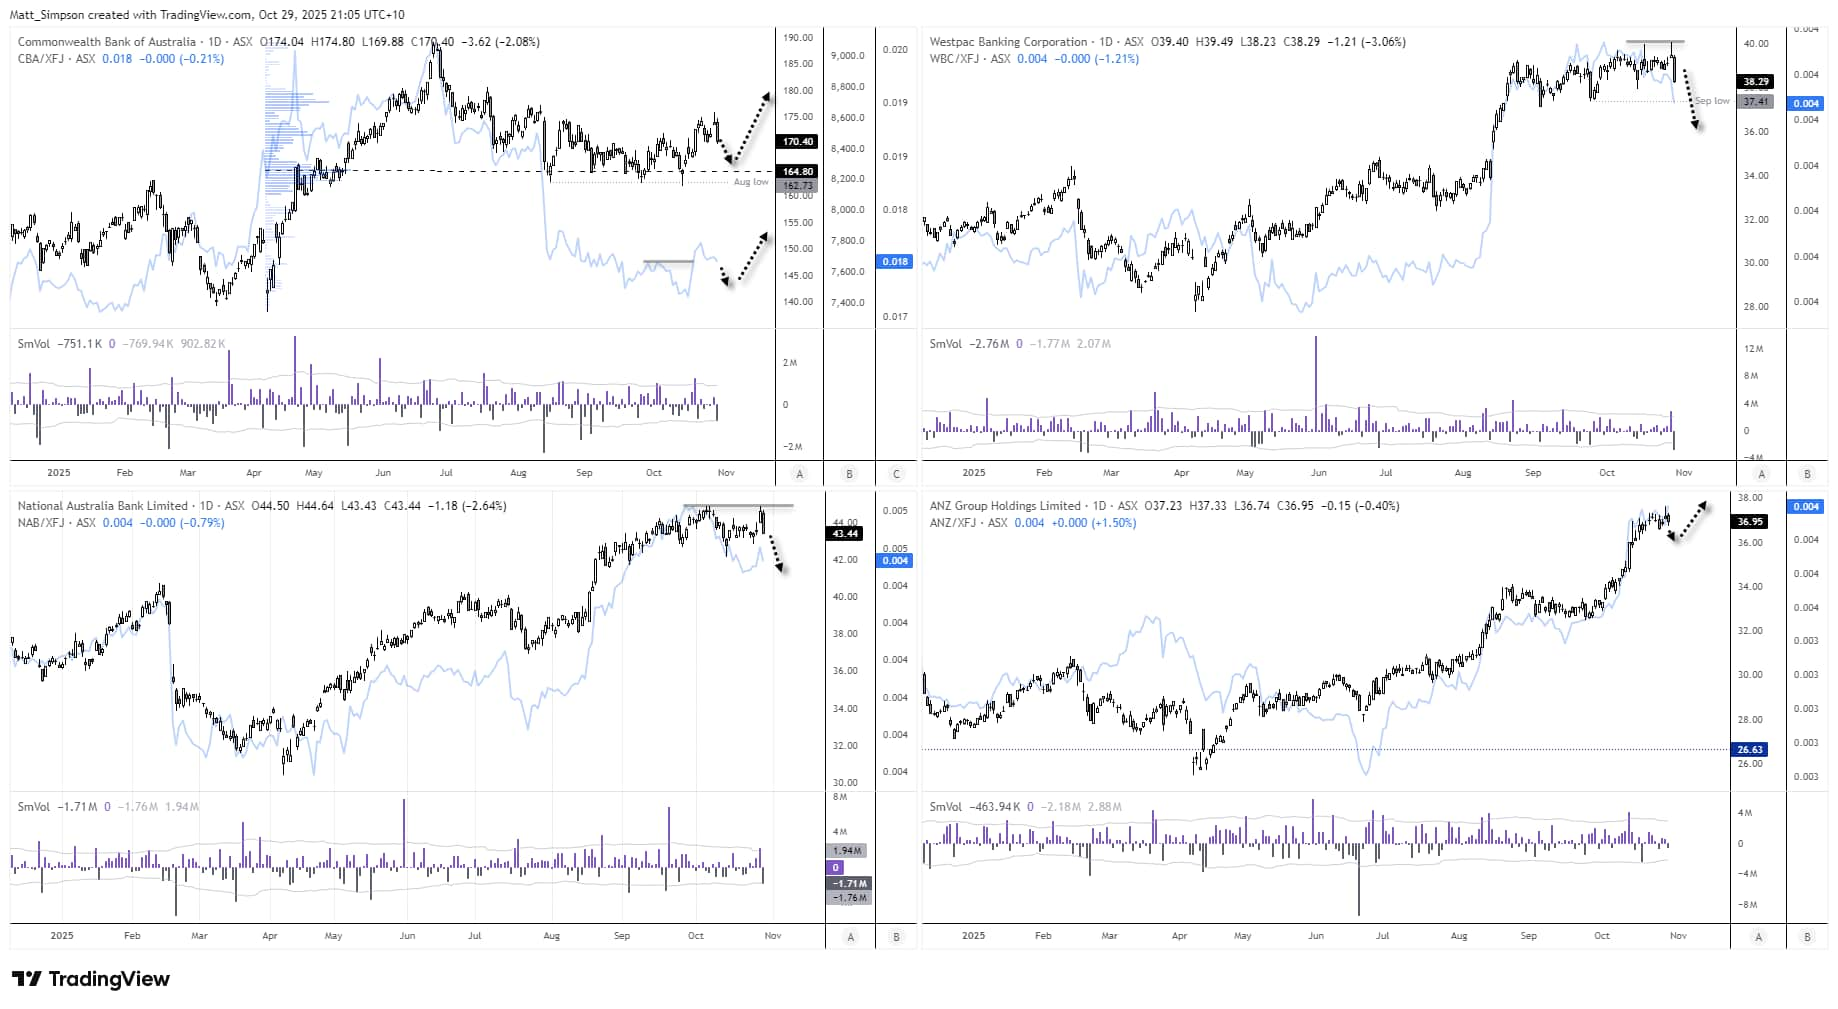
Chart analysis by Matt Simpson - source: TradingView
ASX 200 Futures (SPI 200) Technical Analysis
The market has clearly tipped its hand, with the ASX 200 falling to a 12-day low overnight. Given the bearish signals on weekly candles, the range expansion from the daily coiling pattern near record highs, and continued sectoral weakness, bears may have more to say in the coming weeks.
However, the selloff is already showing early signs of stabilisation above the September VPOC (Volume Point of Control) and October 14 low, while the daily RSI(2) has dipped into oversold territory. Bullish divergences are also forming on the 1-hour RSI(14) and RSI(2). While a dip towards the September VPOC is possible after the open, traders may want to watch for signs of a false break and a countertrend rebound towards the weekly S1 (8945) or 9,000 handle before the next leg lower for the ASX.
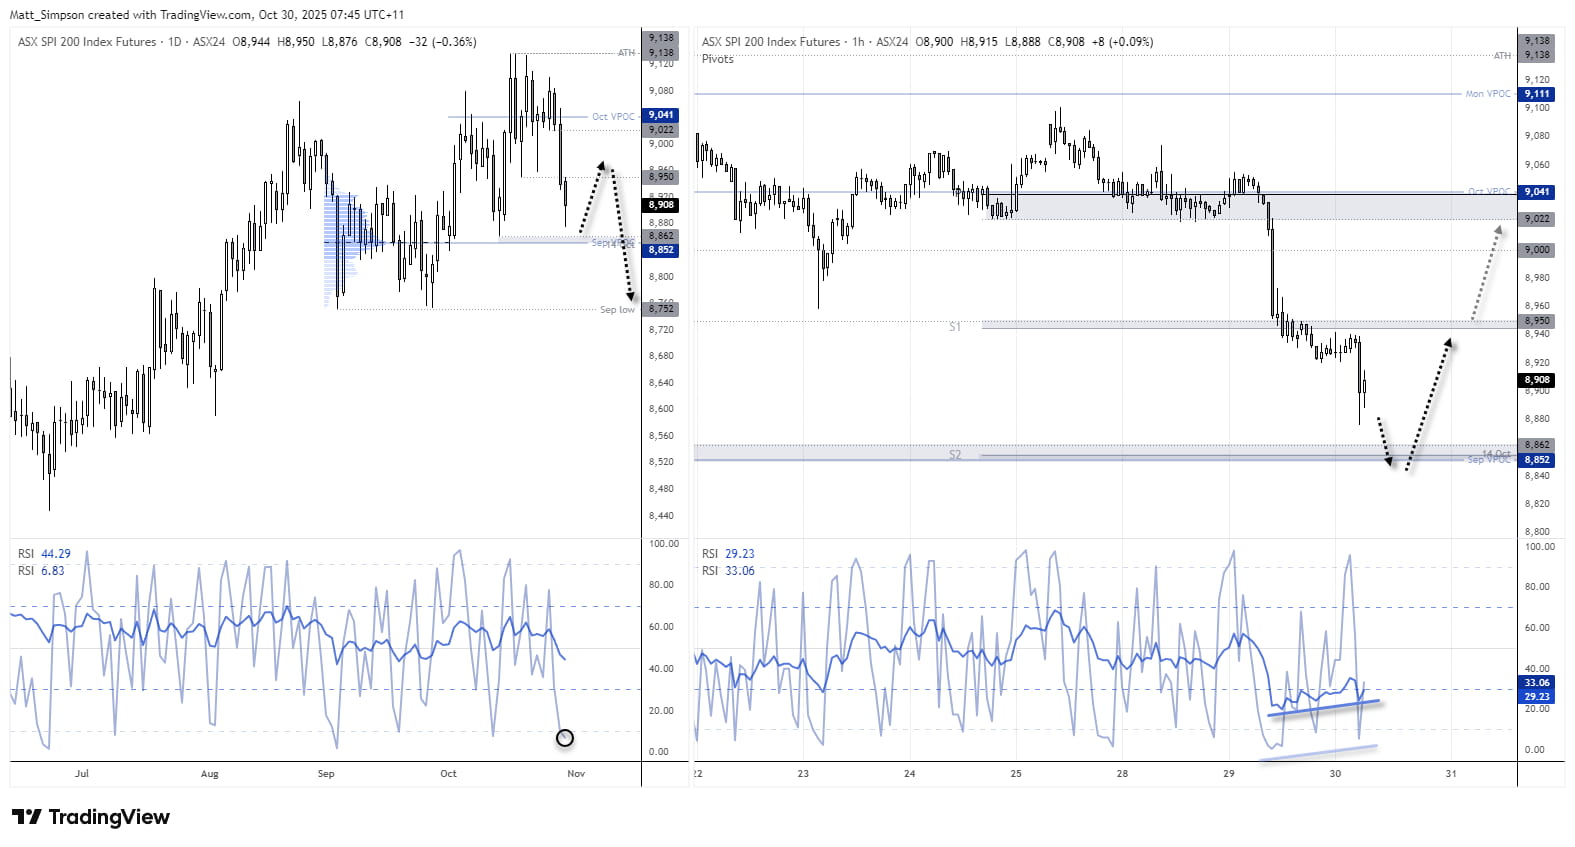
Chart analysis by Matt Simpson - Source: TradingView, ASX SPI 200 Index Futures
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: FOMC and ECB to set the tone
The current backdrop is modestly bearish. On Friday, the EUR/USD closed modestly lower, down for the third consecutive day. The pair also posted a weekly decline after staging a modest recovery attempt in the previous week. Out of the past 8 weeks, the EUR/USD has fallen on 6 occasions. There is not much supporting factors for the single currency right now. So, the upside remains capped.

Silver forecast: metals liquidation drags XAG/USD into $50-55 support
Silver has broken its July low and slipped into a long-term support zone as the selling in precious metals deepens. The chart shows where the metal could bottom, and next week's Fed decision may decide whether it does.
S&P 500 forecast: AI linked stocks remain under pressure
And just like that, it is Friday again and the end of a volatile week. Today offers little on the macro calendar to change the prevailing narrative, leaving markets largely at the mercy of risk appetite, oil prices and the growing unease around the AI trade.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.