



Dow Jones Forecast: DJIA finally at record highs, despite Middle East mixed messaging
U.S. stocks are pointing to a modestly higher open ahead of the long weekend as investors continue to monitor developments in the Middle East.
Share this:
US futures
Dow futures 0.44%, S&P futures 0.25% & Nasdaq futures 0.25%
In Europe
FTSE 0.07% & DAX 0.8%
- U.S rise amid mixed messages from US-Iran and as yields fall
- Treasury yields fall to a weekly low
- Kevin Warsh to be sworn in as Fed Chair
- Oil rises but falls across the week
U.S. stocks at record highs as market weighs Middle East and falling yields
U.S. stocks are pointing to a modestly higher open ahead of the long weekend as investors continue to monitor developments in the Middle East.
Global markets have swung sharply on headlines surrounding the U.S.-Iran war since the conflict began in late February. Hopes of an eventual resolution, alongside continued optimism around the AI trade and resilient corporate earnings, have helped lift U.S. equities back towards record highs.
The Dow Jones Industrial Average was the last of the three major indices to reach a record closing high yesterday, while the S&P 500 and the NASDAQ-100 have been posting fresh record highs regularly since mid-April.
In the latest developments, it appears the U.S. and Iran are edging closer towards a deal, although both sides remain divided over Iran’s uranium stockpile and control of the Strait of Hormuz. These remain key sticking points that would need to be resolved before any agreement can be finalised.
Investors have remained focused on the inflationary impact of elevated oil prices, which have pushed bond yields higher globally and weighed on risk appetite. However, Treasury yields are easing back on Friday, with the 10-year yield falling towards a weekly low near 4.5%, helping improve sentiment slightly.
Later today, Kevin Warsh will be sworn in as the new Federal Reserve Chair, replacing Jerome Powell at a critical moment for U.S. monetary policy and the broader economy.
The S&P 500 is now on track for its eighth consecutive weekly gain, while the Dow Jones has risen in six of the past eight weeks.
Corporate movers
Estée Lauder is surging in pre-market trade after a potential merger with Spanish beauty group Puig fell through.
The proposed deal would have combined Estée Lauder’s luxury brands, including Clinique and Tom Ford Beauty, with Puig’s portfolio, which includes Charlotte Tilbury and Jean Paul Gaultier. Investors welcomed the collapse in talks, sending Estée Lauder shares 11% higher, while Puig is down 13%.
Dow Jones – technical analysis
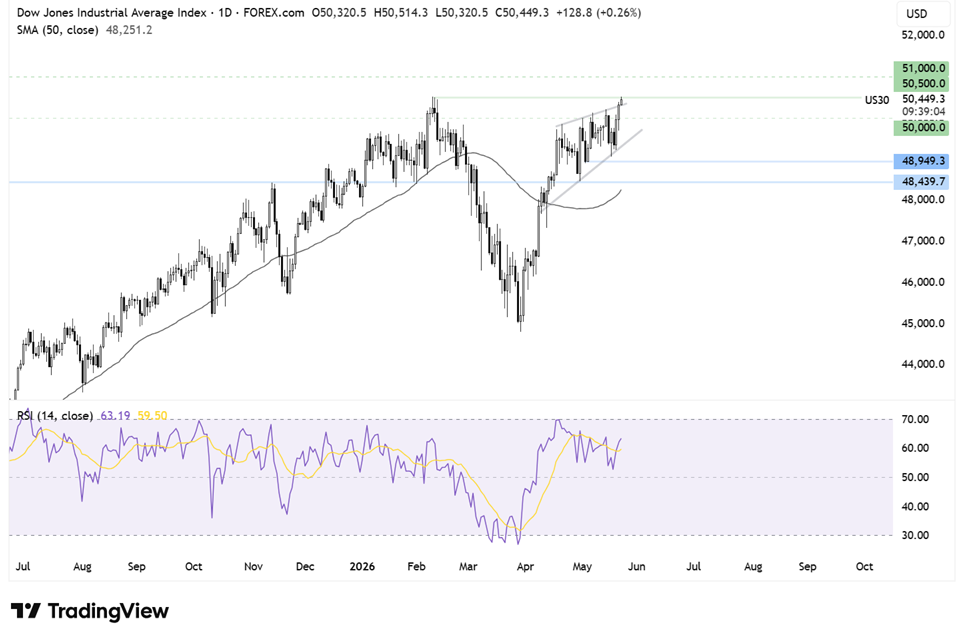
The Dow Jones broke above its rising trendline resistance, validating the breakout from the rising wedge pattern and climbing towards 50,500, matching the record high reached in February.
Buyers will look for a move above this level to extend gains towards 51,000 as the next logical upside target.
Immediate support sits at 50,300 around the rising trendline support, while below here the 50,000 psychological level comes into focus. A break below 49,300 would move the price back beneath the rising wedge pattern and could open the door towards 49,000.
FX markets – USD rises EUR/USD falls
The U.S. dollar is edging higher and remains on track for modest gains across the week, trading around multi-week highs supported by resilient U.S. data and continued uncertainty surrounding U.S.-Iran negotiations.
EUR/USD is little changed despite German data showing a modest improvement in business sentiment. The IFO business climate index rose to 84.9 in May from 84.5 previously. While the data points to improving sentiment, confidence levels remain historically weak. Separately, ECB policymaker Alexander Di Marco said the central bank may still need to raise rates at its June meeting.
GBP/USD is drifting lower after UK retail sales fell at their fastest pace in almost a year as higher petrol prices weighed on consumer spending. Retail sales volumes dropped 1.3% month-on-month in April, the largest decline since May 2025 and well below expectations for a 0.6% fall. Even so, sterling remains on track for gains of around 0.7% across the week.
Oil rises but remains on track for a weekly decline
Oil prices are moving higher on Friday amid doubts over whether a breakthrough in U.S.-Iran peace talks can be reached soon. Even so, crude remains on track for weekly losses, with WTI down around 5% on the week and Brent lower by roughly 4%.
While a senior Iranian official said the gap between Tehran and Washington had narrowed, and U.S. Secretary of State Marco Rubio pointed to some encouraging signs, both sides remain divided over Iran’s uranium stockpile and future control of the Strait of Hormuz.
The conflict has disrupted around 14 million barrels per day of oil supply, equivalent to roughly 14% of global production. Even if the conflict were resolved immediately, oil flows are unlikely to fully normalise before 2027.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.


DAX Tests 26,000 as Markets Await AMD and US Election Results
The DAX remains close to 26,000 points after extending its recovery, but the market's attention is shifting away from geopolitics and back toward earnings, economic data and US politics. Reports from Bayer, Lufthansa and Fresenius Medical Care highlight a market increasingly rewarding profit growth while punishing weak guidance. With US midterm elections, JOLTS job openings and AMD earnings on today's agenda, the next move in equities may depend less on technicals and more on whether earnings and economic data justify current valuations.

US Midterm Forecast: The Key Risks for Traders to Watch Through the US Elections
Prediction markets are pricing in nearly 75% odds of a Democratic sweep in this week’s US midterm elections, a development that would result in a split from the single party Republican rule of the past two years - what will it mean for markets?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.