




European Open: Asian markets traded lower, gold eyes break of $2000
Asian equity markets took the inevitable route of tracking Wall Street lower, yet bearish volatility has receded somewhat.
Share this:

Asian Indices:
- Australia's ASX 200 index fell by -58.3 points (-0.83%) and currently trades at 6,980.30
- Japan's Nikkei 225 index has fallen by -294.04 points (-1.17%) and currently trades at 25,916.60
- Hong Kong's Hang Seng index has fallen by -121.71 points (-0.58%) and currently trades at 20,935.92
- China's A50 Index has fallen by -118.88 points (-0.85%) and currently trades at 13,785.39
UK and Europe:
- UK's FTSE 100 futures are currently down -44 points (-0.63%), the cash market is currently estimated to open at 6,915.48
- Euro STOXX 50 futures are currently down -52.5 points (-1.49%), the cash market is currently estimated to open at 3,459.72
- Germany's DAX futures are currently down -183 points (-1.42%), the cash market is currently estimated to open at 12,651.65
US Futures:
- DJI futures are currently down -62 points (-0.19%)
- S&P 500 futures are currently down -25 points (-0.19%)
- Nasdaq 100 futures are currently down -5.75 points (-0.14%)


We do not feel confidence enough to say it will be a Turnaround Tuesday, but the lack of bearish follow-through should at least be noted. US futures trade around -0.1% lower, which is by no means setting off alarm bells. But as we have seen since Russia invaded Ukraine, headlines retain the ability to quickly flip sentiment and increase volatility at the tap of a keyboard.
FTSE 350: Market Internals

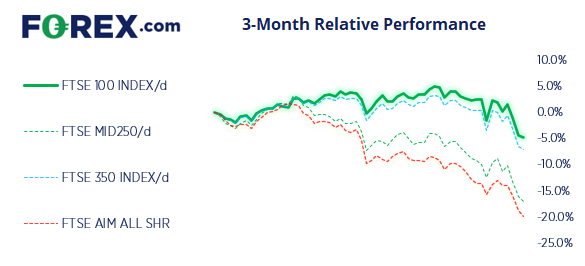
FTSE 350: 3891.56 (-0.40%) 07 March 2022
- 105 (29.91%) stocks advanced and 243 (69.23%) declined
- 3 stocks rose to a new 52-week high, 158 fell to new lows
- 15.1% of stocks closed above their 200-day average
- 8.83% of stocks closed above their 50-day average
- 10.83% of stocks closed above their 20-day average
Outperformers:
- + 32.98% - Petropavlovsk PLC (POG.L)
- + 28.33% - EVRAZ plc (EVRE.L)
- + 8.05% - Shell PLC (SHEL.L)
Underperformers:
- -22.81% - Oxford Instruments PLC (OXIG.L)
- -9.94% - Hammerson PLC (HMSO.L)
- -8.30% - Baltic Classifieds Group PLC (BCG.L)
Oil holds the key to equity market direction
If we had to use one market to help gauge the reaction of others today, it would be oil. As it was the sharp rise in oil which triggered the sell-off in equities as traders priced in stagflation worries once again. Should oil prices stabilise then it should remove some selling pressure across equity markets. And should the West submit to the idea it will be a long and drawn-out process to wean themselves off-of Russian energy, oil prices could tail off and provide further support for equites. And makes Thursday’s meeting, where European leaders will discuss how to remove Russian energy, a pivotal (and volatile) event.
Russia ‘forecasts’ $300 oil
Russia have since threated to cut European gas supplies if Western allies ban their energy exports. We therefore expect Russia to be quite vocal on the subject leading up to the Versailles meeting. Russia’s claim that oil prices could reach $300 if their energy exports are banned seems far-fetched. It also sounds like a knee-jerk reaction to the West talking of an oil embargo, as Russia were perhaps not expecting it. And knee-jerk reactions can lead to other knee-jerk reactions, so headline risk will be a key driver for markets this week.
Gold remains bid, but $2k caps as resistance
Gold was the only metal to hold onto its market-open gains yesterday, whilst copper and palladium hit record highs before reversing lower. It’s no major surprise that gold met resistance at $2,000 as it is a psychological level, but the fact it closed just beneath it is a sign of strength. Sure, it has pulled back to $1985 but it has done so in an orderly way. It therefore remains bid and, without any good reasons to short at this level, it almost seems inevitable it will break higher this week.


The hourly chart remains in a strong uptrend and has found support at the 50-hour eMA. A potential inverted head and shoulders (H&S) would be confirmed with a break above 2003, which projects a target around 2045. Interim resistance levels would include 2020 and the weekly R1 pivot at 2038.
However, should momentum turn below the 1991 – 2003 resistance zone, it would remove the potential for the H&S but not necessarily remove our bias for an eventual breakout, as it could still be part of a corrective move. We would then look for a higher low to form above 1960 or along trend support.
GBP drifts higher overnight
The pound is the strongest major but the moves appear to be corrective in nature and not tied to any specific event. The Australian dollar is lower against the board as it (potentially overdue) retracement phase gets underway. A notable theme yesterday was that the US dollar regained its safe-haven bid, and also traded higher against the yen and Swiss franc. Although what likely helped soften the franc was a thinly veiled warnings from the SNB that their currency is too high and, therefore, they are likely to intervene to weaken it.
Up Next (Times in GMT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


Gold Update: XAU/USD Remains Under Pressure Even After the NFP Report
As the trading week comes to an end, weakness around gold price action remains evident in the short term. This can be seen in the performance of the past two sessions, where the metal has declined by approximately 0.3%. Although the move has not been particularly aggressive, it highlights that buying pressure continues to struggle to regain control of the market.

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.