


European Open: Swiss inflation, flash PMI and ISM manufacturing reports in focus
Oil prices have stabilised following OPEC’s surprise oil production cut, which now allows traders to switch their focus over to Swiss inflation, flash PMI and ISM reports.
Share this:
Asian Indices:
- Australia's ASX 200 index rose by 39.6 points (0.55%) and currently trades at 7,217.40
- Japan's Nikkei 225 index has risen by 158.88 points (0.57%) and currently trades at 28,200.36
- Hong Kong's Hang Seng index has fallen by -120.57 points (-0.59%) and currently trades at 20,279.54
- China's A50 Index has risen by 9.52 points (0.07%) and currently trades at 13,246.04
UK and Europe:
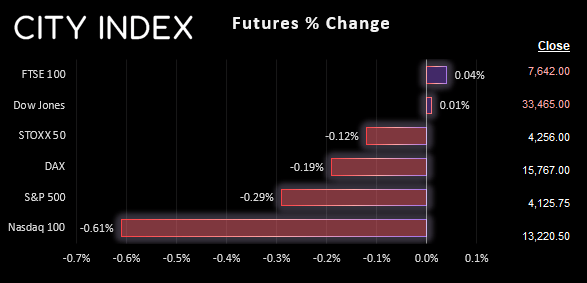
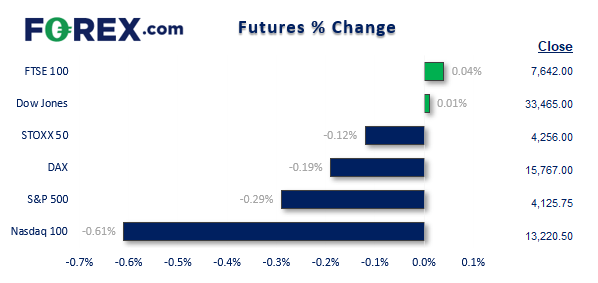
- UK's FTSE 100 futures are currently up 3.5 points (0.05%), the cash market is currently estimated to open at 7,635.24
- Euro STOXX 50 futures are currently down -5 points (-0.12%), the cash market is currently estimated to open at 4,310.05
- Germany's DAX futures are currently down -31 points (-0.2%), the cash market is currently estimated to open at 15,597.84
US Futures:
- DJI futures are currently up 4 points (0.01%)
- S&P 500 futures are currently down -11.75 points (-0.28%)
- Nasdaq 100 futures are currently down -80.75 points (-0.61%)
- Oil gapped aggressively higher at the Asian open and rallied nearly 8%, on news that OPEC+ announced they are cutting oil production by over 1 million barrels per day
- The OPEC move was quickly called “inadvisable” by the US, as it risks a second round of inflation at a time that central authorities have yet to fully deal with the first one
- Gold has fallen around 1% today as investors weigh up the lure of gold as a safe haven asset, versus the potential for higher-for-longer interest rates. Clearly, fears of inflation and higher interest rates has won the argument with gold heading for $1950.
- Given its repeated failed attempts to break above $2000, gold is now vulnerable to a move down to $1900 given the potential for a higher terminal Fed rate that markets are currently pricing in.
- Nasdaq futures are 0.6% lower as tech stocks remain sensitive to higher rates
- The DAX and STOXX are also lower, but to a lesser degree of -0.19% and 0.12% respectively
- China and Hong Kong exchanges were closed due to the Ching Meng Festival between Monday and Wednesday
- PMI across Asia was a little lacklustre, which saw China’s manufacturing PMI stall at 50 (neither expand or contract), Japan’s manufacturing PMI contract at 49.7 (below 51 previous and 51.3 prior) and South Korea’s manufacturing PMI contract at a faster rate of 47.6 (48.5 prior)
I think OPEC’s move has killed the argument for Fed rate cuts and plays into the ‘no cuts this year’ message that Jerome Powell has been peddling. It could be argued that OPEC’s move really is more of a lesson for bond traders than it is for the Fed, as the central bank are all too aware that higher oil prices could bring a second wave of inflation and result in a higher terminal rate further out.
With OPEC reminding markets that they will not hesitate to support oil prices, it’s not impossible to envisage oil hitting the $90-$100 range. And that is a major problem for central banks and governments in the fight against inflation.
A host of PMI reports are released today
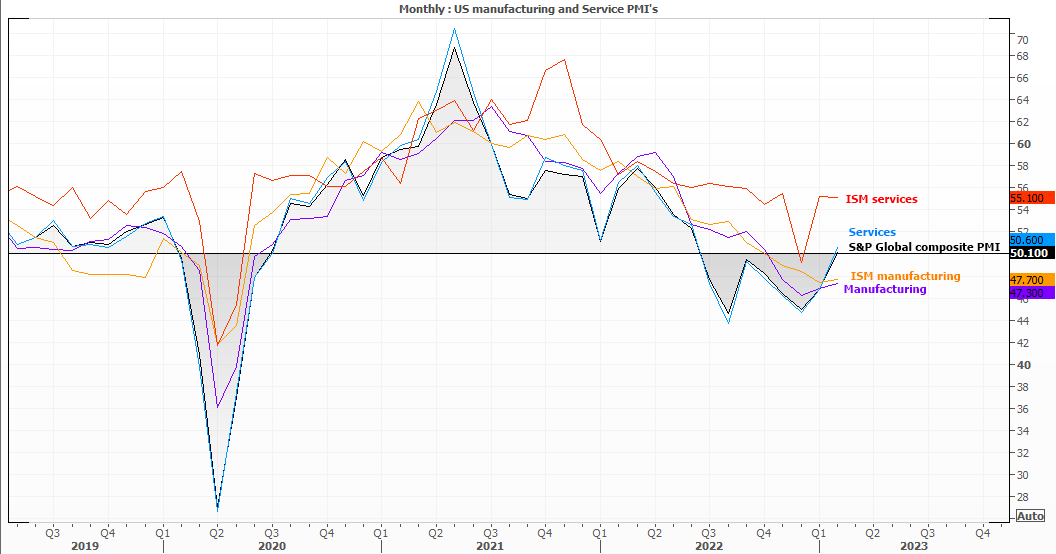
PMI reports provide a forward look at potential growth of a country or region, and today we have flash PMI reports for Europe, UK and the US. If early reports from Asia are anything to go by, we may be in for some softer manufacturing reports or faster rates of contraction. The ‘prices paid’ sub index warrants a look to see if inflation pressures continue to soften, whilst the ‘new orders’ component shows a pipeline of potential out, and can therefor lead the headline figures.
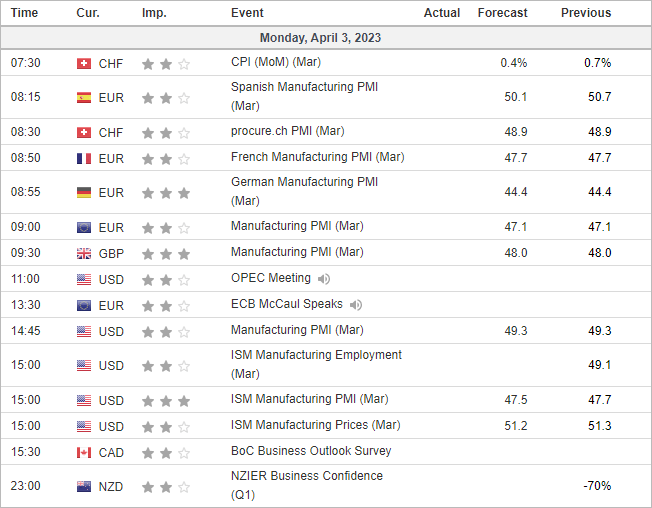
Italy kicks off at 07:45 GMT+1, France and Germany follow at 8:50 and 8:55, the eurozone at 09:00 and the UK at 09:30. Of those mentioned, Italy has the only expansion in February – at the slow rate of 51. Ultimately, we won’t hold our breath for any punchy manufacturing figures today. The ISM report on business is also released at 15:00 for US manufacturing and services.
Swiss CPI also in focus at 07:30
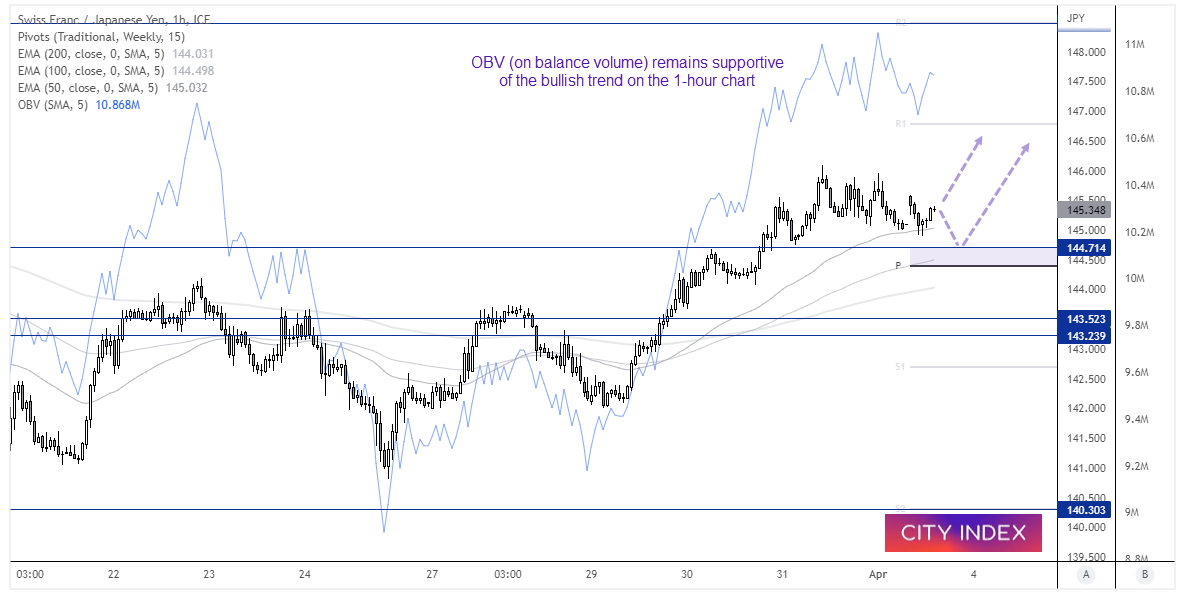
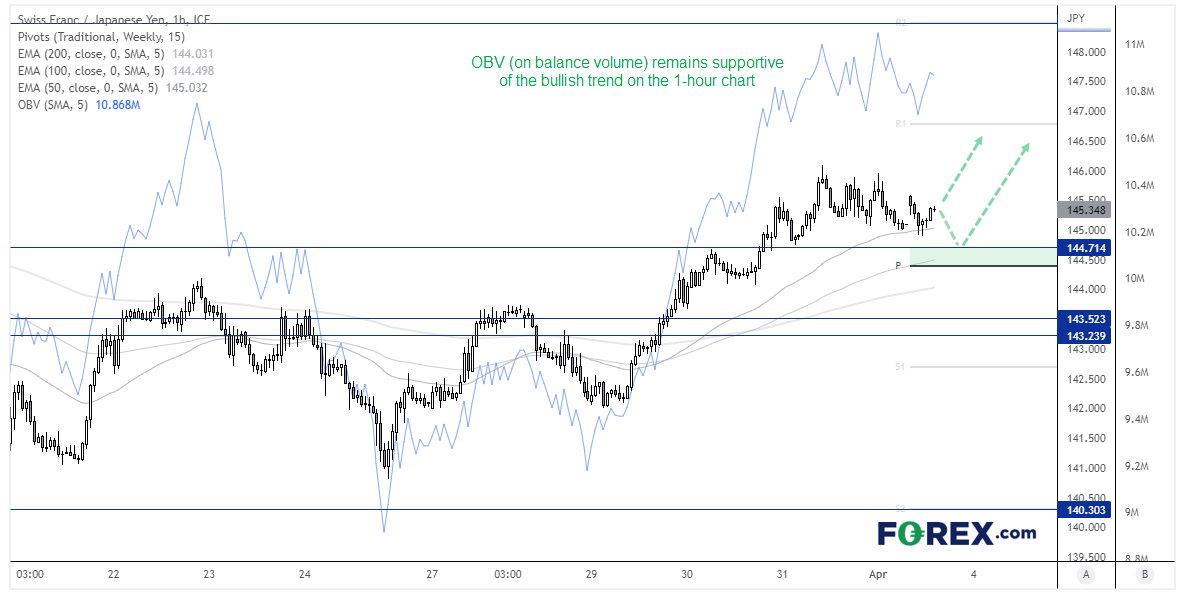
The SNB (Swiss National Bank) delivered a hawkish hike in December, have continued to make hawkish noise since whilst citing high levels of inflation. Therefore, a stronger Swiss inflation report today could cement another SNB hike and further support the Swiss franc. Take note that the yen is currently the weakest major, and a bullish trend has developed on the 1-hour CHF/JPY chart.
Prices are holding above 145 ahead of today’s inflation report, and we’re looking for a bullish breakout from its current consolidation and move up to the weekly R1 pivot around 146.60.
Economic events up next (Times in GMT+1)
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY bulls back in business as AI trade roars back
The AI investment boom rolls on, with Anthropic and Meta helping revive enthusiasm across Wall Street. USD/JPY has responded with a bullish reversal pattern, putting its former trading range back in focus ahead of major central bank decisions and technology earnings.

EUR/USD weekly outlook: FOMC and ECB to set the tone
The current backdrop is modestly bearish. On Friday, the EUR/USD closed modestly lower, down for the third consecutive day. The pair also posted a weekly decline after staging a modest recovery attempt in the previous week. Out of the past 8 weeks, the EUR/USD has fallen on 6 occasions. There is not much supporting factors for the single currency right now. So, the upside remains capped.

Silver forecast: metals liquidation drags XAG/USD into $50-55 support
Silver has broken its July low and slipped into a long-term support zone as the selling in precious metals deepens. The chart shows where the metal could bottom, and next week's Fed decision may decide whether it does.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.