



GBP/USD, GBP/AUD: Sterling Rally Faces a BoE Reality Check
Sterling faces a reality check as the BoE prepares to hike rates. GBP/USD and GBP/AUD approach resistance, leaving bulls vulnerable to dovish guidance.
Share this:
The Bank of England looks set to deliver its first rate hike since August 2023, but a 25bp increase may not be enough to satisfy sterling bulls. With markets still pricing further tightening despite a recent dovish repricing, the MPC's voting split, updated economic forecasts and forward guidance could determine whether GBP/USD and GBP/AUD extend their rallies or retreat from resistance.
View related analysis:
- AUD/USD Remains Vulnerable Despite US Dollar Weakness Amid Midterms
- Yen Weakness Fuels USD/JPY and EUR/JPY Breakouts Ahead of Midterms
- RBA Hikes to 4.85%, but Split Vote and Softer Guidance Hit AUD/USD
- Forex, Gold and Oil Outlook: FX Crosses May Have the Edge
- Yen Bulls Loaded Up into BOJ as Euro Shorts Hit 11-Year Extreme | COT report
Sterling Faces a BoE Reality Check as GBP/USD and GBP/AUD Test Resistance
The Bank of England is expected to raise its Bank Rate by 25 basis points to 4.00% today, its first increase since August 2023. However, with a hike largely priced in, the bigger market reaction could come from the Monetary Policy Committee's (MPC) voting split, updated economic forecasts and guidance on further tightening.
The BoE faces an increasingly difficult balancing act: inflation is running well above target following the energy shock, but the labour market remains relatively weak. The central question is whether policymakers see today's expected hike as the beginning of a tightening cycle or an insurance move against persistent inflation.
September's meeting revealed growing hawkish pressure, with three MPC members voting to raise rates against six favouring a hold. Since then, prolonged conflict in the Middle East has intensified inflation concerns, while September CPI rose to 3.5%, exceeding the BoE's July forecast of 3.0%. At least two of September's hold voters would need to switch sides for today's expected hike, making the voting split particularly important for assessing the likelihood of further tightening.
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
BoE Rate Expectations Ease Ahead of November Decision
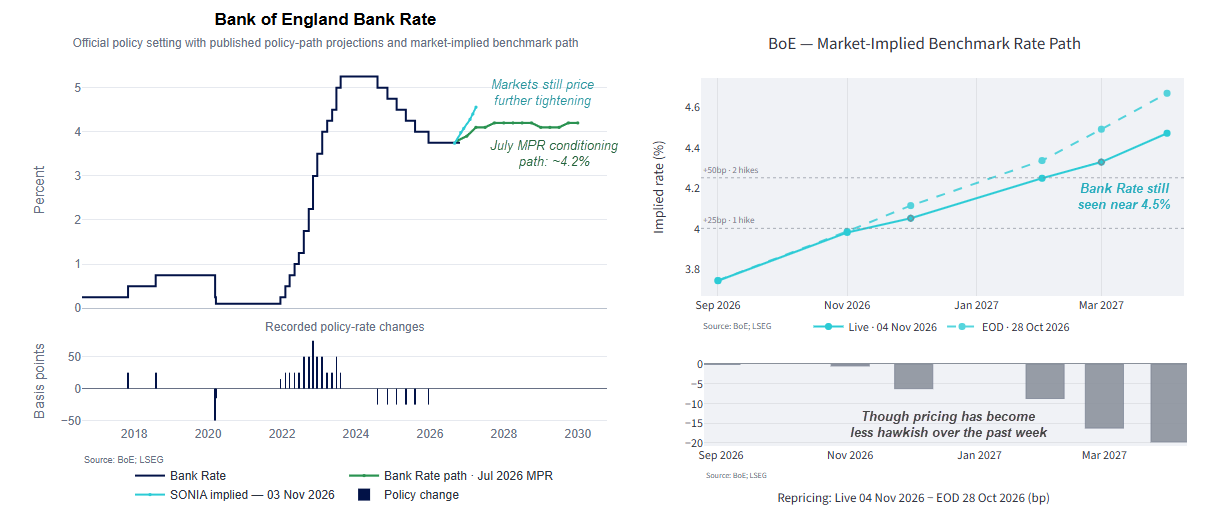
Markets remain considerably more hawkish than the rate path used to condition the BoE's July projections, leaving scope for GBP weakness should the BoE deliver a less-hawkish-than-expected rate hike.
Although markets continue to favour further tightening, expectations have eased noticeably over the past week. The SONIA curve has shifted lower since 28 October, with around 20bp of tightening removed from expectations by April 2027. Nevertheless, markets still imply Bank Rate rising towards 4.5% by April, compared with the roughly 4.2% path underpinning the BoE's July Monetary Policy Report.
This suggests traders are already scaling back some of their more aggressive tightening bets, leaving sterling sensitive to the MPC's forward guidance. A dovish hike could accelerate that repricing and weigh on GBP, particularly if policymakers emphasise weakening economic activity or signal that further rate increases are less likely.

Three things to watch in the Monetary Policy Report
- Inflation forecasts: The BoE's July projections showed inflation peaking around 3.2% in late 2026 before gradually returning towards its 2% target. An upward revision or a delayed return to target would strengthen the case for further tightening.
- Unemployment and growth forecasts: Any deterioration could support the case for a pause following November's hike.
- Second-round inflation effects: Evidence of higher wage settlements or persistent services inflation could make the MPC less comfortable with leaving Bank Rate at 4%.
- Inflation risks and fiscal policy: Beyond its central forecasts, the MPC's assessment of persistent energy shocks, second-round inflation risks and the government's recent Budget could provide further clues about the likely path of interest rates.

GBP/USD Bulls Eye September VPOC Before May High
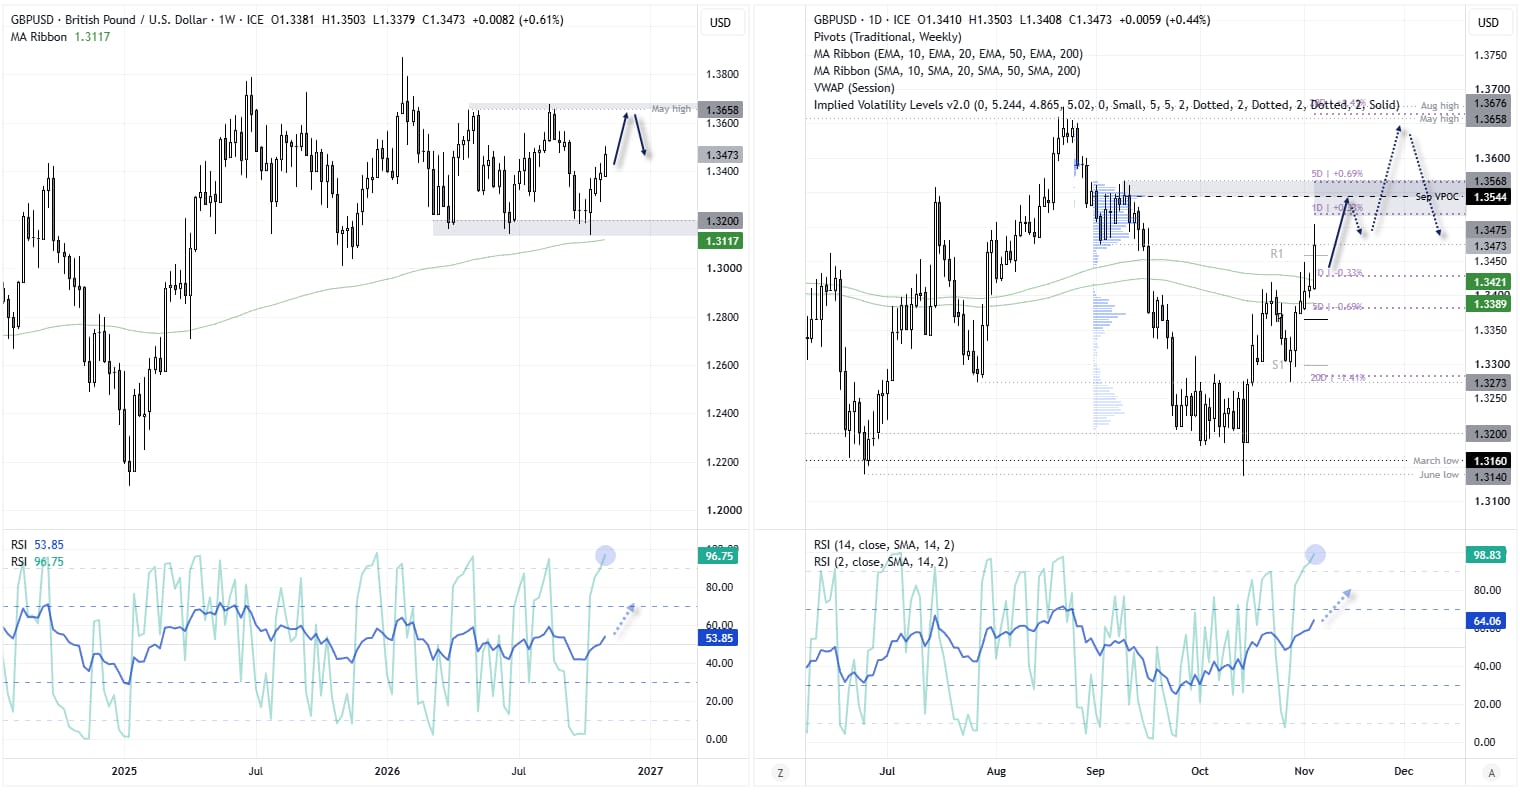
GBP/USD is on track for a fourth consecutive weekly gain heading into today’s BoE meeting, after its false break below 1.3200 marked a sharp reversal from the range lows. And if the current rally extends, it could be headed for the range highs around 1.3600 or the May high (1.3658). That said, the weekly RSI (2) is currently overbought, so perhaps a bump in the road could be due.
Still, the daily chart shows bullish momentum remains strong, with the rally confirmed by a rising RSI (14). GBP/USD has cleared both of its 200-day averages and is now within roughly one to two days’ trading ranges of the September VPOC (1.3544).
Bulls could be seeking dips towards the 200-day SMA (1.3421), which sits near the lower 1-day implied volatility band. The upper 1-day IV band sits at 1.3518, making it a potential initial upside target ahead of the September VPOC.
Source: ICE, TradingView
GBP/AUD Faces Resistance Ahead of BoE Decision
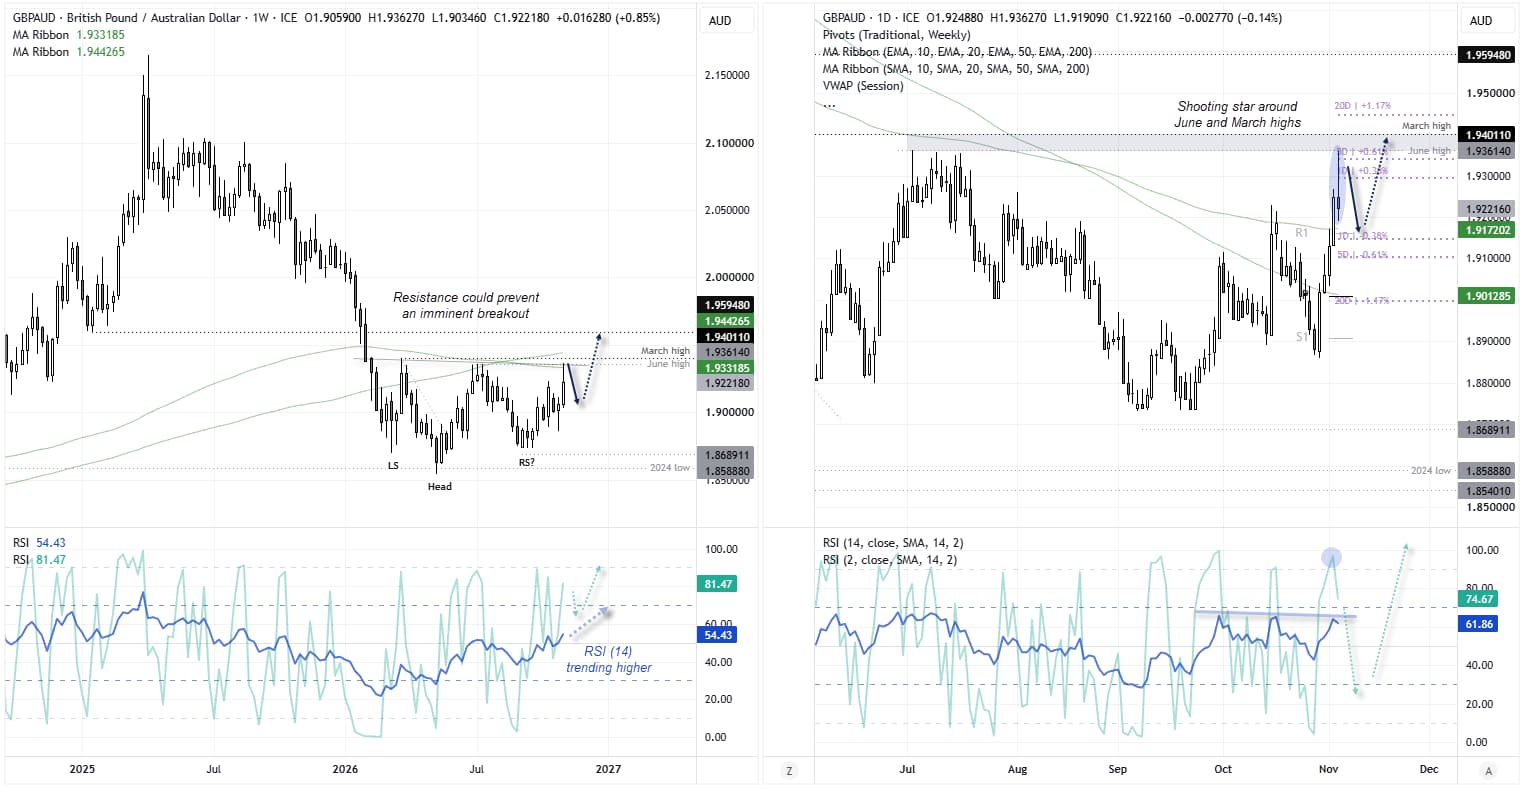
The British pound-Aussie cross reached my upside target around the June high on Wednesday, propelled by pre-emptive hawkish bets ahead of the BoE meeting and an unwinding of hawkish RBA bets. This keeps the potential long-term inverted head and shoulders reversal alive on the weekly chart, though resistance looms with the 200-week averages and March high (1.940) nearby.
The shooting star candle on the daily chart around said resistance levels presents the possibility of a near-term pullback, making GBP/AUD my preferred pair to watch for a short setup should the BoE disappoint bulls with a not-so-hawkish hike.
Source: ICE, TradingView
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

USD/CAD Forecast: Canadian Dollar Gains Ground After U.S. Midterm Elections
The trading week continues to unfold and the recovery in the Canadian dollar has once again become a relevant theme in the short term. This can be clearly seen in the recent performance of USD/CAD, which is down nearly 0.4% during the session, reflecting a consistent recovery in the CAD against the U.S. dollar.


Euro Technical Outlook: EUR/USD Support Reversal Sets Up Breakout Test Ahead of NFP 11 4 2026
Euro bulls are attempting to build on the rebound from recent lows, but pivotal resistance still stands in the way of a larger EUR/USD recovery.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.