



Gold and S&P 500 analysis: What now after Warsh’s hawkish speech?
The dollar surged across the board after the Fed Chair Kevin Warsh surprised with a hawkish-leaning speech at the Jackson Hole summit. All the bearish dollar bets that had been accumulated since last Friday on the back of data weakness and bond market troubles had to be squared and that triggered a short squeeze rally for the dollar. Gold and silver dropped, as a result, as too did bitcoin, while US indices were giving back earlier gains.
Share this:
The dollar surged across the board after the Fed Chair Kevin Warsh surprised with a hawkish-leaning speech at the Jackson Hole summit. All the bearish dollar bets that had been accumulated since last Friday on the back of data weakness and bond market troubles had to be squared and that triggered a short squeeze rally for the dollar. Gold and silver dropped, as a result, as too did bitcoin, while US indices were giving back earlier gains. Bond yields pushed higher to near recent highs. At the time of writing, it looked like the week would be ending on a downbeat note for risk assets, but will dip-buyers show up as we head deeper into the US session, for equities, gold and major FX? The counterargument against the hawkish re-pricing here is that with oil prices stabilising amid signs of increased traffic flows through the Strait of Hormuz, inflationary pressures could come down and the Fed may not hike after all, especially if the upcoming jobs and CPI reports both come in weaker in the next two weeks. But that’s something perhaps to considered for the week ahead.
Warsh puts September hike back in play, but will the Fed hike?
Warsh’s speech was deemed to be quite a bit on the hawkish side and the dollar reacted by bouncing back across the board, while gold and silver fell from their earlier highs in initial reaction. Warsh said what you would have expected regarding forward guidance: i.e., he doesn’t believe in in and so for that reason he refused to pre-commit to a September hike. That didn’t stop the markets from speculating that a hike may, after all, be back on the table. Regarding inflation, Warsh said it remains the clear priority, and he discussed it in some detail, although he also added that he’s confident that underlying inflation is moving towards the Fed’s objective. Overall, he cam across as more hawkish than was expected. Markets sharply repriced the September Fed decision during Kevin Warsh’s Jackson Hole speech. The probability of the Fed hiking rates by 25bp jumped from 30% to around 50%.
US jobs and CPI to come until September Fed meeting
Heading into the new month, we will have one more jobs and CPI inflation report to look forward to, before the Fed meets on September 16. There will also be some secondary data releases in between. It will be a close call.
Among next week’s US data releases, the NFP report will be published on Friday. Under the new Chairman, the Fed has become more data dependent. This has allowed data traders to enjoy higher volatility around the time of data release, especially when you consider the fact that the Fed has also stopped giving forward guidance. With the US jobs report missing expectations in the last couple of releases, and by big margins, any further signs of weakness could seriously dent expectations of a September rate hike from the Fed.
RBNZ and BOC rate decisions will also be watched
Both the Reserve Bank of New Zealand and later the Bank of Canda will meet on Wednesday to deliver their respective rate decisions.
The RBNZ raised interest rates by 25 basis points to 2.50% in July, in its first rate change in four meeting. While labour and housing market activities have been subdued, a vast majority of economist expect a further 25 basis point hike on Wednesday. This is largely due to inflation remaining sticky. Any hints of another hike later in the year could boost the NZD.
Meanwhile, no changes are expected at this meeting from the Bank of Canda, as strength in the economy (GDP grew by an annualised rate of 3.3% in Q2) is weighed against stable core inflation and, more to the point, the ongoing trade tensions with the US. That’s not to mention the energy market uncertainties. Against this backdrop, a wait-and-hold stance makes sense.
Gold key levels to watch
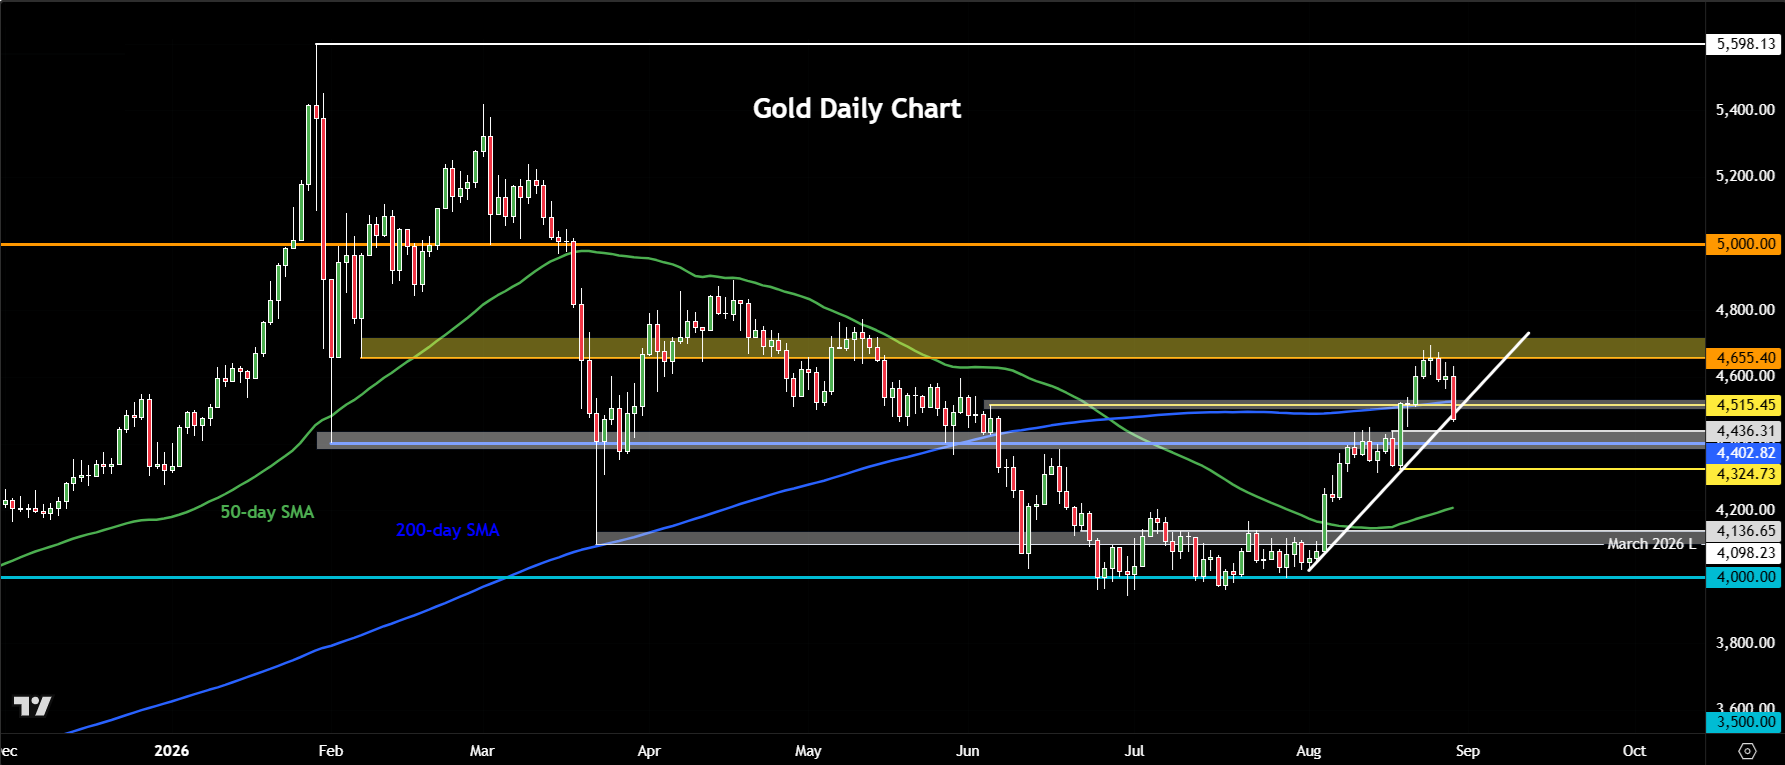
Gold has now resumed lower from the key resistance area we highlighted earlier this week around the 4655 area. At the time of writing, the metal was below the 200-day but was testing the short-term bullish trend line. Next support is seen around the 4436 and then 4400 area. It would be a bearish technical development if they buyers don’t show up are those levels.
S&P 500 turns red
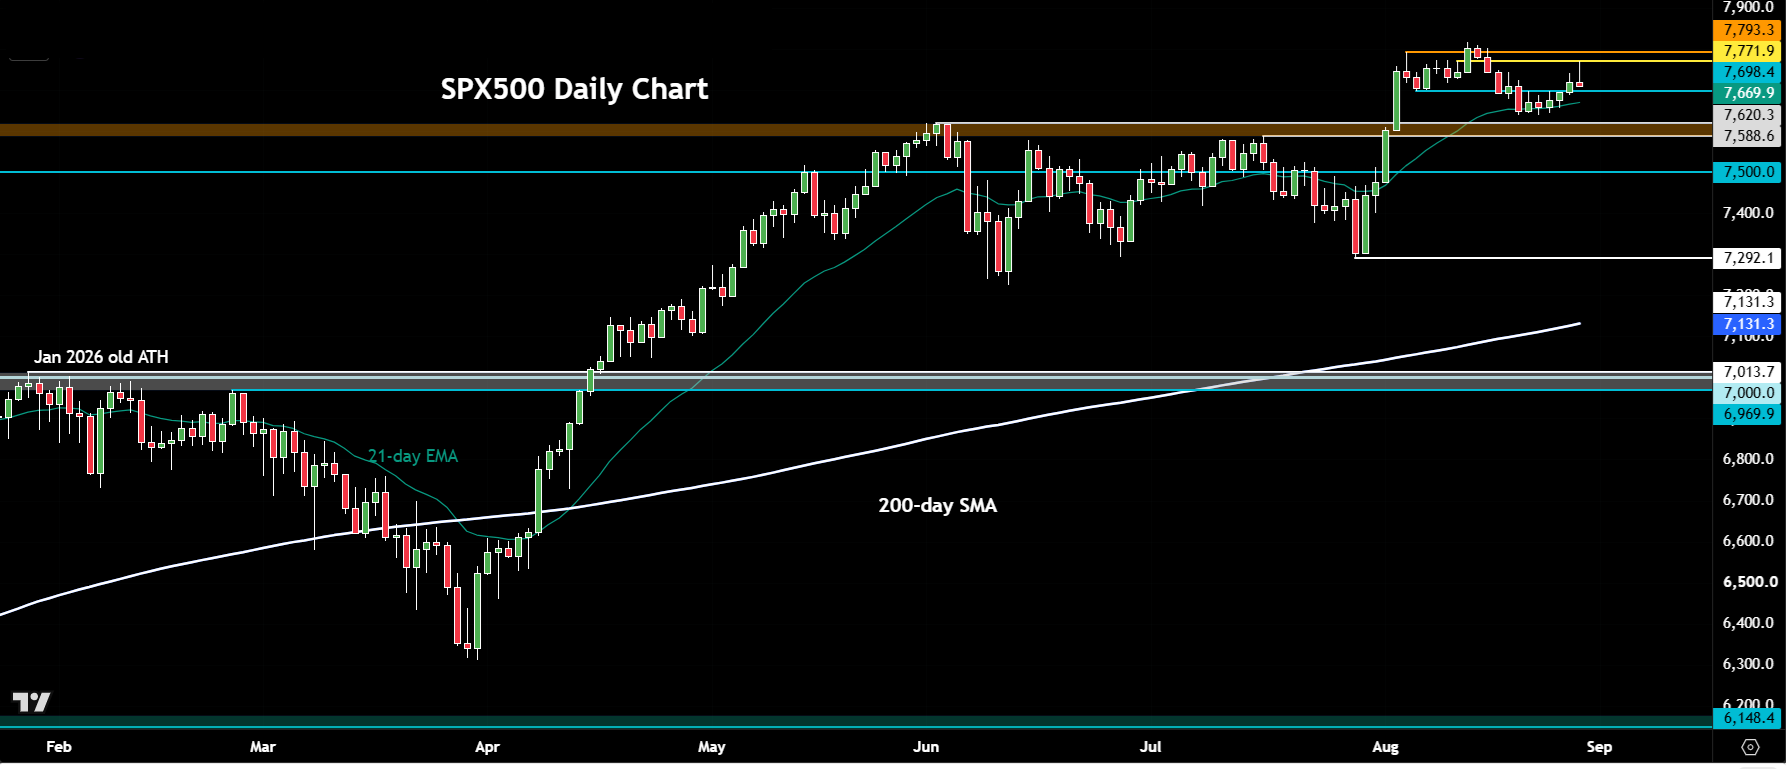
The chart of the S&P 500 has turned negative on the day, after it found resistance at 7770/2 area. The index still looks healthy when you zoom out, but if more and more support levels break then things will start to look different quite quickly. Short-term support is at 7698 area, followed 7620 zone.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.

Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.