






Japanese Yen Weaker Amid Tariffs, Reduced Hawkish-BOJ Bets, CPI Reports in Focus
The Japanese yen was the weakest currency on Thursday, with traders lowering their expectations of a BOJ hike in light of Trump's tariffs. GBP/JPY was the outperformer as traders are also lowering their expectations of BOE cuts. But whether USD/JPY can break out above its 200-day EMA and the 152 handle likely requires a soft set of inflation figures from Tokyo and a stronger-than-expected US PCE report today.
Share this:

View related analysis:
- If Consumers Don’t Consume, a Recession Could be Presumed
- Nasdaq 100, S&P 500 Feel the Force of Trump’s Tariffs, ASX to Open Lower
- Japanese yen broadly lower, USD, risk bounces amid Trump-tariff relief
- EUR/USD bears short-covered at fastest pace in 5 years - COT Report
- AUD/USD Weekly Outlook: AU inflation, US Core PCE on Tap
The Japanese yen was the weakest currency on Thursday, which saw GBP/JPY breakout and tap 196 for the first time since January, AUD/JPY rise to a 7-day high and EUR/JPY a 6-day high. Yet this was not a risk-on move. Instead, traders are lowering their expectations of a hawkish Bank of Japan (BOJ) in light of Trump’s tariffs, on bets it will weaken their economy.
- CHF/JPY closed above its 200-day EMA and a double top pattern to suggest bullish trend continuation.
- EUR/JPY rallied from its 200-day EMA to suggest it wants another crack at breaking above 164
- GBP/JPY was the outperformer as traders are also lowering their expectations of BOE cuts
- Whether USD/JPY can break out above its 200-day EMA and the 152 handle likely requires a soft set of inflation figures from Tokyo and a stronger-than-expected US PCE report today
Economic events in focus (AEDT)
- 10:30 – Tokyo CPI
- 10:50 – BOJ summary of opinions
- 18:00 – UK Q4 GDP, Retail Sales, Trade Balance, Business Investment
- 21:00 – European Sentiment Indicator
- 23:30 – US Core PCE
Watch personal spending, income in today’s US PCE report
While today’s PCE inflation report for the US is today’s big calendar event, it remains debatable as to how important the headline figures are, given all attention is firmly on Trump’s tariffs. Unless, of course, we get a large deviation from forecasts and prior readings, in either direction. Yet PCE data is by design less volatile than other inflation readings, and the estimates are also not overly exciting.
Core PCE is expected to rise to 2.7% y/y from 2.6% and remain stable at 0.3%. PCE is expected to remain unchanged at 2.7% y/y and 0.3% m/m.
Personal income and spending could be metrics to watch closely, given the dire US consumer reports. In particular, I noted concerns over future finances, which could put a cap on future spending and therefore growth. Today’s PCE report is an ideal place to look for such cutbacks.
Tokyo’s inflation report up next
There was a close, positive correlation between Tokyo and Japan’s core CPI readings up until Q3 2024, but since then we have seen Japan’s core CPI rise and Tokyo’s decelerate. This is unfortunate because Tokyo’s data is released three weeks prior and was thus a useful leading indicator for the nationwide counterpart.
All is not lost, however, because there is still a strong correlation between Tokyo’s broad CPI, Japan’s nationwide CPI and (as an added bonus) Japan’s services CPI. Given traders are trimming their bets on a hawkish BOJ due to Trump’s tariffs, a weak set of inflation figures today could further weaken the yen and allow EUR/JPY, GBP/JPY, and the like to continue higher. USD/JPY could finally break out if bulls are treated to soft data from Tokyo and a stronger-than-expected PCE report later today.
ASX 200 at a glance
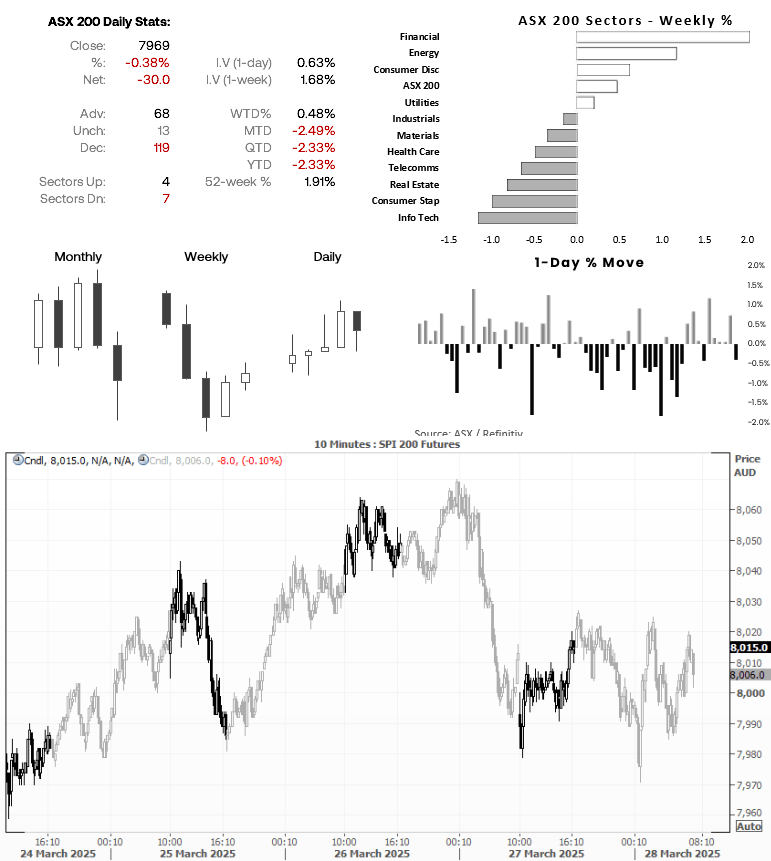
- The ASX 200 snapped a 5-day winning streak on Thursday and closed -40 points on the day, after failing to close above 8,000 on Wednesday
- 7 of the ASX 200 sectors declined (led by info tech and consumer staples), 4 advanced (led by financial and energy)
- Wall Street was a touch lower and ASX 200 futures (SPI 200) were down -0.1% overnight, pointing to a flat open for the ASX cash market today.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD reversal risk builds as central bank showdown looms
USD/CAD has delivered a bullish reversal signal from established support, just as traders prepare for Fed and BoC decisions. Aggressive Canadian rate hike expectations and conflicting momentum signals make the coming session important.
EUR/USD weekly outlook: FOMC and ECB to set the tone
The current backdrop is modestly bearish. On Friday, the EUR/USD closed modestly lower, down for the third consecutive day. The pair also posted a weekly decline after staging a modest recovery attempt in the previous week. Out of the past 8 weeks, the EUR/USD has fallen on 6 occasions. There is not much supporting factors for the single currency right now. So, the upside remains capped.

USD/JPY Weekly Outlook: AI earnings could overshadow the Fed and BoJ
AI sentiment has become a major driver of US Treasury yields and USD/JPY. With Microsoft, Alphabet and Amazon reporting this week, central bank decisions may have competition for traders' attention.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.