

Market Brief: Markets Fall on Fed Chair Shock; DAX Stabilizes, Metals Slide
Markets turned risk‑off after President Trump nominated Kevin Warsh as the next Fed Chair—sending the dollar higher, yields up and precious metals sharply lower. US equities closed weaker, while Apple held flat and software stocks fell. The DAX is stabilizing near support with early signs of a momentum rebound. Oil softened, crypto slid below key levels and geopolitical tensions in the Middle East and Europe kept volatility elevated.
Share this:
Market Brief – Overview of Key Developments
US EQUITIES & MONETARY POLICY
Fed Chair Nomination Weighs on Sentiment
US equities were choppy as markets reassessed what President Trump’s nomination of Kevin Warsh as the next Fed Chair means for policy. The uncertainty may persist until Warsh provides updated commentary, given his long absence from the public stage. Historically, he has been considered hawkish on the balance sheet and skeptical of QE, yet in 2025 he advocated for lower interest rates.
Stocks ultimately finished in the red, with Materials leading the losses due to a sharp correction in precious metals, followed by Technology.
Apple (AAPL) ended the day roughly flat despite posting a top‑ and bottom‑line beat, as some desks flagged concerns about weak services revenue and future cost pressures linked to memory shortages. Defensive sectors such as Consumer Staples and Healthcare showed resilience.
Germany – DAX Technical Analysis
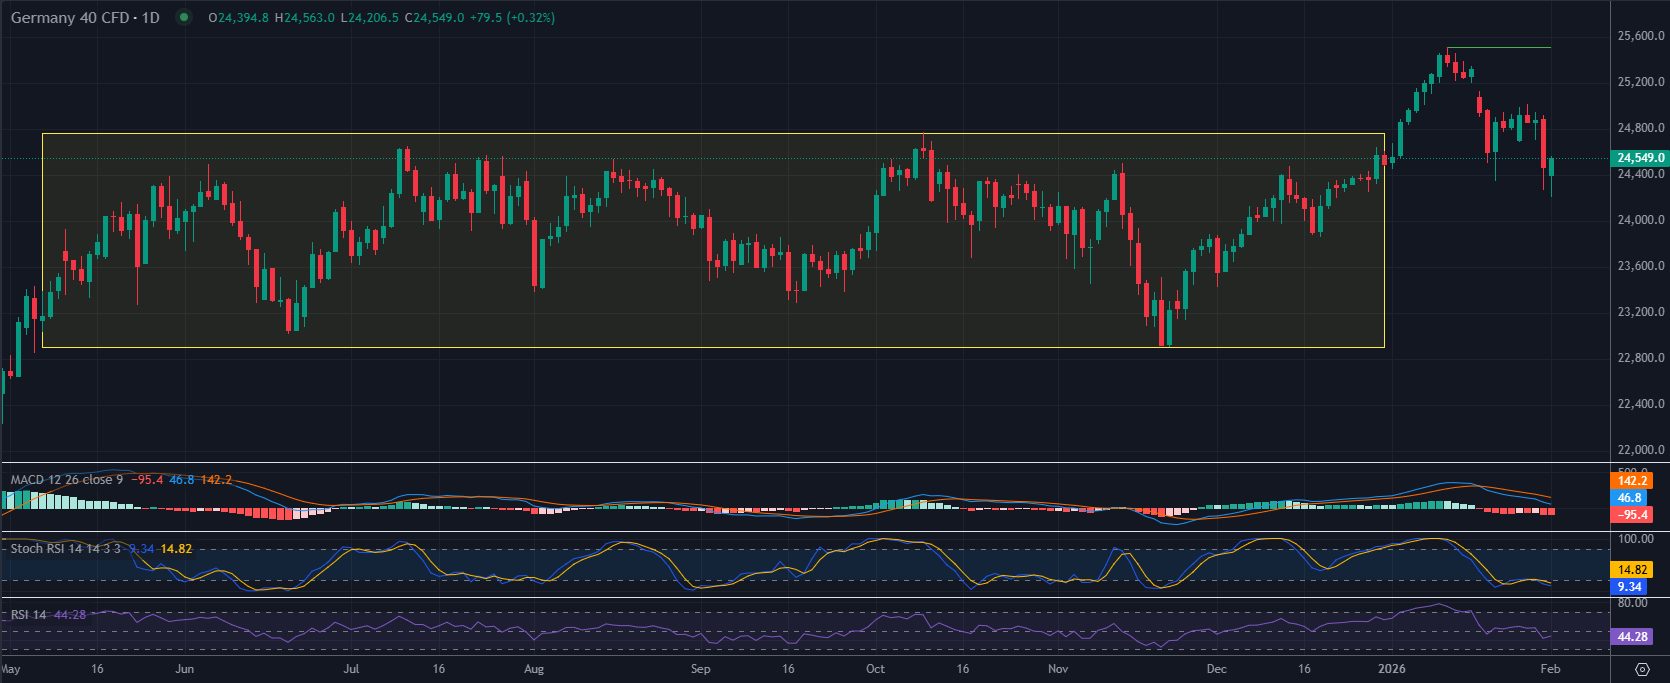
Germany 40 is stabilising around 24,549 after bouncing off the lower edge of the previous long‑term range near 23,900. Price is now testing the lower boundary of the old consolidation zone, and 24,900–25,000 remains the key resistance that must be reclaimed for bullish momentum to return.
Momentum indicators are weak but improving. MACD stays negative, RSI at 44 is neutral‑bearish, and Stochastic RSI is turning up from oversold, hinting at a possible short‑term rebound. A move back above 24,900 would open the way toward 25,200–25,600, while failure keeps pressure toward 24,200 and 23,900.
TARIFFS & TRADE
United States–Canada–China
President Trump warned of a “very substantial response” if Canada finalizes a trade deal with China. He added that the US “does not want China taking over Canada,” which he claims would be the consequence of such an agreement.
United States–South Korea
South Korean Industry Minister Kim said Seoul would accelerate implementation of investment legislation after returning from talks in Washington, which he said clarified misunderstandings surrounding US tariffs.
China–EU
The EU industry association reported that China has proposed final anti‑subsidy duties on EU dairy products of up to 11.7%, significantly below the provisional rates of up to 42.7%.
NOTABLE HEADLINES
Warsh Nomination Politics
President Trump said Fed Chair nominee Warsh may even receive Democratic votes, and expressed hope that Warsh would lower interest rates. Trump added that Warsh did not commit to rate cuts but “will probably” discuss cuts with him; he also asserted that Warsh would cut rates without White House pressure.
NVIDIA–OpenAI Investment Uncertainty
NVIDIA’s rumored USD 100bn investment in OpenAI has reportedly stalled due to internal concerns, according to the WSJ. However, CEO Jensen Huang said:
- NVIDIA will definitely invest in OpenAI
- It will likely be their “biggest investment ever”
- But rejected the notion of a USD 100bn figure ("no, nothing like that")
COMMODITIES & ENERGY
Oil
Crude futures slumped as risk‑off sentiment intensified. Weak demand expectations were compounded by:
- The partial US government shutdown
- Surprise contractions in China’s official PMIs
- OPEC+ members maintaining their pause on output hikes for March
Russia eased some gasoline export restrictions, and reports surfaced that the US and Iran could meet in Turkey this week for talks.
Gold & Silver – Historic Selloff
Spot gold extended losses following Friday’s largest intraday drop in four decades, triggered by Warsh’s nomination.
CME Group hikes margins, which is set to take effect as of Mondays market close:
- Gold: from 6% → 8%
- Silver: 11% → 15%
Platinum and Palladium futures will also see increases in margin requirements.
Copper
Copper futures declined amid broad risk aversion and weak Chinese factory data. Selling accelerated once SHFE and LME trading resumed following a technical issue.
CRYPTO
Bitcoin Continues to Slide
Bitcoin extended last weekend’s losses, breaking below USD 80,000 and hitting a trough below USD 75,000 before stabilizing.
Risk‑off sentiment linked to Warsh’s nomination exacerbated pressure across crypto markets.
MIDDLE EAST
Escalating Rhetoric
- Iran’s Supreme Leader Khamenei warned that a US attack would “not remain confined to Iran” and could expand across the region.
- Iran threatened Israel again, saying any “enemy mistake” would endanger regional security.
US officials indicated a possible US–Iran meeting in Turkey this week (Axios).
The US State Department also approved nearly USD 16bn in arms sales to Israel and Saudi Arabia.
RUSSIA–UKRAINE
- President Zelensky said Ukraine is ready for substantive discussions, with the next trilateral US–Russia–Ukraine talks scheduled for Feb 4–5 in Abu Dhabi.
- The US envoy Witkoff described weekend talks with Russia’s Dmitriev as “constructive.”
- Russia claimed control over two villages in Kharkiv and Donetsk (TASS).
- Medvedev said victory is near and praised Trump as an “effective leader seeking peace.”
EU / UK
UK & EU Defence Integration
- UK PM Starmer said Britain should consider re‑entering talks on a defence pact with the EU.
- UK and Japan agreed to deepen security cooperation.
Ratings
- S&P affirmed Italy at BBB+, Outlook raised to Positive
- European Stability Mechanism reaffirmed at AAA, Outlook Stable
MARKET REACTIONS TO CRYPTO & TECH
Strategy Inc plunges with Bitcoin
Strategy Inc (MSTR) fell ~10% pre‑market as Bitcoin dropped again.
The company holds 712,647 BTC at an average price of USD 76,037, making its stock a leveraged proxy for Bitcoin.
Software Sector Selloff
A broad decline followed Microsoft’s weak cloud growth:
- Microsoft: –10%
- ServiceNow: –10% (warned of slower subscriber growth)
- Salesforce: –6%, hitting a 52‑week low
DEUTSCHE BANK PROBE
German authorities raided Deutsche Bank offices as part of a money‑laundering investigation potentially involving Russian oligarch Roman Abramovich.
Deutsche Bank is cooperating with investigators.
MACRO THEMES
Kevin Warsh to Lead the Fed – Markets React Immediately
Trump nominated Kevin Warsh for Fed Chair.
Impacts observed:
- US yield curve steepened
- USD strengthened
- Precious metals fell
Warsh advocates reducing the Fed balance sheet to curb inflation, which he argues creates room for future rate cuts.
US DOLLAR VOLATILITY
The dollar has swung sharply based on conflicting White House signals:
- Trump said the weaker USD was “great” and beneficial for US companies.
- Treasury Secretary Bessent later reiterated the strong‑dollar policy.
- Warsh’s nomination boosted the dollar further.
JAPAN
Inflation Eases, Rate Hike More Likely
- Tokyo CPI: 1.5%, first sub‑2% reading since 2024
- Core inflation (ex-food/energy): 2.4%
Labour market remains solid.
Markets price a 97% probability of a BoJ rate hike by June.
EARNINGS THIS WEEK
United States – 129 S&P 500 companies
Key reporters include:
Amazon, Alphabet, AMD, Uber, Palantir, AbbVie, Pfizer, Merck, Eli Lilly, PayPal, PepsiCo, Disney
Europe – 84 STOXX 600 companies
Includes:
SocGen, BNP Paribas, Santander, Siemens Healthineers, Infineon, Novo Nordisk, Shell
Japan
Nintendo, Mitsubishi, Mizuho Financial Group
KEY UPCOMING EARNINGS DATES
- Feb 2: Disney (pre-market), Palantir (after-market)
- Feb 3: PayPal, Pepsi, Pfizer, AMD, Supermicro
- Feb 4: Uber, Eli Lilly, Alphabet, Qualcomm
- Feb 5: Amazon, Strategy Inc, Reddit
-Philip Papageorgiou – Market Analyst
--X ex Twitter: PhilipForexCom
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Outlook: A Rates Trade Disguised as a Stock Market?
Australian bond futures have exhibited a far stronger relationship with the ASX 200 than Wall Street over recent months. Now both markets are displaying remarkably similar price structures.
AUD/USD Bulls Fight Back After Australian Jobs Shock
AUD/USD has been hit by another ugly Australian employment report, sending RBA rate hike expectations sharply lower. Yet the relationships driving the currency have shifted since quarter-end, and improving risk appetite could provide the fuel for a recovery.
Bitcoin Forecast: BTC/USD Bounces off $80K, 9-Month Highs In Play?
Despite apparent fundamental headwinds, Bitcoin’s price has held up relatively well, bouncing sharply off $80K support - where could it head next?
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.