

Nasdaq 100 Forecast: NDX falls as oil jumps 5%, Treasury yields rise
U.S. stocks are set to open lower, with the Dow Jones leading the move south as U.S. oil prices jump 5% and Treasury yields rise, stoking inflation concerns.
Share this:

US futures
Dow futures -0.66%, S&P 500 futures -0.34% & Nasdaq futures -0.59%
European futures
FTSE -0.06%, DAX -0.76%
- US stocks fall further from record highs
- Oil jumps 5% and Treasury yields are rising
- USD sits at an 18-month high
- Oil rises with Brent back above $105 as tanker attacks in the Strait rise
U.S. Stocks Set to Open Lower as Oil and Yields Rise
U.S. stocks are set to open lower, with the Dow Jones leading the move south as U.S. oil prices jump 5% and Treasury yields rise, stoking inflation concerns.
Oil prices have surged as attacks on shipping in the Gulf and the Strait of Hormuz increase, adding to concerns over global supply.
Meanwhile, the bond market sell-off shows no signs of slowing, with the 10-year Treasury yield at 5.34%, its highest level since 2002.
The latest rise in yields comes not only as oil prices climb but also after hawkish Fed minutes from the September meeting. The minutes showed that the vote to hike rates by 25 basis points, marking the first rate hike since 2023, was unanimous. The majority of policymakers also saw another rate hike before the end of the year.
Elevated yields are hurting demand for risk assets, pulling the S&P 500 and Nasdaq back from record highs reached earlier in the week.
Attention will also turn to quarterly earnings season, which ramps up next week with the big banks, including JPMorgan.
Optimism surrounding a strong earnings season is helping to keep stocks buoyed despite a challenging macroeconomic backdrop. Technology and energy stocks are expected to see the strongest quarterly earnings growth, with overall S&P 500 earnings expected to rise 30.6%.
Federal Reserve Governor Christopher Waller hinted at a possible pause at the central bank's upcoming meeting, saying flexibility around the pace of increases was needed, although he still sees further hikes as necessary to bring inflation back towards the Fed's 2% target.
The market is widely expected to leave rates on hold at the October meeting, but a December rate hike remains very much on the table.
Corporate Movers
Wolfspeed jumped 15% after the chipmaker secured a conditional $1.5 billion loan, marking a 30-year financing commitment from the Defense Department.
Broadcom is around 2% lower pre-market on reports the company is working to arrange more than $50 billion in financing tied to the custom AI chips it is developing with OpenAI.
Taiwan Semiconductor Manufacturing, the world's largest contract chipmaker, reported September revenue growth of 54.6% year on year, pushing third-quarter revenue to $16.03 billion, above expectations.
Lululemon is down around 1% after announcing former Nike executive and Athleta CEO Maggie Gower will take over as chief product officer.
Levi Strauss is falling 3% after the company posted Q3 revenue of $1.61 billion, slightly missing expectations as direct-to-consumer sales weakened in both the U.S. and Europe.
Nasdaq 100 Forecast – Technical Analysis
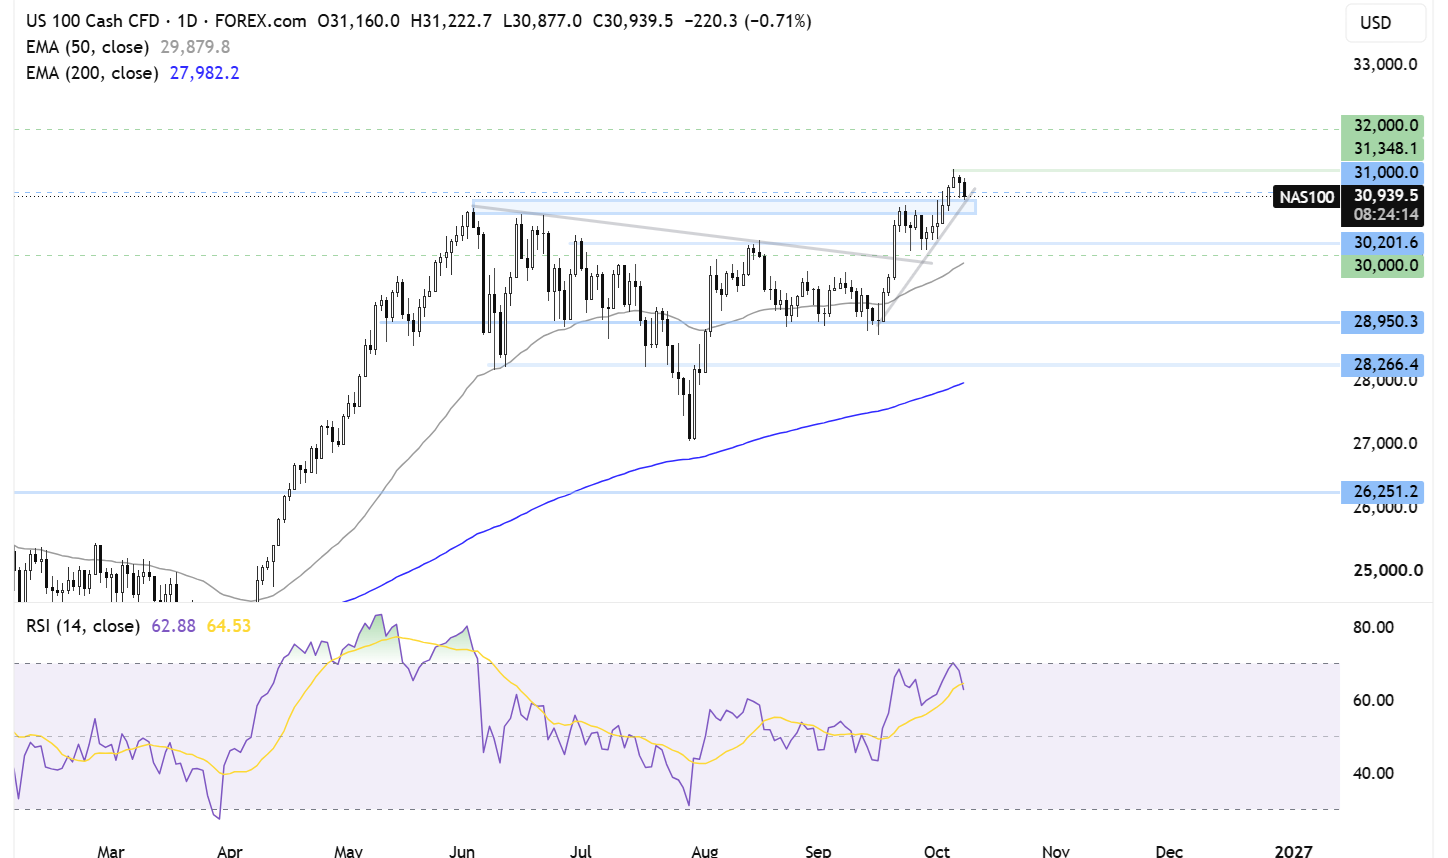
The Nasdaq 100 has eased back from its record high of 31,360, testing support at the rising trendline and the June high around 31,000.
A break below here would keep attention on 30,200. Only below this level would the bullish outlook be materially weakened. It would take a break below 28,900 to create a lower low and turn attention towards 28,300, the June low.
Should support hold, buyers will need to rise above 31,360 to create a higher high and bring 32,000 into focus.
FX Markets – Dollar Holds Near 18-Month High
The U.S. dollar is rising to a fresh 18-month high, tracking Treasury yields higher as inflation risks remain tilted to the upside, according to the Fed's latest minutes. A December rate hike remains priced in, with further tightening expectations supporting the dollar.
EUR/USD is falling towards an 18-month low amid USD strength and ongoing concerns surrounding debt levels across the region. Eurozone bond yields have risen, with those of more indebted countries such as France increasing more sharply. The French 10-year yield has surged 14.9 basis points and is on track for its biggest daily jump in two weeks.
Meanwhile, ECB minutes showed policymakers viewed inflation risks as tilted to the upside due to elevated oil prices. The central bank also noted that the 2.5% deposit rate remained within estimates of the neutral range.
GBP/USD is testing 1.32 amid a stronger U.S. dollar, despite expectations that the Bank of England will hike interest rates at its November meeting. BoE Governor Andrew Bailey is due to speak shortly, while policymaker Clare Lombardelli is also scheduled to speak. The market will be watching for clues over when the central bank could next hike rates, with two 25-basis-point hikes priced in by the February meeting.
Oil Prices Rise as Supply Concerns Return
Oil prices have jumped 5% on Thursday amid rising concerns over Middle Eastern supply, as attacks on ships in the Gulf and Strait of Hormuz increase and the U.S. cuts output ahead of an approaching hurricane.
Brent has risen above $105 a barrel, while WTI is back above $92.
Attacks on tankers passing through the Strait of Hormuz have reached their highest level since the war began. Meanwhile, the U.S. is also considering renewed military action against Iran ahead of the midterm elections.
These developments suggest the conflict in the Middle East is escalating rather than de-escalating, raising concerns over supply from the region.
Separately, the hurricane is moving towards offshore production areas in the U.S., the world's biggest oil producer, causing some companies to shut platforms. U.S. Gulf of Mexico oil and gas producers had shut in around 25% of current oil production and 16% of natural gas production as of Wednesday because of the storm.
U.S. inventory data also supported crude prices, with stockpiles falling by more than expected.
The key market risk is that oil above $100 keeps inflation expectations elevated just as Treasury yields are already at multi-decade highs, leaving equities caught between strong earnings expectations and a much less supportive macro backdrop.
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Short-term Outlook: USD Four-Week Rally Stalls Below Key Resistance 10 8 2026
DXY is holding in a tight range beneath major resistance as traders await the next catalyst from inflation expectations and Fed repricing.
Dow Jones forecast: Stocks extend drop amid surging oil and elevated yields
The global equity markets remain under pressure and with oil surging higher again this week, we have even more reason to remain cautious. Already, the S&P and Nasdaq were running support from only a handful of hyperscalers and AI stocks. But even these indices have started to take notice of the deteriorating market breadth and global indices. Still, for me, the ongoing weakness is becoming more evident in the Dow and the small-cap Russell 2000 indices, and as such I will continuing watching these markets closely to provide a more accurate signal about the health of the stock markets.

Nasdaq 100 Forecast: NDX falls as oil jumps 5%, Treasury yields rise
U.S. stocks are set to open lower, with the Dow Jones leading the move south as U.S. oil prices jump 5% and Treasury yields rise, stoking inflation concerns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.