


Nasdaq 100 forecast: Oil and yields apply pressure ahead of CPI
US index futures and European markets were struggling to stay afloat after a weaker handover from Asia overnight, ahead of an eventful second half of the week. Rising oil prices and elevated bond yields were once again weighing on investor sentiment, keeping mild pressure on all sorts of risk assets.
Share this:
US index futures and European markets were struggling to stay afloat after a weaker handover from Asia overnight, ahead of an eventful second half of the week. Rising oil prices and elevated bond yields were once again weighing on investor sentiment, keeping mild pressure on all sorts of risk assets. The US dollar retreated further despite the oil gains and stronger payrolls data on Friday, suggesting the US dollar debasement trade is still alive. There are at least three key events to watch as we head into the second half of the week: the ECB’s interest-rate decision on Thursday, US CPI on Friday and the latest developments in crude oil. We maintain a cautious Nasdaq 100 forecast ahead of these events and as rising bond yields undermine the appetite for low yielding assets, including growth stocks.
Brent crude oil hits $100
Chief among investor worries is the continued rise in oil prices, with Brent futures now breaking the $100 barrier. The main driver for oil remains the conflict in the Middle East, with concerns that the recent re-escalation could disrupt regional oil supplies.
Financial markets are concerned about a sustained rise in energy prices as that would put renewed pressure on inflation, which creates all sorts of problems – especially for central banks and specifically those where there is political pressure to cut rates, namely the Fed.
Higher oil prices can push inflation higher while simultaneously squeezing consumers and businesses. If crude continues to rise, markets may therefore start pricing in more rate hikes for central banks like the ECB and the Fed.
For equities, that would be a clear headwind, especially growth stocks - many of which are constituents of the Nasdaq 100 index.
Yields grind higher ahead of inflation data
Meanwhile, it is worth keeping an eye on bond yields which continue to rise amid inflation concerns, while in the US it was the stronger than expected labour market that provided the latest gains.
Much of the focus will be on US 10 and 30 year bond yields this week, which have moved higher as markets reopened after the extended Labor Day weekend.
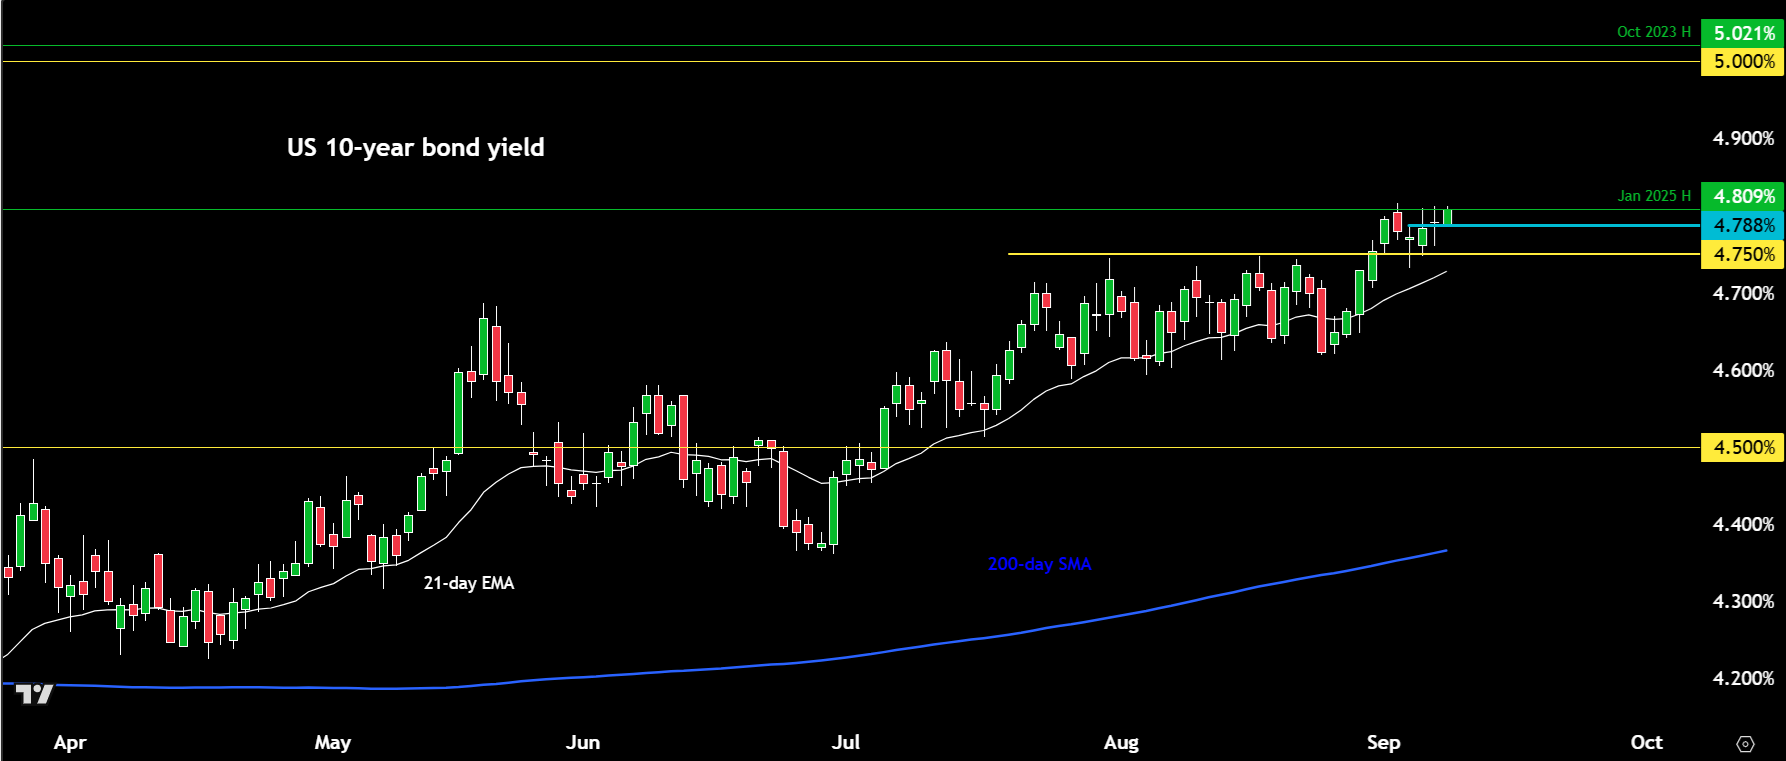
Investors are turning their attention to key inflation data that could help determine the Federal Reserve’s next move on interest rates.
The immediate focus is Thursday’s producer price index report for August. Economists expect the monthly PPI measure to have risen 0.4%, after remaining unchanged in July.
But it is CPI, due on Friday, that will potentially move the markets more meaningfully.
Headline CPI is expected to have risen by 0.4% month on in August, while the year over year rate is seen unchanged at 3.4%. Core CPI is expected to have edged a bit lower to 2.4% y/y vs 2.5% the month before.
If inflation data turns out to be in line, or worse, higher than expected, then this is likely to put renewed pressure on risk assets as it would cement expectations of a hike from the FOMC’s September 16 meeting.
Technical Nasdaq 100 forecast and key levels to watch
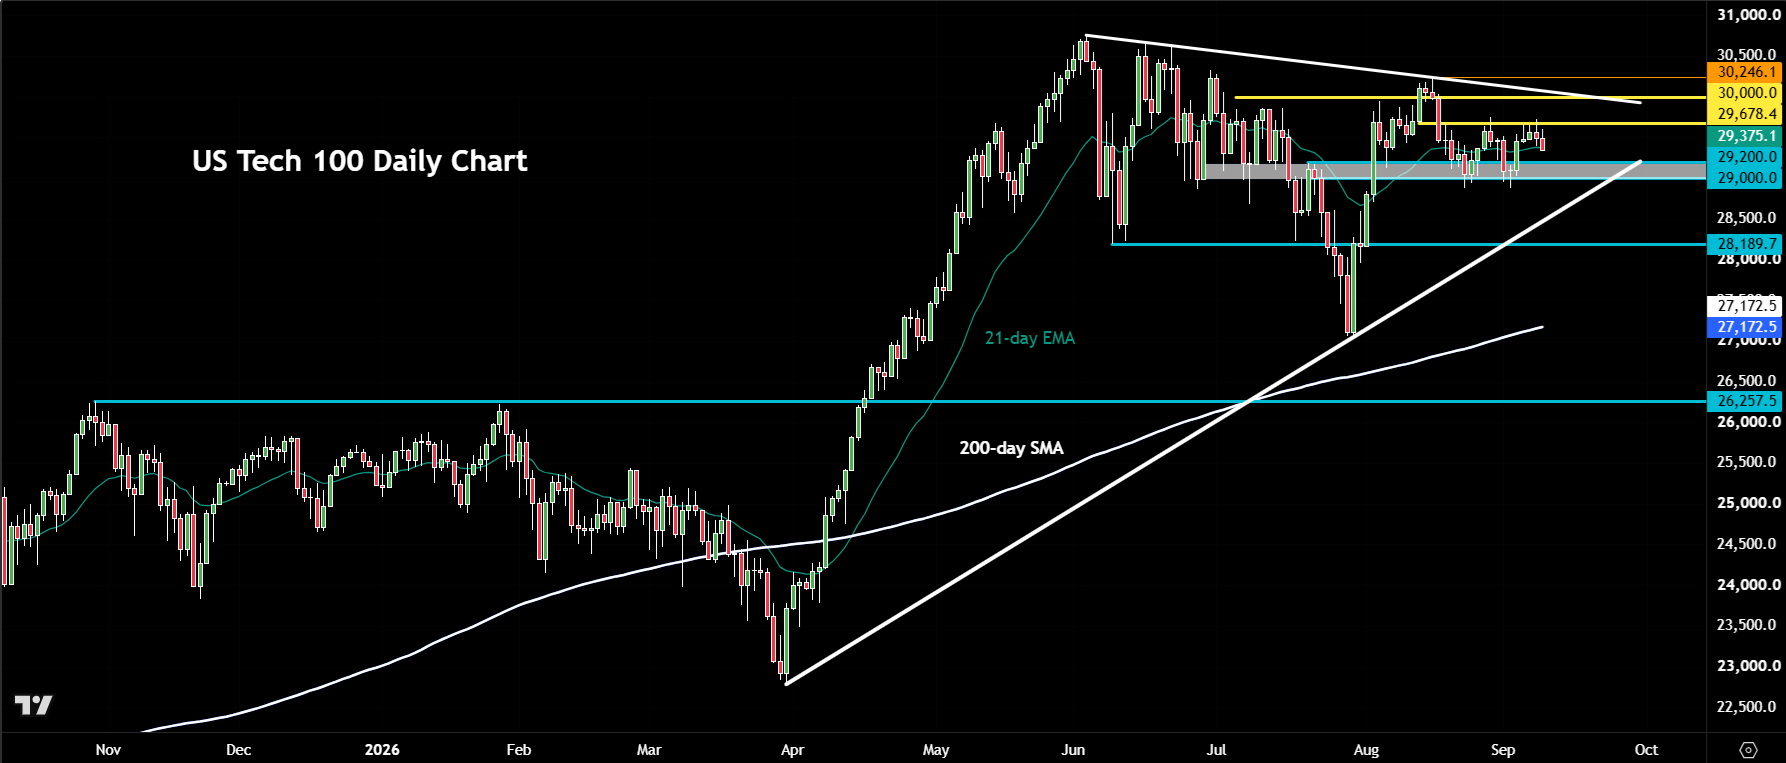
The ongoing consolidation phase could turn into a correction if the macro picture doesn’t improve soon. Key support is seen around 29,000 to 29,200 on our US Tech 100 chart, which is derived from the underlying Nasdaq 100 futures.
Below that, the trend line will come into focus and then sold support at 28.190ish.
Resistance is currently offered around the 29,680 area. Above that you have the 30K level, which coincides with the bearish trend line, making it a key hurdle. A break above that would certainly be a bullish development when you consider this lengthy consolidation here.
So, this week could prove decisive for risk assets. Ahead of it, investors are watching oil prices. If oil continues to push past and remain above $100 for Brent, stocks may continue to struggle.

Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

British Pound Short-term Outlook: GBP/USD Selloff Breaks June Uptrend 9 22 2026
Sterling has slipped below its 200-day moving average as downside momentum carries GBP/USD toward another major technical support zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.