

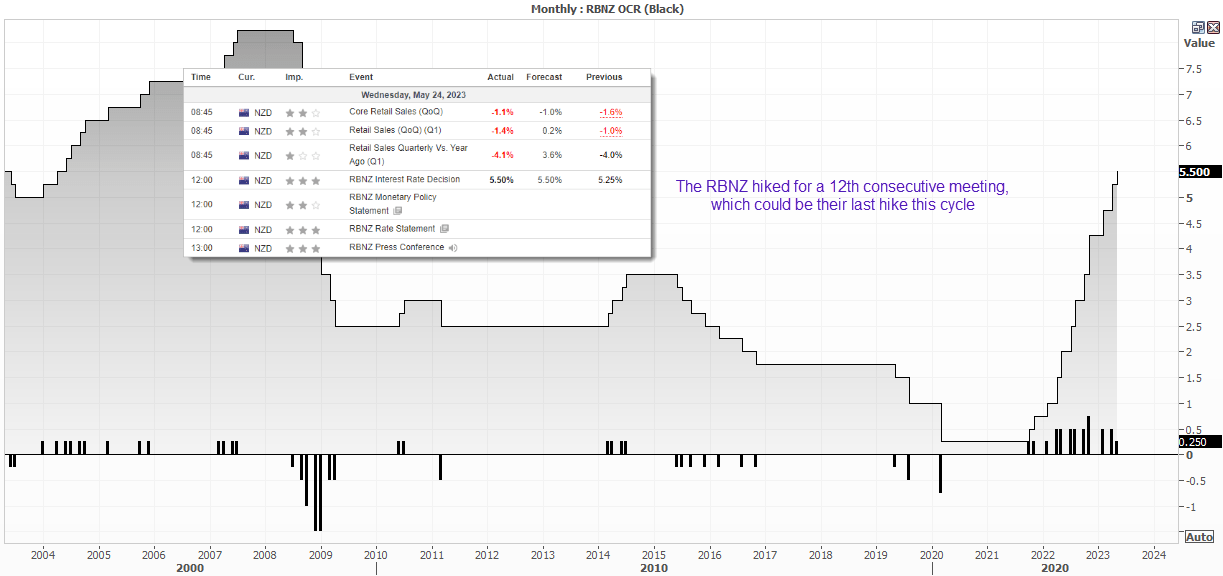


NZD/USD analysis: The RBNZ’s latest 25bp hike could be their last
NZD pairs were lower after the RBNZ hiked for a 12th consecutive meeting and signalled they may have reached a peak rate of 5.5%. At least for now.
Share this:

Key takeaways
- The RBNZ increased rates by 25bp to 5.5%, below some estimates of a 50bp hike
- Forecasts retained a terminal rate at 5.5%
- The statement was relatively dovish, compared to prior statements
- The government’s budget is not deemed to be as inflationary as feared
- Initial confusion over a pause stemmed from incorrect reporting by some data vendors (and slow RBNZ website)
- NZD pears broadly lower by ~1%
Depending on who is asked, the RBNZ hiked rates by 25bp as expected (or not by the 50bp as expected some others). A dovish statement with an unadjusted peak rate at 5.5% means the RBNZ have signalled the end of their tightening cycle, although warned that rates will need to remain ‘restrictive’ (high) for soe time.
NZD pairs were around -1% lower, AUD/NZD rose 0.9% and we’re not seeing any immediate appetite to support the Kiwi dollar at the time of writing, although neither are prices dropping further.
But the release was not plain sailing, as Reuters and presumably any other data vendor which copies them, initially printed a hold at 5.25% before correcting to 5.5%. The RBNZ website was slow also slow to update to the latest report (at least it was on my end). By quite how much of an impact on the Kiwi’s selloff sue to the incorrect figure is hard to decipher, but we can see that the New Zealand dollar was heavily sold off across the board and it has not really recovered since.
A relatively dovish RBNZ statement
In relative terms, the statement was the most dovish the RBNZ have released in quite some time and certainly this tightening cycle. And by that we mean it was not as hawkish as expected. The majority of the statement is tipping its hat to slower demand overall and, whilst migration and tourism is a support demand to a degree, it seems the RBNZ are not overly concerned with the government’s budget which was deemed by many as highly inflationary. Weaker than expected retail sales data released ahead of the announcement may have also helped with their outlook.
Summary of the RBNZ statement and MPS
- The level of interest rates are constraining spending and inflation pressure
- The OCR will need to remain at a restrictive level for the foreseeable future
- Global growth remains weak and inflation pressures are easing
- New Zealand’s inflation is expected to continue to decline from its peak and with it measures of inflation expectations
- Consumer spending growth has eased and residential construction activity has declined
- Businesses are reporting slower demand for their goods and services
- Businesses report that a lack of demand, rather than labour shortages, is now the main constraint on activity
- Net inward migration and tourism spending is supporting demand
- Broader government spending is anticipated to decline in inflation-adjusted terms and in proportion to GDP
NZD/USD daily chart
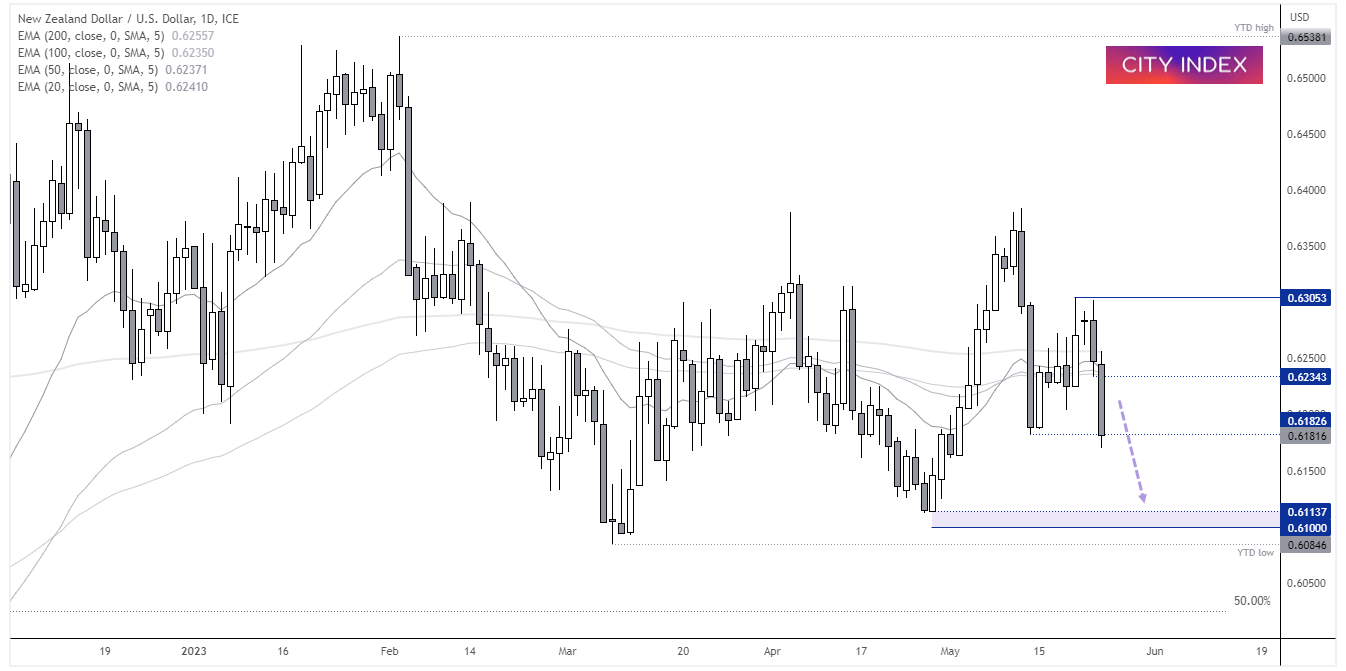
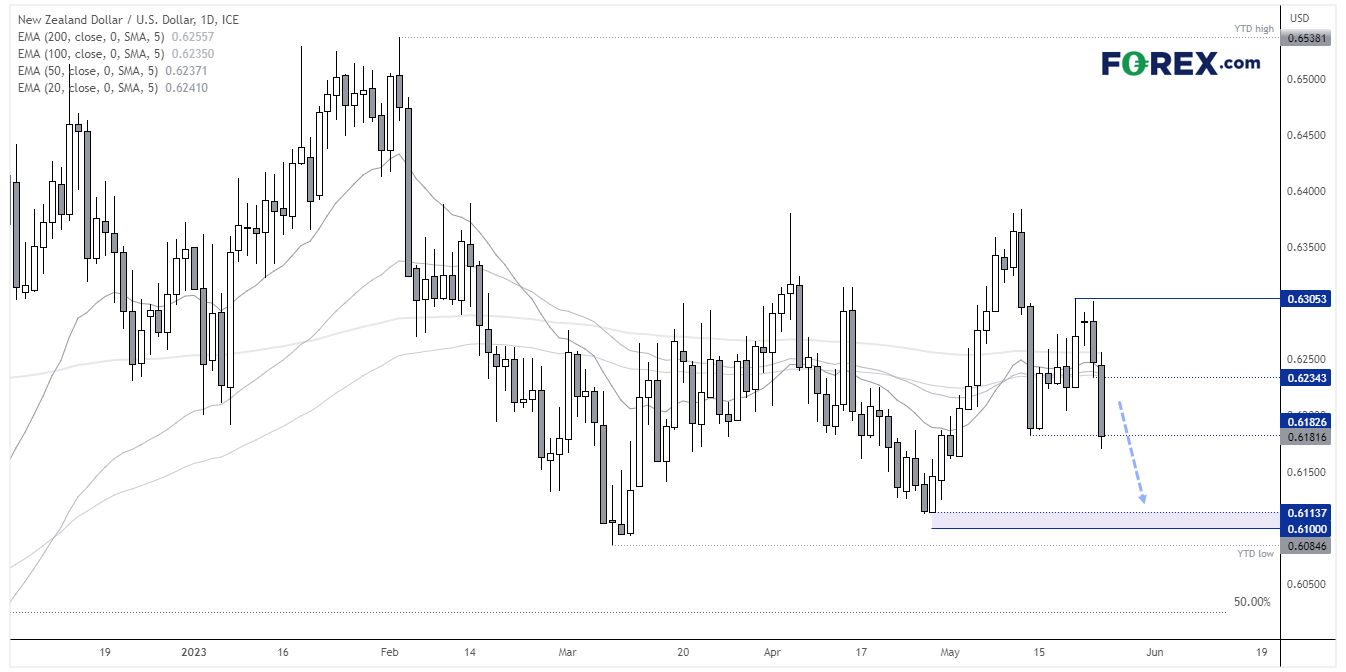
After failing to hold above 63c in recent sessions, momentum has turned sharply lower and seen a clean break beneath the 20, 50, 100 and 200-day EMAs. NZD/USD is on track for its worst day in seven, although prices are showing signs of stability around the 0.6182 low ahead of the European open. This risks a minor rebound from current levels but, with trades across Europe and the US yet to react, the potential for a second round of selling remains. Ultimately, any pullback towards the 0.6235 lows could be seen as a gift to bearish swing traders, assuming any such pullback makes it that far. But with the RBNZ signalling the end of their tightening cycle, we suspect a move down to 61c is feasible, especially if the US dollar weakens.
NZD/USD 4-hout chart
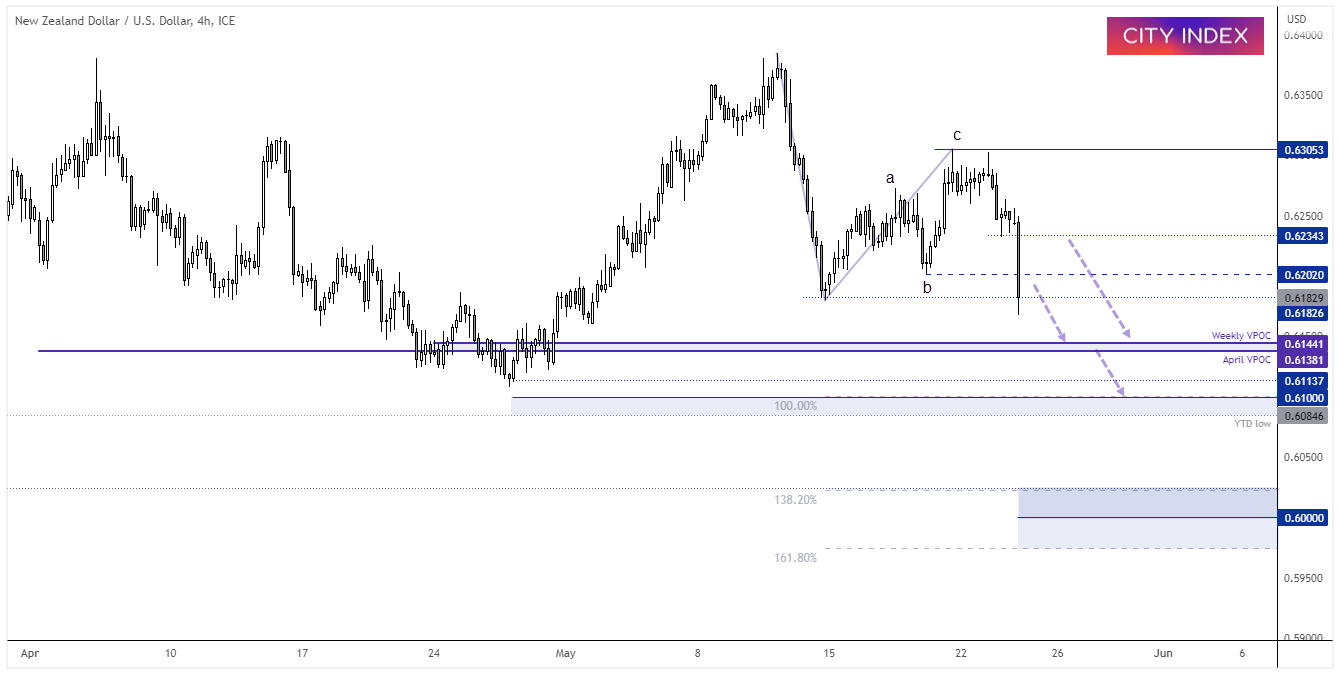
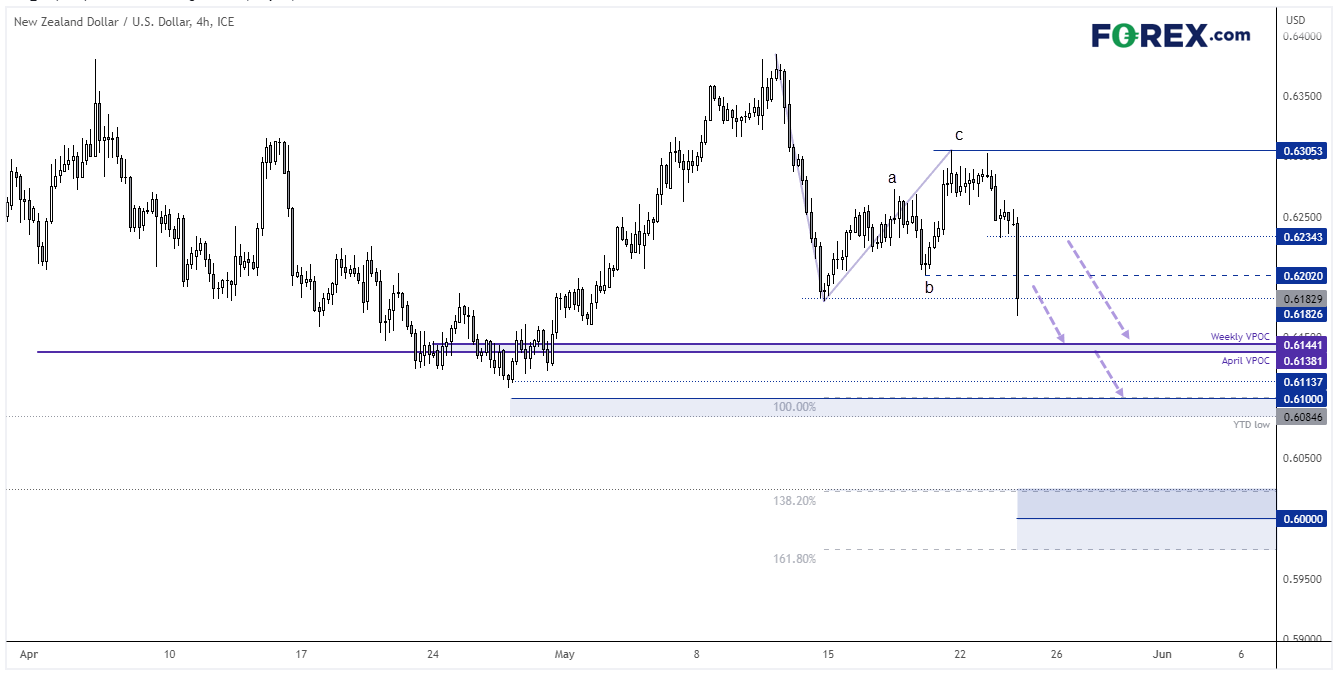
As it appears as though an ABC correction has completed, the turn lower in momentum should mean we’re now in a wave III of an impulsive move lower. If so, a conservative 161.8% projection sits at 0.5975. However, there are several levels along the way, such as the YTD lows around the YTD low and 100% projection, and of course the 60c level which could provide strong support. Initially at least.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Forecast: Euro Under Pressure After Strong NFP Data
As the trading week comes to an end, the euro has once again struggled to sustain a meaningful recovery against the U.S. dollar, highlighting renewed weakness within EUR/USD price action. During the final trading session of the week, the pair declined nearly 0.7%, reflecting that confidence around the European currency remains limited in the short term.
Australian Dollar Short-term Outlook: AUD/USD 3% Plunge Puts Multi-Month Range at Risk 11 6 2026
A sharp equity-led selloff has driven AUD/USD toward critical June-low support, with strong NFP data adding pressure ahead of next week’s U.S. CPI.

Nasdaq 100 forecast: Tech stocks rebound but AI concerns linger
The Nasdaq 100 rebound has run into former support as fears over AI regulation and spending linger. Fawad Razaqzada explains why he maintains a cautious forecast and where the key levels sit.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.