





RBNZ Holds But Keeps Door Open For A Cut In August
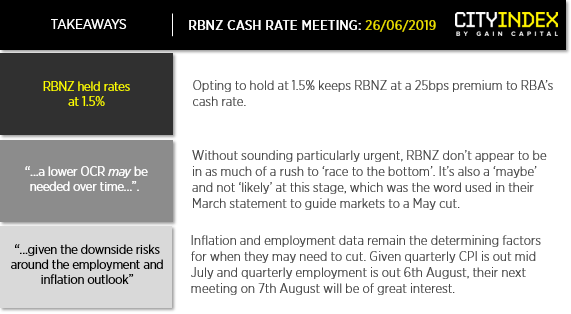
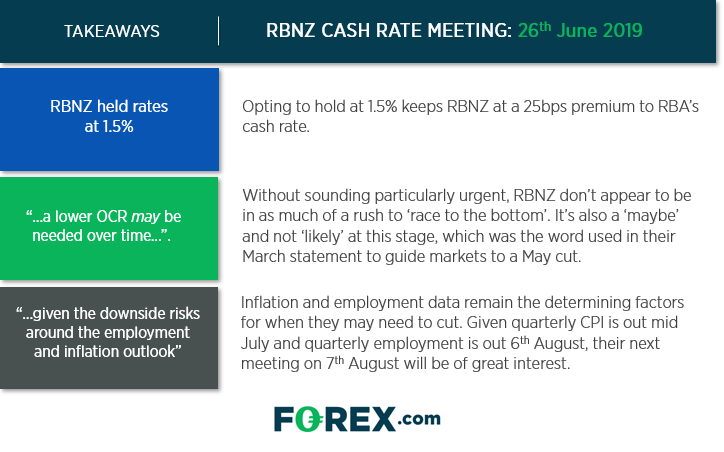
RBNZ held rates at record lows of 1.5%, opting not to play catch up with RBA’s 1.25%. Yet by reintroducing talk of a cut, they kept the door open easing in August.
Share this:

RBNZ held rates at record lows of 1.5%, opting not to play catch up with RBA’s 1.25%. Yet by reintroducing talk of a cut, they kept the door open easing in August.
Statement summary
- The Official Cash Rate (OCR) remains at 1.5 percent
- A lower OCR may be needed over time
- Domestic growth has slowed
- Downside risks related to trade activity have intensified
- Low rates and government spending to support growth and employment
- Given downside risks around employment and inflation outlook, a lower OCR may be needed.
Traders had been expecting a stronger dovish tone to the statement, yet with them keeping a cut in August as a ‘maybe’ and not a ‘likely’, it leaves potential for further short covering on the Kiwi dollar on the near-term (barring jawboning from Adrian Orr, who speaks shortly). Of course, it still paves the way for a potential cut in August, but it will likely hinge upon domestic inflation and employment data, alongside trade developments.
NZD is currently the strongest major of the session, with NZD/JPY leading the board and already testing its typical daily range. Indeed, this invalidates the swing trade short idea, as the fundamentals do not match up with the technicals. Moreover, bullish momentum has taken it clearly above the 50% retracement level highlighted.
GBP/NZD has hit a new cycle low after breaking out of compression. The 8 and 20-day eMA’s are curling lower and crossed back beneath the 200-day eMA. Given the increasingly net-short exposure of GBP traders highlighted in our weekly COT report and the political uncertainty with the UK’s hunt for the next PM, we suspect the path of least resistance likely points lower. A daily close back above 1.0908 support would place it on the backburner but, ultimately the trend remains bearish below 1.9415.
EUR/NZD has broken its March 2018 trendline and could head for the 1.6916 low, near the 200-day eMA. A dovish ECB and less dovish than expected RBNZ has proven to be a decent short catalyst. A daily close below the trendline would be preferred, however we remain bearish whilst it trades back below 1.7110.
Keep in mind that RBNZ’s governor, Adrian Orr is due to speak shortly. If he can speak without jawboning the currency and undermining the statement, the bearish bias remains for GBP/NZD and EUR/NZD.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.
Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.

US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.