



S&P 500 analysis: Stocks rebound on Treasury announcement but rising oil keep investors on edge
US index futures were broadly flat by midday London, following a sharp decline in the previous session. That was before the US Treasury announced thar it was increasing buybacks of long-term debt. That announcement has just caused yields to take a dip, while stock futures and gold have rallied.
Share this:
US index futures were broadly flat by midday London, following a sharp decline in the previous session. That was before the US Treasury announced thar it was increasing buybacks of long-term debt. That announcement has just caused yields to take a dip, while stock futures and gold have rallied. Let’s see if it will have a lasting impact, though. Until now, sentiment was quite downbeat as US equities had fallen for three consecutive trading days, with warning signals from the oil and bond markets finally beginning to weigh more heavily on risk appetite. Our S&P 500 analysis suggests a cautious approach is still warranted in light of the recent bearish price action and a not-so-great macro backdrop.
Among the major US indices, the Nasdaq 100 took the brunt of the sell off yesterday with a 1.7% drop, while other major global indices also ended lower. The crowded AI trade has lost some momentum as bond yields continue to climb, raising the question of whether this is simply a pause within the broader equity rally or the start of something more significant.
Much will depend on what happens next with oil prices and long-term yields. If both continue to rise unchecked, the risk of a more disruptive period for equities will increase, even as weaker US economic data has recently reduced some of the pressure on the Fed to raise interest rates.
Energy risks keep investors cautious
The relatively calm tone this morning has done little to improve the broader mood. The persistence of oil prices remaining high are continuing to raise concerns about inflation.
The issue is especially acute for European markets, given the region’s dependence on imported energy. Another inflationary shock to an economy that is already struggling with elevated costs at a time when interest rates are already relatively high is never a good thing for risk appetite. But the impact is no longer confined to Europe, with Wall Street now increasingly feeling the pressure as well.
To make matters worse, there are no signs of a meaningful de-escalation in the Middle East. Donald Trump has rejected an extension of the truce, while Iran has repeatedly said that the Strait of Hormuz will remain closed until the blockade and oil embargo are lifted.
With crude oil elevated and natural gas prices already close to their highs for the year, the risk of a prolonged supply disruption is starting to weigh on risk appetite.
Rising yields: bad news for growth stocks
Bond markets have also been providing a major source of concern. But yields took a tumble after the Treasury announced its doubling buybacks of long-term debt. This comes after yields had climbed to multi-year or multi-decade highs across several major markets.
Higher government bond yields increase the opportunity cost of holding riskier assets, particularly growth stocks whose valuations depend heavily on future earnings. This makes the S&P 500, which has significant exposure to large technology companies, especially vulnerable.
The bond sell-off accelerated yesterday, sending yields higher before some of the move was subsequently reversed. The US 30-year Treasury yield has risen to 5.337%, its highest level in almost two decades. Japan’s 10-year yield is also approaching 3%, a level not seen since the mid-1990s, while eurozone yields remain close to multi-year highs.
The combination of higher energy costs and rising long-term borrowing costs is becoming difficult to ignore. Until either oil prices or yields begin to stabilise, or fall back, the recent weakness in stocks may have further to run. Today’s Treasury announcement has certainly helped to stabilise the bond market but let’s see if it will have any lasting impact.
Technical S&P 500 analysis and levels to watch
From a purely technical S&P 500 analysis point of view, the trend remains bullish for now, despite the fact the index has given back some gains in recent days. Considerably more technical damage would need to occur for the index to turn decisively bearish. So far, the selling pressure has not been significant enough to trigger a reversal in the broader trend. However, that could change if the fundamental backdrop does not improve.
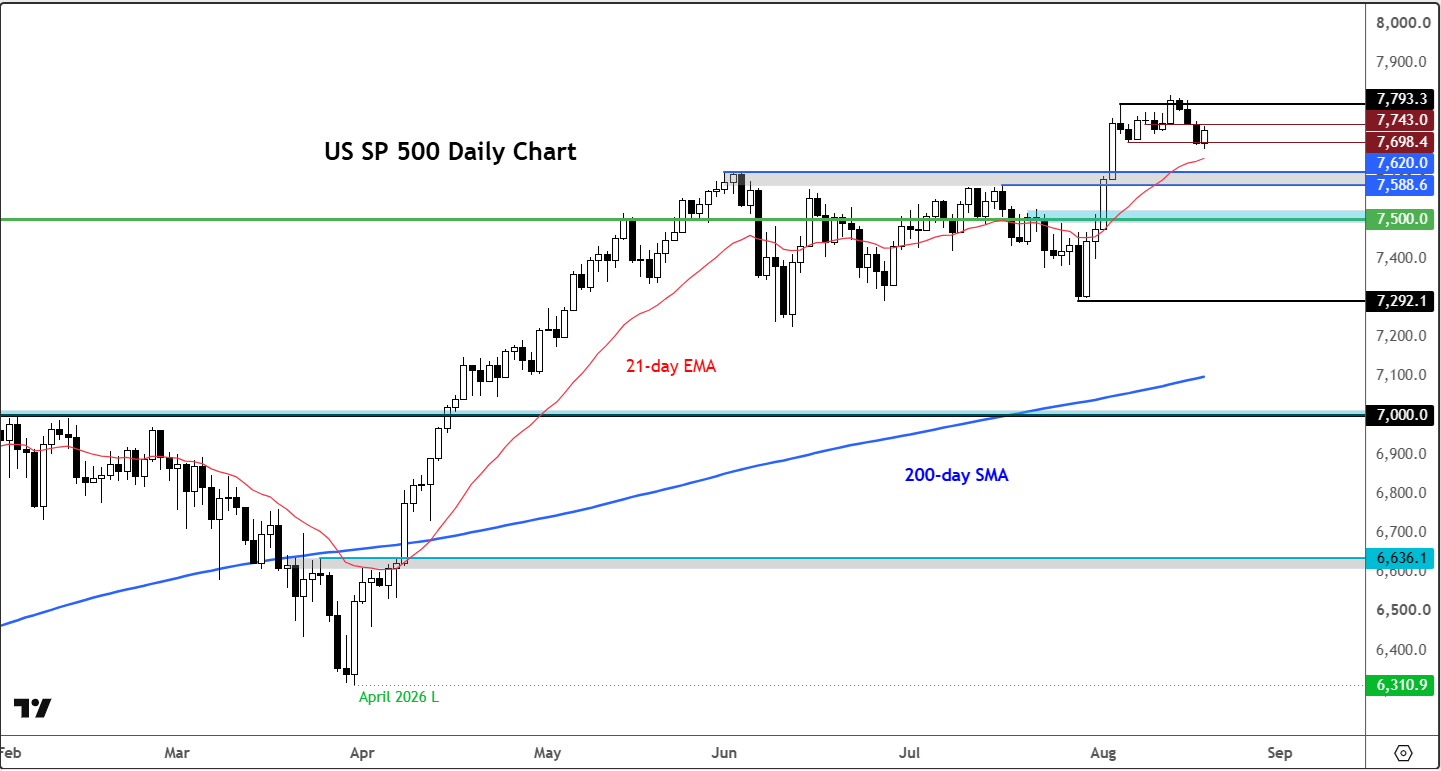
In the very short term, we have seen a breakdown of a couple of important support levels. The first was at 7,743, followed yesterday by 7,698. These levels had previously acted as support but could now turn into resistance if the index retests them from below.
If the selling pressure continues, the next downside target could be the previous all-time high around 7,620, which was reached in early June. Below that, we have the area between 7,500 and 7,526. This zone is arguably the most important area to watch if we see a more sizeable pullback over the next few days.
Further below, 7,400 represents another potential support level, while the most recent low at 7,292 is effectively the line in the sand. That low was recorded on 29 July. A sustained break below 7,292 would create a lower low, and that would be a significant technical development, potentially confirming that the broader bullish trend has come to an end.
The more recent price action has certainly been bearish, and that is a warning sign that we could be heading for a deeper correction. Still, we would need to see a more substantial deterioration in price action before calling a full trend reversal.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.