


S&P 500 Forecast: SPX muted amid wait for US-Iran deal details & ahead of tomorrow’s FOMC decision
U.S. futures are pointing to a muted start as investors await further details on the U.S.-Iran peace agreement and look ahead to Wednesday's Federal Reserve interest rate decision.
Share this:


US futures
Dow futures 0.1%, S&P futures 0.033% & Nasdaq futures 0.03%
In Europe
FTSE 0.5% & DAX 0.46%
- U.S stocks muted as investors eye US-Iran deal cautiously
- FOMC kicks off its two-day meeting under new Fed Chair Warsh
- SpaceX rises for a 3rd day
- Oil extends declines on hopes the Strait will be re-opened on Friday
U.S. Futures Steady Ahead of Fed Decision as Markets Assess Iran Deal
U.S. futures are pointing to a muted start as investors await further details on the U.S.-Iran peace agreement and look ahead to Wednesday's Federal Reserve interest rate decision.
Markets are seeking greater clarity on the terms of the deal, particularly around the reopening of the Strait of Hormuz and Iran's nuclear programme. While investors have been disappointed by failed agreements before, the sharp decline in oil prices suggests markets are increasingly pricing in a normalisation of global energy supplies over the coming months.
Attention is also turning to the Federal Reserve, which begins its two-day policy meeting today, the first under Chair Kevin Warsh.
The Fed is widely expected to leave interest rates unchanged at 3.50%-3.75%. However, the focus will be on updated projections, the dot plot and guidance from Warsh. Investors will also be watching for any signs that the Fed removes the easing bias from its previous statement. However, Warsh is expected to prefer a less is more approach in the policy statement, as he does not believe in forward guidance and may eliminate the dot plot that has guided the markets since 2012,
While falling oil prices have eased inflation concerns, headline inflation remains elevated at 4.2%. The combination of sticky inflation and a resilient labour market gives policymakers flexibility to keep policy restrictive for longer if needed.
As a result, the recent rally in equities faces an important test. Lower energy prices are supporting risk appetite, but a more hawkish-than-expected Fed could limit further gains in the near term.
Corporate Movers
SpaceX is rising over 8% pre-market, extending gains from the company's blockbuster IPO. The stock is set to surpass Amazon in market value and become the world's fifth largest company.
Qualcomm is rising 5% after J.P. Morgan lifted its price target on the semiconductor company and placed the shares on positive catalyst watch ahead of its upcoming investor day.
S&P 500 Forecast – Technical Analysis
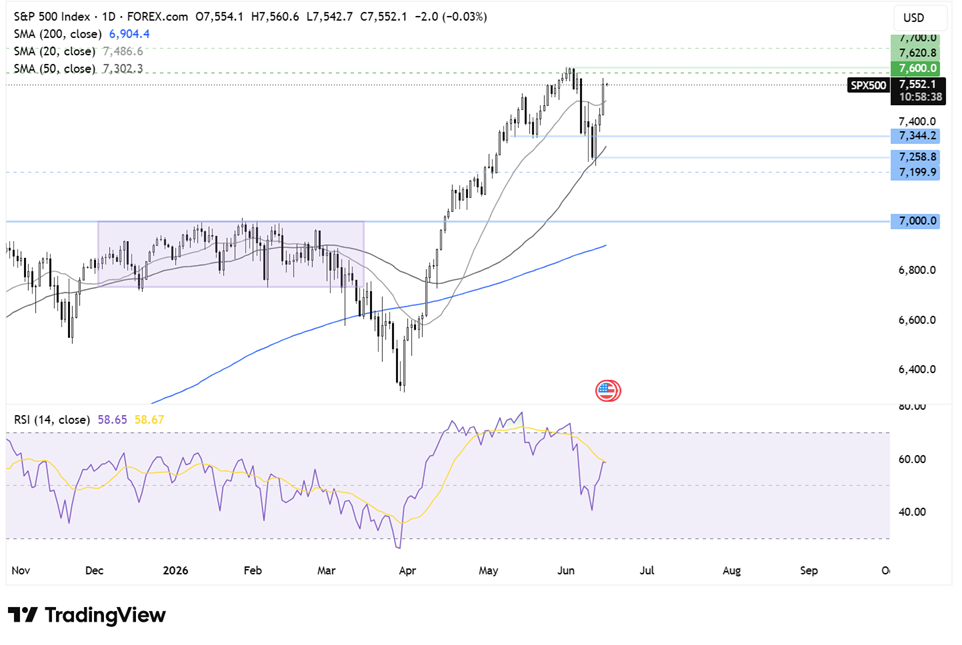
The S&P 500 has extended its recovery from the 50-day SMA, rising to 7,550 at the time of writing.
Buyers will look to extend gains towards the record high at 7,620. A break above this level would bring fresh record highs into focus.
Momentum is showing signs of slowing. Initial support can be seen at the 20-day SMA at 7,475, with a break below exposing 7,350, the May swing low, and the 50-day SMA at 7,300. A move below this area would weaken the near-term bullish outlook.
FX Markets – USD steady, EUR/USD rises
The U.S. dollar is broadly steady as falling Treasury yields offset expectations that the Fed will maintain a restrictive policy stance. Investors are balancing optimism surrounding the U.S.-Iran agreement against the possibility of a hawkish message from the Fed.
EUR/USD is rising as improving sentiment offsets softer economic data. German ZEW economic sentiment returned to positive territory in June, suggesting investor confidence is recovering as energy price concerns ease.
GBP/USD is little changed ahead of UK inflation data, the Bank of England rate decision and Thursday's Macclesfield by-election. While inflation is expected to rise to 3.3%, the BoE is still expected to leave rates unchanged as it balances persistent price pressures against a weakening economy and softer labour market conditions.
Oil Falls as Supply Concerns Ease
Oil prices are extending losses after falling around 5% on Monday, dropping to their lowest level in three months.
Markets are increasingly pricing in the reopening of the Strait of Hormuz and a recovery in Middle Eastern oil exports, reducing the geopolitical risk premium that had supported crude prices.
Attention is now shifting towards how quickly supply can normalise. Goldman Sachs has lowered its Brent forecast and expects Gulf exports to return to pre-conflict levels by the end of July.
Demand-side concerns are also weighing on prices. China's crude oil imports fell 29% in May to their lowest level in eight years, highlighting weaker demand from the world's largest oil importer.
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Analysis: Earnings Uncertainty Continues to Weigh on the SPX
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.
Nasdaq 100, S&P 500 Smashed as AI Bubble Fears Run Risk Aversion
It’s been a rocky few weeks for stocks starting with a bearish engulf in NVDA a few weeks ago and then the same formation in the S&P 500 two weeks ago. Sellers have since chewed through supports and fear is starting to spread, but is this the beginning of the end for the AI rally?
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.