

S&P 500 Forecast: SPX rises as tech rebounds ahead of earnings
S&P 500 and the Dow Jones are set to open higher as dip buyers emerge following last week’s AI sell-off, oil prices decline and attention turns to key earnings reports this week.
Share this:

US futures
Dow futures -0.1%, S&P 500 futures 0.51% & Nasdaq futures 1.39%
European futures
FTSE -1%, DAX -1.3%
- US stocks head to a mixed open with tech rebounding
- AI worries ease as attention turns to tech earnings
- No rate hike is expected this month
- Oil prices fall from multi-month highs as Trump waives sanctions on Russia
U.S. stocks rise as AI dip buyers step in, oil prices ease and earnings take centre stage
S&P 500 and the Dow Jones are set to open higher as dip buyers emerge following last week’s AI sell-off, oil prices decline and attention turns to key earnings reports this week.
Both the S&P 500 and the Nasdaq 100 posted their largest weekly declines since late June as concerns over the profitability of huge AI investments weighed on tech stocks, particularly data centre operators and memory chip makers.
The sell-off highlights growing investor jitters over the cost of the AI buildout and how it will be financed, particularly at a time when interest rates remain elevated.
The Federal Reserve has acknowledged that the AI boom is contributing to inflation, complicating policymakers' efforts to rein in price pressures.
Chip stocks, which fell sharply last week, are climbing today, with the Philadelphia Semiconductor ETF having dropped 12% last week. Focus is now shifting to a busy week for corporate earnings, with Meta and Tesla due to report on Wednesday and SpaceX on Tuesday.
Elsewhere, oil prices are falling, easing some inflationary concerns and helping Treasury yields move lower. However, lower yields alone may not be enough to restore demand for risk assets if concerns over AI spending persist.
Corporate movers
CoreWeave, which fell 25% last week and was central to mounting concerns over the financing of the AI buildout, was climbing 6% in pre-market trading. Other chipmakers, including Broadcom and Micron, were also up over 3%.
Intel is rising 4% after J.P. Morgan upgraded the chipmaker to neutral from underweight, although analysts expect its turnaround to take years.
Amazon is rising over 1% after Morgan Stanley named it a top pick and raised its price target. Analysts cited accelerating growth at Amazon Web Services, the potential of its Bedrock AI platform and efficiencies driven by robotics.
S&P 500 forecast – technical analysis
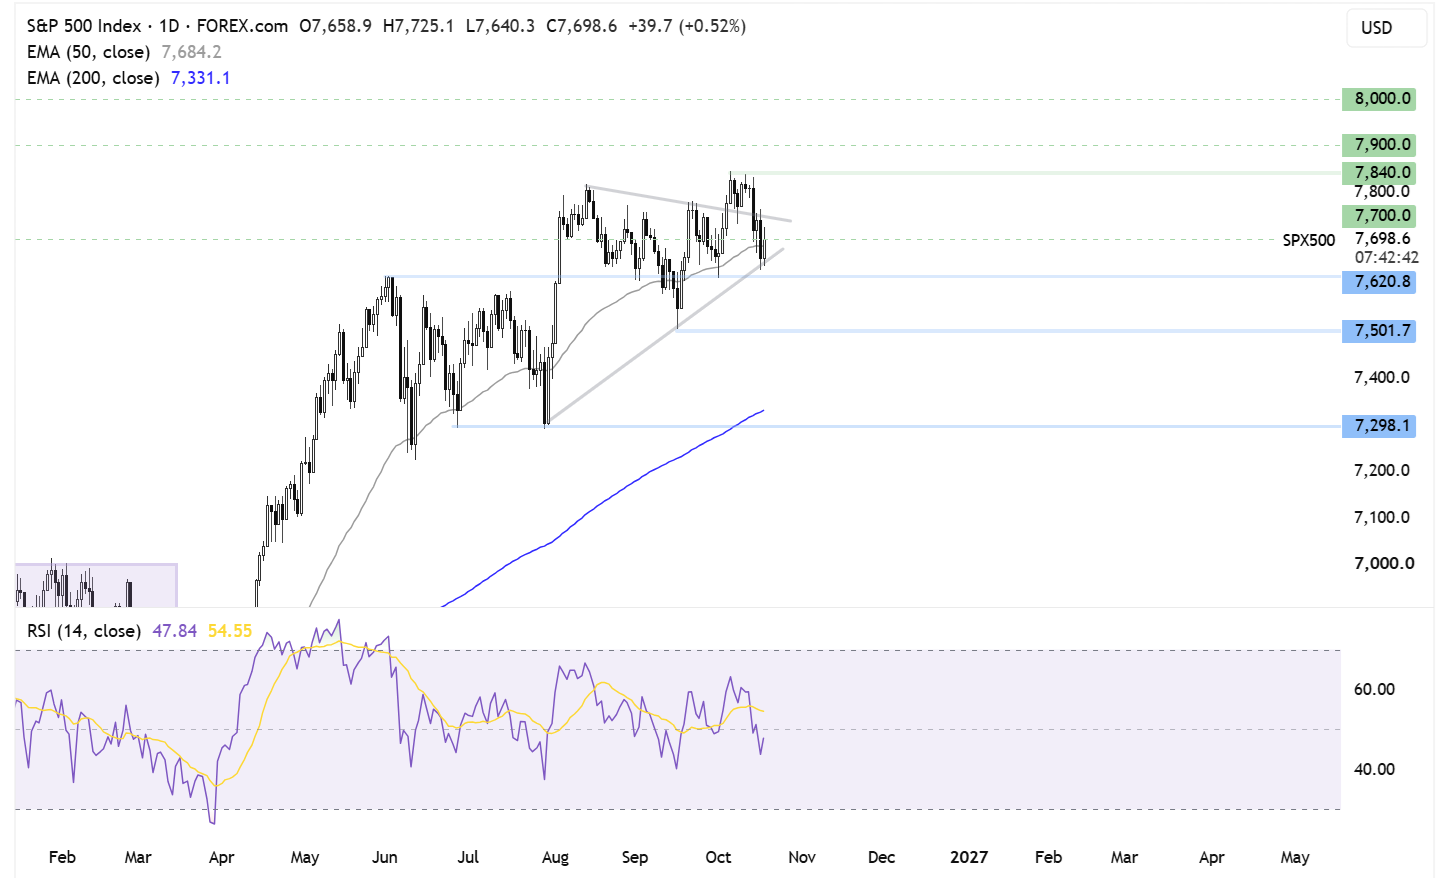
The S&P 500 has re-entered the symmetrical triangle pattern after a brief attempt to break out to the upside. The price has once again tested rising trend-line support around 7,650 and has pushed back above the 50 EMA.
Buyers would need to rise above 7,755 to break out to the upside, opening the door to 7,844 and fresh record highs.
To break out to the downside of the triangle pattern, sellers would need to take out support at 7,650 and 7,620, bringing 7,500 into focus.
FX markets – dollar holds steady, EUR falls
The U.S. dollar is holding steady on Monday after losses last week. The dollar tracked Treasury yields lower over the past week, even after hotter-than-expected U.S. inflation data. Yields are falling again at the start of this week, with the 10-year Treasury yield at 5.07%.
Following Federal Reserve Chair Kevin Warsh's speech at the IMF on Friday, markets are pricing in just a 15% chance of a rate hike this month.
EUR/USD remains under pressure as political unrest in France and elevated energy prices weigh on the single currency. The spread between French and safe-haven German government bond yields has widened amid some of France's worst riots in years, adding to concerns over political stability. Natural gas prices have also risen to a four-year high, raising concerns ahead of winter as European storage levels remain low.
GBP/USD is holding steady around 1.3330 ahead of a busy week for UK economic data. Attention turns to jobs figures on Tuesday, inflation on Wednesday and retail sales on Friday. Markets are pricing in a greater than 90% probability that the Bank of England will raise interest rates at its November meeting, offering some support to sterling. EUR/GBP has risen to its highest level in 17 months amid euro weakness, while stronger-than-expected UK GDP data last week has also supported the pound.
Oil falls after Trump waives sanctions on Russia
Oil prices are falling from a five-month high on Monday, with attention remaining on the conflicts in the Middle East and Ukraine and their impact on supply.
Brent is down over 1.3% after reaching its highest level since May 19 on Friday. Meanwhile, WTI is down 0.3% but remains above $100 a barrel after hitting its highest level since September 17.
Strikes on vessels crossing the Strait of Hormuz mean flows remain well below pre-conflict levels. The increased number of attacks on commercial vessels has seen Gulf crude flows fall to a seven-day average of around 8.5 million barrels a day, down from approximately 20 million barrels a day before the conflict.
There are concerns that Iran could ramp up attacks further in the run-up to the U.S. midterm elections, keeping a significant geopolitical risk premium in oil prices despite Monday's pullback.
Separately, President Trump has signed an executive order waiving some sanctions and tariffs related to Russian exports, a development that could affect the outlook for Russian supply.
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rises as tech rebounds ahead of earnings
S&P 500 and the Dow Jones are set to open higher as dip buyers emerge following last week’s AI sell-off, oil prices decline and attention turns to key earnings reports this week.
Crude Oil Weekly Outlook: Brent Tests September Highs, WTI Tops $100, and XLE Reclaims 18-Year Resistance
Crude Oil Weekly Outlook: Brent is testing its September highs, WTI has moved towards $100, and XLE has reclaimed its 18 year resistance. Explore the key levels that could define the next move in oil.
S&P 500, Nasdaq, Dow and Russell 2000 For the Week Ahead
Stocks started to shake last week and there was even a hint of this in the prior week. The question now is whether we’re at the point where buyers may abandon pullbacks as get closer to mid-term elections.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.