



S&P 500 forecast: Stocks undermined as yields rebound and crude rallies
The major European indices and US index futures fell by mid-day in London. The pressure was once again exerted by familiar forced. Bond yields rebounded sharply and a renewed surge in oil prices weighed on sentiment.
Share this:
The major European indices and US index futures fell by mid-day in London. The pressure was once again exerted by familiar forced. Bond yields rebounded sharply and a renewed surge in oil prices weighed on sentiment. The Treasury’s decision to increase purchases of longer-dated government debt triggered a powerful rally across risk assets on Wednesday, but the relief has proved short-lived for equities. The fact that the S&P 500 has failed to push back towards record highs despite the sharp fall in yields yesterday suggests investors remain uneasy about two issues in particular: oil prices and stretched equity valuations. Consequently, we will maintain a cautious S&P 500 forecast amid increasing risks of a potential correction.
Treasury intervention provided only temporary relief
Long-dated Treasury yields are moving higher again, potentially bad news for the likes of gold and Bitcoin, the major beneficiaries of yesterday's Treasury Department’s decision to significantly increase its purchases of longer-dated government debt, as well as the stock markets.
Looking at the chart, it looks like a classic case of resistance turning into support with the highs of October 2023 (5.178%) and that of May 2026 (5.200%) holding as support.
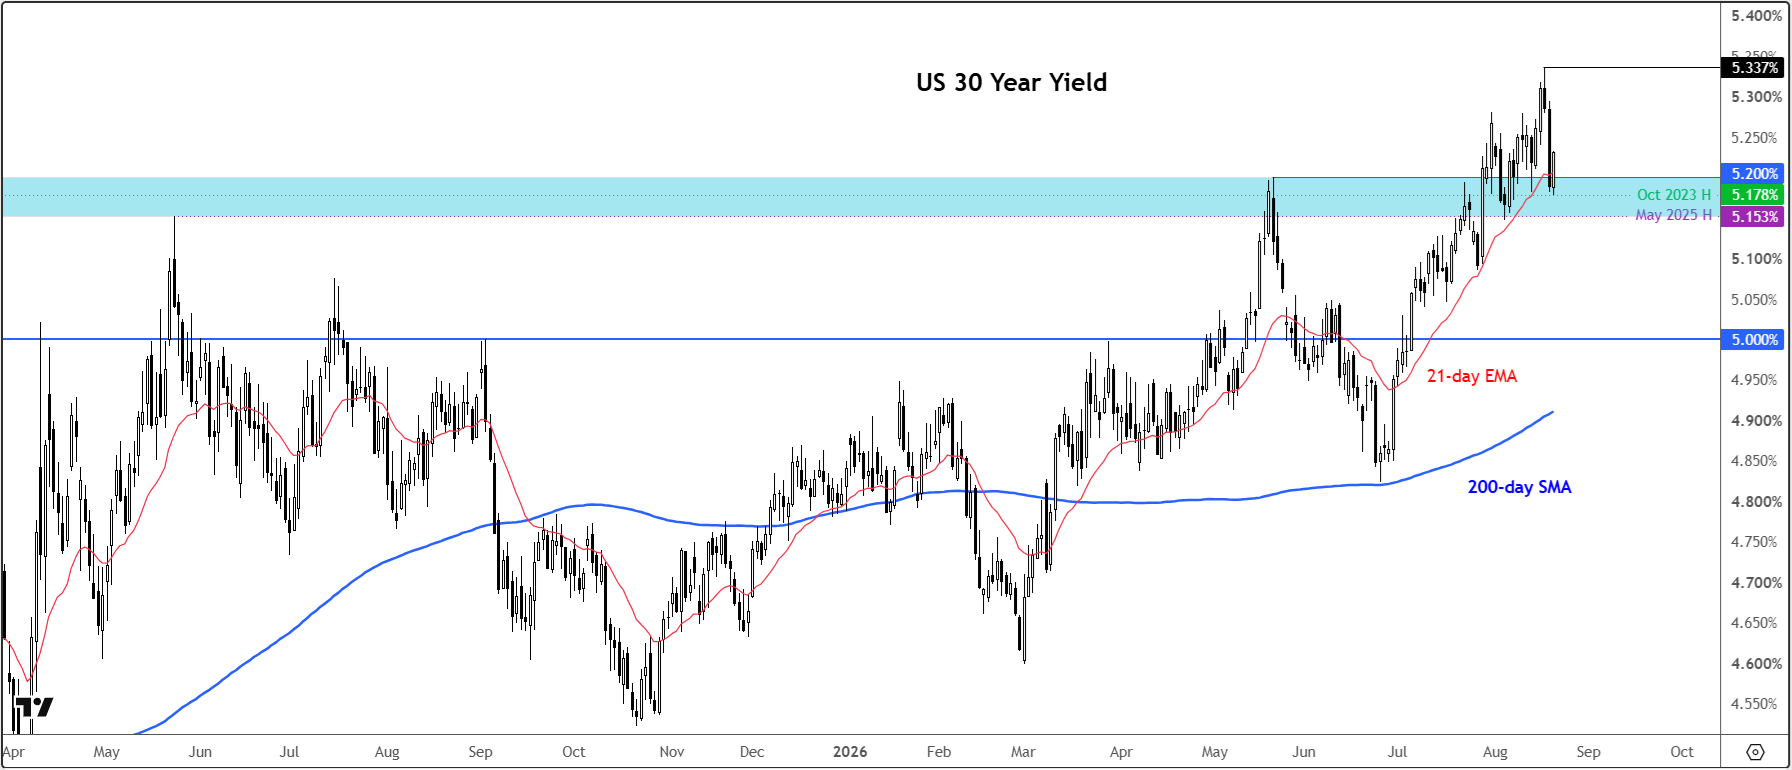
Treasury yields have risen sharply since June, reaching levels not seen since before the global financial crisis. The latest move comes as total US government debt has surpassed $40tn, more than double its level a decade ago.
The unscheduled announcement yesterday was a clear indication of the Treasury’s discomfort with the recent sell-off at the long end of the market.
Ultimately, a more structural solution — particularly fiscal consolidation — would be needed to deliver a sustainable improvement in the bond market. But the message that the Treasury is prepared to be more active in managing conditions at the long end has nevertheless been welcomed by investors.
Yesterday saw risk assets rally sharply, as lower yields improved the appeal of higher-risk assets such as Bitcoin, while also supporting non-yielding assets such as gold. Equities benefited mildly too, helping to keep the AI trade alive for a little longer and providing some support to US indices.
Crude oil extents surge
The key risk, however, remains oil, with prices surging higher again today, putting everything at risk of giving back their gains.
Prices have now surged 3% on the day, increasing inflationary concerns. The Treasury intervention may have bought some breathing room for bonds and risk assets, but a sustained rise in crude could quickly undermine that relief by putting renewed upward pressure on inflation and yields.
Technical S&P 500 forecast and levels to watch
From a technical analysis perspective, the S&P 500 forecast has turned mildly bearish. It has developed some short-term bearish price action, although the broader support structure remains intact – for now.
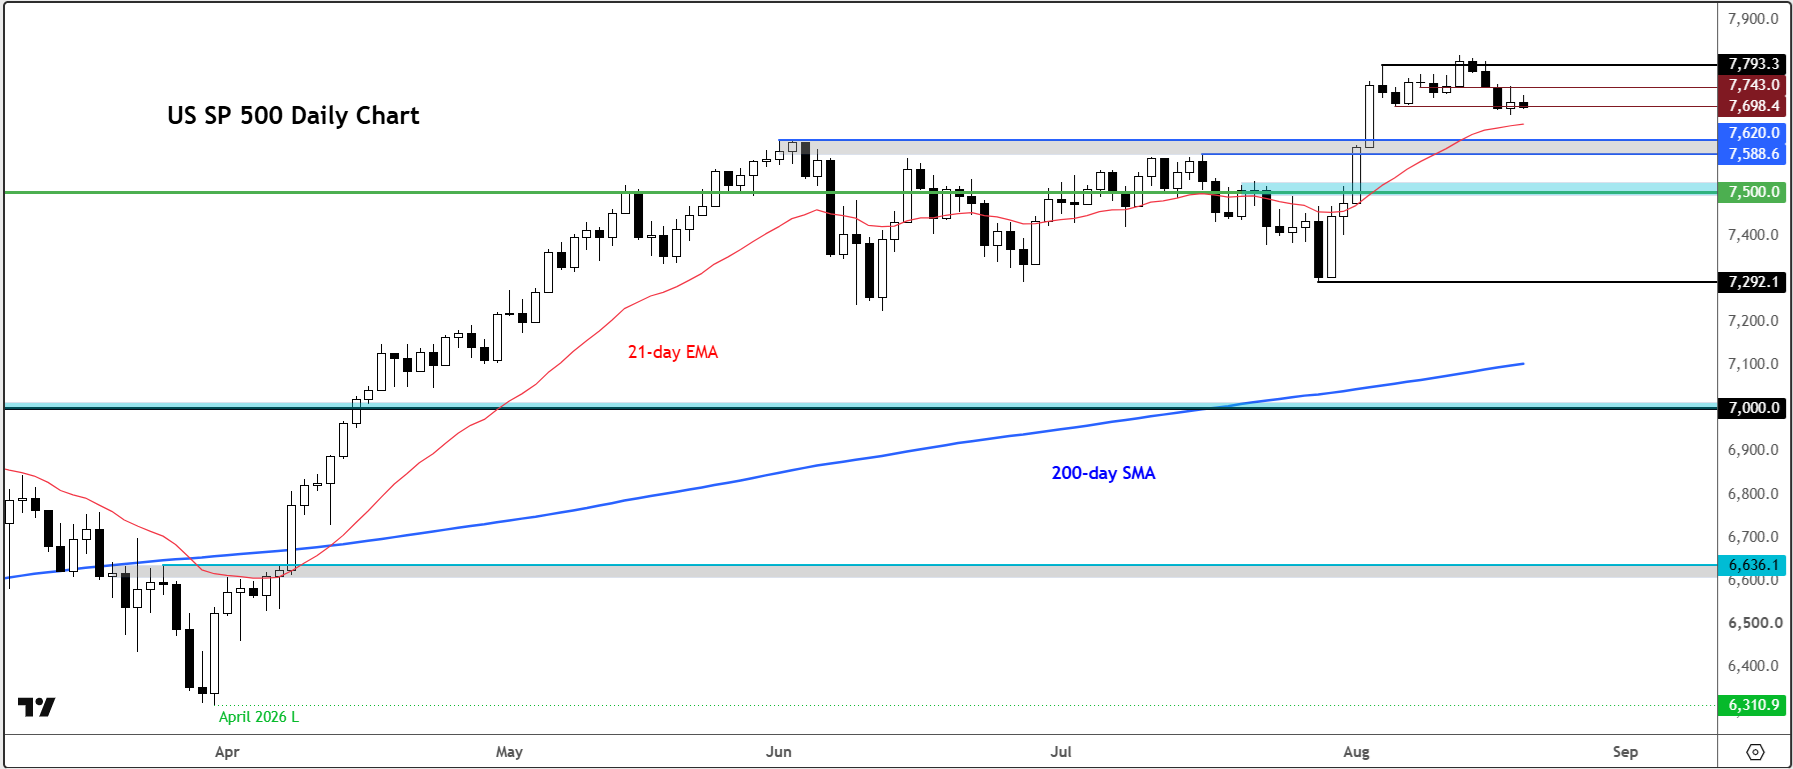
Resistance is currently seen around 7,698, followed by 7,743 and then 7,793 on our US SP 500, derived from the underlying S&P 500 futures chart. These levels previously acted as support, making them important areas for the bulls to reclaim.
On the downside, the index could head to the previous all-time highs around 7,588 to 7,620. A break below that region would weaken the technical picture further and potentially expose the psychologically important 7,500 level.
For now, the S&P 500 remains caught between supportive bond-market intervention and increasingly challenging oil and inflation dynamics. The Treasury may have bought markets some time, but whether that translates into another leg higher for equities will depend heavily on what happens to crude and long-term yields from here.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.

Nasdaq 100 forecast: Stocks rebound but AI concerns linger
The Nasdaq 100 was finding some support at 28,000 after recent sell-off amid concerns about the AI trade. Even with oscillators oversold, the risk to the near-term forecast is tilted to the downside.
Silver outlook: a return to the 2011 high tests $49 to $50 support
Silver is testing key support at $49 to $50, the area of its 2011 high, and has yet to bounce. A bullish reversal candlestick would make the picture more constructive, but for now the near-term forecast hangs in the balance.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.