




S&P 500 Forecast: SPX falls on renewed US-China trade war fears
U.S. stocks are pointing to a lower open as renewed tensions between China and the US raise the likelihood of a costly trade war. Federal Reserve officials, including Chair Powell, are due to speak. ISM manufacturing PMI data is due later and is expected to contract again in May.
Share this:

US futures
Dow futures -0.26% at 42,100
S&P futures -0.36% at 5880
Nasdaq futures -0.56% at 21204
In Europe
FTSE 0.13% at 8776
DAX -0.4% at 23897
- US futures on US-China trade war concerns
- Fed officials, including Powell, are due to speak
- US ISM manufacturing is expected to remain in contraction
- Oil rises as Russia-Ukraine tensions overshadow OPEC+ meeting
Stocks fall as US-China trade war worries return
U.S. stocks are pointing to a lower open as renewed tensions between China and the US raise the likelihood of a costly trade war.
Wall Street indices are set to start the new month and week on a softer note, giving back some of last month's gains as tensions between the US and China ramp up.
At the end of last week, U.S. Treasury Secretary Scott Bessent warned that trade talks with Beijing had stalled, and Trump accused China of violating the consensus it reached in the Geneva trade talks. China is pushing back against these accusations, as relations deteriorate once again.
The US and China agreed to pause triple-digit tariffs for 90 days in mid-May. China also promised to remove trade measures restricting exports of critical metals needed for US semiconductor electronics and defence production.
However, Trump has said he plans to hike tariffs on steel imports to 50% from 25%, as the erratic and coherent trade policies impact market sentiment, reviving the “sell America trade.
Today, a slew of Federal Reserve officials, including Chair Jerome Powell, are due to speak at a conference in Washington, DC. Attention will also be on manufacturing PMI figures, which are expected to show that activity remained in contraction in May at 49.5, up from 48.7 in April.
Looking out across the week, US non-farm payrolls on Friday will be the main focus, with expectations of job creation slowing to 130k from 177k. Weak job growth could fuel concerns over the health of the labour market in light of Trump’s trade tariffs.
Corporate news
Steel stocks rose after President Trump hiked tariffs on the metal. Cleveland-Cliffs jumped 25%, while Steel Dynamics rose 10%.
Chip stocks slide lower on reports that Trump is preparing to tighten restrictions on China’s tech sector by expanding existing rules to include subsidiaries of sanctioned firms. Nvidia falls 1%, Marvell Technologies falls 1.9%, and AVGO falls 0.9%.
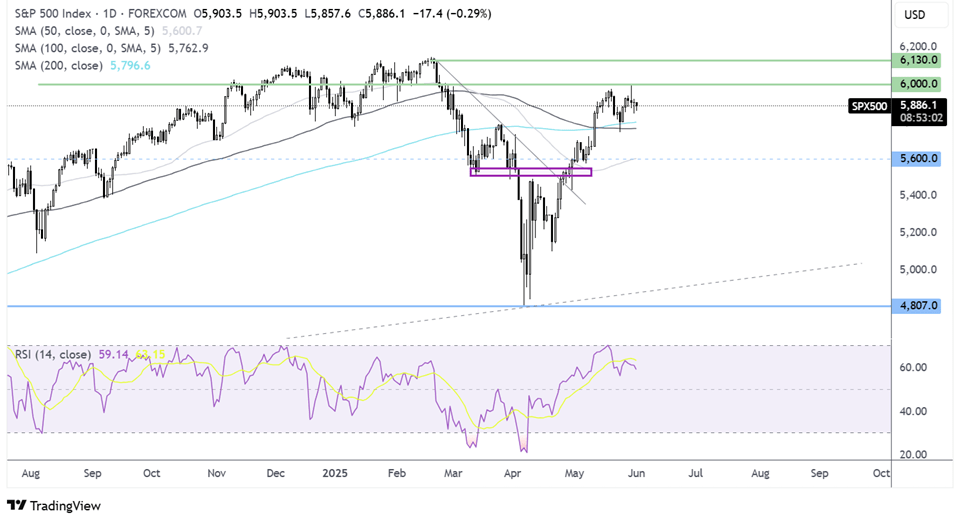
S&P 500 forecast – technical analysis.
The S&P 500’s recovery has stalled below the 6000 key psychological level—the price trades in a holding pattern below 600 but above the 200 SMA at 5800. A breakout above 6000 is needed to create a higher high and bring 6130 the ATH into play. Sellers will need to take out 5800 to gain traction towards 5600.
FX markets – USD falls, GBP/USD rises
The USD is falling amid re-escalating US-China trade war worries and after Trump announced 50% trade tariffs on aluminium and steel. His chaotic tariff policies hurt confidence towards the USD.
The EUR/USD is rising, pushing above 1.14 on broad-based USD weakness. Eurozone manufacturing PMI figures showed the sector contracted modestly at 49.4 in May. This marks the fifth straight monthly improvement and its best reading in 3 years.
GBP/USD is rising, breaking above 1.35, capitalising on the weaker USD. The pound has been supported by expectations that the BoE could be more cautious in cutting rates further from here. This week, the BoE Treasury Select hearing will shed more light on the BoE’s plans for rate cuts this year. Two more 25 bps cuts are expected.
Oil rises as Russia-Ukraine tensions rise & despite OPEC+ output increase
Oil prices rose 3% at the start of the week after Ukraine's drone attacks deep in Russia raised concerns over an escalating war and supply. This overshadows OPEC+ lifting oil output this weekend.
OPEC+ agreed to increase output by 411,000 barrels per day in July, marking the third straight month of the same increase. However, this mood was widely priced in.
As a result, markets are reacting to Ukraine's drone strikes on Russia's military airports over the weekend, which have brought a new element of supply risk into the market.
Meanwhile, lower US food inventory ease, combined with a surge in gasoline demand ahead of peak summer driving season, adds further support.
Meanwhile, on the demand side, Asian crude imports, particularly from China, have softened, pointing to some caution in the face of the economic uncertainty stemming from Trump's trade tariffs.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.