


US Economy, Fed Outlook & Market Moves | DAX Technical Analysis
The US economy faces pivotal jobs data and shutdown risks as markets weigh Fed rate cuts. Strong GDP and falling jobless claims challenge easing bets, while global equities show stretched valuations. Gold hits record highs, copper surges on supply shocks, and crypto slides. Meanwhile, DAX charts point to a potential bullish breakout as technicals strengthen, giving investors a roadmap for the week ahead.
Share this:

US Economy & Fed Outlook
- Jobs data focus: Friday’s employment report is key for the Fed, with expectations of modest payroll gains and a 4.3% unemployment rate.
- Shutdown risk: A potential US government shutdown could delay payrolls data, forcing the Fed to rely on private surveys before its October meeting.
- Policy expectations: Markets price a 90% chance of an October rate cut and a two-thirds chance of another in December, but strong data could temper easing.
- Recent data impact: Stronger-than-expected GDP (+3.8% annualized in Q2), durable goods orders, and falling jobless claims reduced expectations for aggressive cuts.
Markets & Valuations
- Equities: The S&P 500 trades at 22.8x forward earnings, close to a 5-year high, leaving valuations stretched.
- Asia: Chinese and South Korean equities gained, while Japan’s Nikkei fell after a strong September.
- UK: The FTSE 100 held firm despite tariff risks and pharma weakness; travel & leisure supported gains.
- Pharma stocks: AstraZeneca and GSK pressured lower on US tariff proposals targeting branded drugs.
- Gilts & FX: UK gilt yields rose amid weak auctions and fiscal concerns; the pound fell sharply to $1.3355.
Commodities & FX
- Gold: Hit a record above $3,800/oz, supported by shutdown fears, geopolitical tensions, and dollar softness.
- Oil: Prices eased on rising supply.
- Copper: Prices surged to ~$10,360/t after Indonesia’s Grasberg mine halted operations due to a natural disaster, with output shortfalls expected through 2026.
- Crypto: Bitcoin dropped below $109,000, erasing $170bn from crypto markets.
- Treasuries: Gained as investors sought safety.
Global Central Banks
- PCE Core Inflation: August +0.2% m/m and +2.9% y/y, in line with consensus, keeping Fed on track but not altering expectations.
- Switzerland (SNB): Maintained 0% policy rate and FX intervention stance. Inflation remains subdued (0.2% in August). GDP slowed to +0.5% in Q2, with outlook capped by weak exports and tariffs. Growth projected at 1–1.5% in 2025, <1% in 2026, with rising unemployment.
Sector & Country Developments
- India – IT under pressure:
- H-1B visa fees hiked from ~$5,000 to $100,000.
- New US proposals to tax outsourced services at 25% and remove tax deductibility threaten profits.
- MSCI India IT Index fell over 3% on Monday.
- US agriculture: Soybean farmers hit as China halts purchases amid tariff tensions.
- Corporate: EA reportedly near a $50bn go-private deal (WSJ).
- Apple supply chain: Chinese factory workers face harsh conditions rushing to produce iPhone 17s (China Labour Watch).
Political & Policy Headlines
- US shutdown negotiations: President Trump to meet congressional leaders; warned that without a deal, “the country closes.”
- Tariffs: US tariff risks weighing on global growth; pressure particularly on pharma and Swiss exporters.
Key Events This Week
- RBA rate decision
- US JOLTS job openings
- US Non-farm payrolls (Friday)
- Speeches: President Trump (20:15), FOMC’s Williams (20:30)
DAX Technical Analysis 4 hours
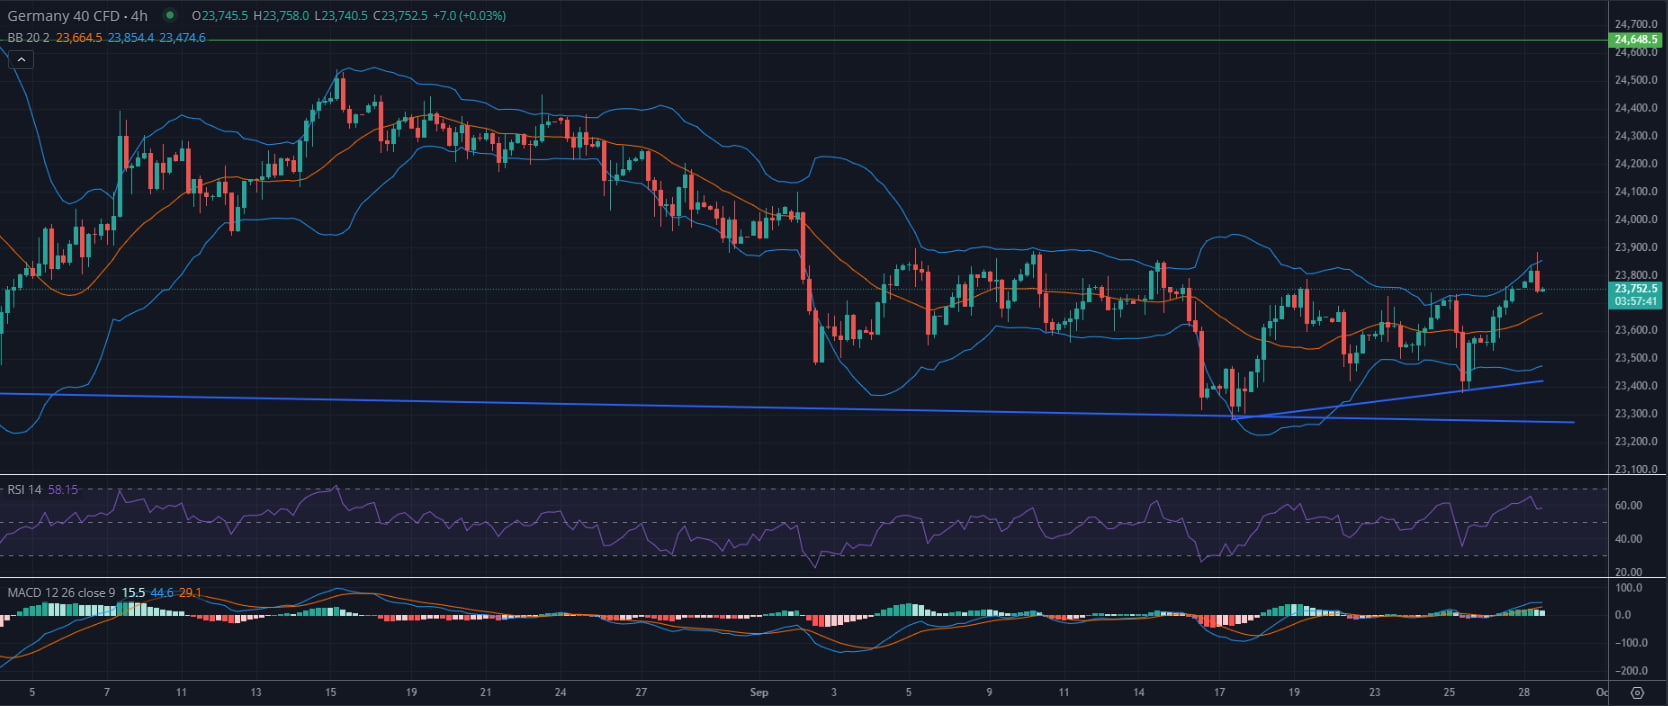
Looking at the Germany 40 CFD on the 4H timeframe, price action shows a recovery from early September lows near 23,200, with a rising trendline offering short-term support. The recent bounce has pushed price back toward the 23,800 zone, where it briefly pierced the upper Bollinger Band before easing slightly. This suggests near-term overextension, but the overall structure points to a gradual shift from a sideways consolidation into a potential uptrend. RSI at ~58 remains supportive without being overbought, while the MACD has crossed into positive territory, reinforcing bullish momentum.
Key levels are clear: immediate support sits around 23,500 and again near the rising trendline (~23,300), while resistance lies overhead near 24,000–24,100 and more prominently at 24,650. As long as the price holds above the rising trendline, bulls maintain the advantage, with further upside possible on a clean break above 24,000. However, a failure to hold above 23,500 could risk dragging the index back toward 23,200, neutralizing the emerging bullish case.
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Nears New Highs as Investors Rotate Back Into Growth
The DAX continues to push higher, trading above 26,500 as investors extend last week's recovery. Falling oil prices, improving sentiment toward technology stocks and stronger-than-expected German industrial production have helped support risk assets globally. Attention now turns to US inflation data and a busy earnings calendar, which will determine whether the rally can continue toward fresh record highs.
DAX Rebounds as Investors Look Beyond the AI Selloff
The DAX has started the week on a stronger footing, recovering from last week's technology-driven selloff and pushing back toward the key 26,000 level. Improving sentiment across global markets, easing oil prices and a positive reassessment of technology valuations have helped support the rebound. Attention now shifts to Tuesday's US inflation report and a busy earnings calendar, both of which will determine whether the recovery can extend further.
DAX Weakens as Tech and Defence Stocks Come Under Pressure
European equities are under pressure as the global technology selloff extends into a second session. Concerns about AI-related capital expenditure, semiconductor demand and regulatory risks are weighing heavily on technology stocks, while rising oil prices add another layer of uncertainty. With the US jobs report due later today, investors are reassessing valuations, growth expectations and the outlook for interest rates.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.