


USD, yields jolted as Fed hesitant to be ‘over-easy’ ahead of Trump 2.0
The expected 25 cut was delivered. But the Fed were understandably cautious regarding future cuts, given they don't know which or how many of Trump’s inflationary policies will see the day of light. And that means the current pullback on the USD and yields could be limited.
Share this:
The Fed cut their interest rate by 25bp as expected, although the cut was little surprise given Fed fund futures had implied a near 100% probability of it this week. They will depend on incoming data to decide whether to cut in December, which is all but certain given Powell cited a “strong economy” and that it’s “remarkable how well it has been performing”.
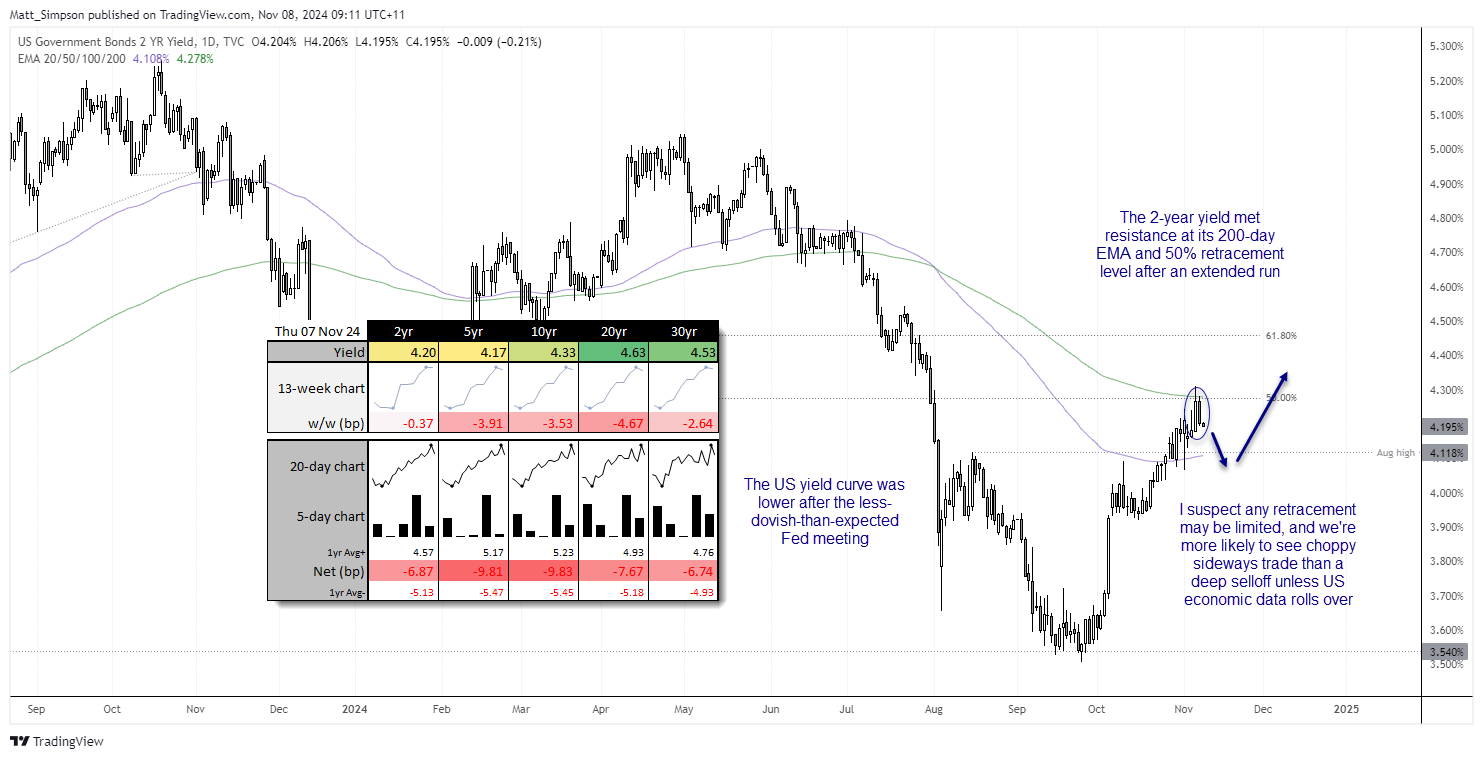
As I’d hypothesised earlier this week, it was not a particularly dovish cut. And that resulted with an inevitable pullback in yields and USD, allowing Wall Street indices to reach new record highs. The 2-year yield formed a bearish inside day after meeting resistance at its 200-day EMA and 50% retracement level. This seems natural after an extended from its September low, but not detrimental to its trend. If the Fed are less dovish due to Trump’s policies being inflationary, then we may find any retracement for yields (and therefor the USD) to be limited unless US economic data rolls over.
Powell said he doesn’t see inflation expectations anchoring higher and that they won’t allow them to drift higher. A weaker labour market could see them cut more quickly but, in all likelihood, they will continue to make interest rate decisions on a meeting-by-meeting basis. Especially with Trump due to return to the Whitehouse in January.
While he did not mention the incoming Trump administration, Powell expects geopolitical risks could rise from already elevated levels next year. Therefore, the Fed “don’t want to do a lot of forward guidance”. It will therefore be interesting to see how they update their forecasts in December to account for the incoming administration, without knowing which or how many of Trump’s inflationary policies will see the day of light.
The Bank of England (BOE) also cut rates by 25bp to 4.75% with an 8-1 majority (7-2 was estimated by Reuters), with just Catherine Mann voting to hold at 5%. The BOE also upgraded their 1-year CPI forecast to 2.7% from 2.4% in August and 2.2% in 2 years, up from 1.7%. The UK’s recent budget is of course the culprit behind the upgrades, and which prompted them to say “a gradual approach to removing policy restraint remains appropriate”.
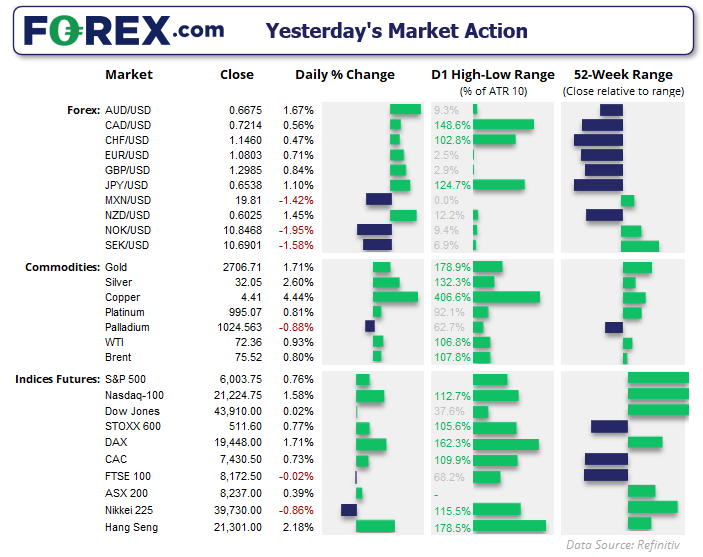
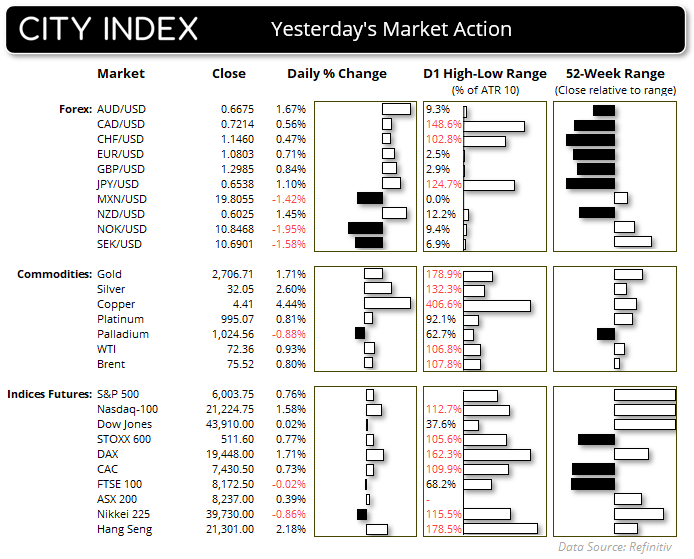
- AUD/USD and NZD/USD were the strongest majors during a risk-on session, the USD was the weakest
- GBP/USD reached my 1.3 target to recoup around 2/3rds of its post-election losses
- AUD/JPY rallied for a second day, moving closer to my 103 target outlined yesterday
- Nasdaq 100 futures closed to a record high, the S&P 500 and Dow Jones extended their post-election record highs for a second day
- Gold futures rose 1.7% to recoup around half of its post-election losses
- Copper futures rebounded 4.4% from Wednesday’s low, recouped most of the day’s losses and closed back above its 200-day SMA
Events in focus (AEDT):
- 10:30 – JP household spending
- 13:45 – RBA assistant governor Jones speaks
- 16:00 – JP leading, coincident indicators
- 20:30 – ECB McCaul speaks
- 22:10 – BOC deputy governor Gravelle speaks
- 23:15 – BOE MPC member Pill speaks
USD index technical analysis:
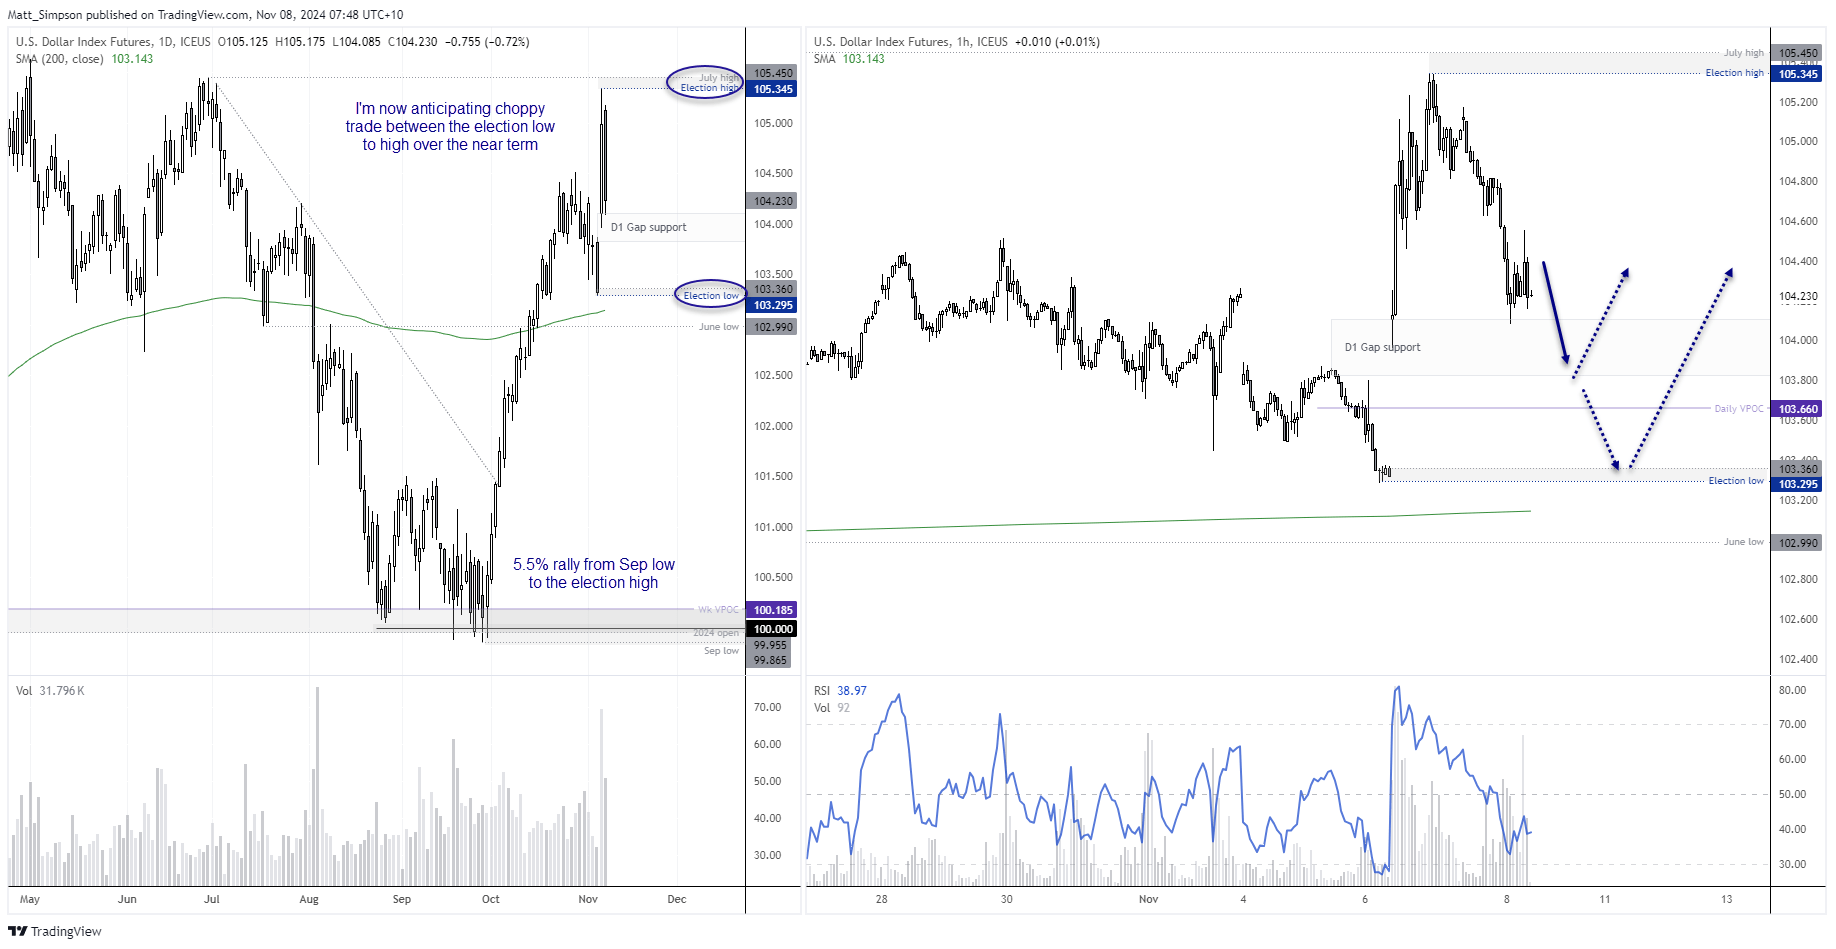
The USD index posted a 5.5% gain from the September low to the US election high, which fell just short of the July high. A 2-day bearish reversal pattern formed on the daily chart (dark-cloud cover) by Thursday’s close which, alongside the rise of 2-way volatility, suggests we’re in for a period of choppy sideways trade. If not, a pullback.
Given the Fed are less dovish and facing the prospects of an inflationary Trump administration, I suspect any pullback could be limited over the coming weeks. Potential support levels on the daily chart include the lower gap (103.80), election low (103.28), 200-day SMA (103.15) and the June low around the 103 handle.
Given we’re approaching the weekend, we could also find that trade is choppy today which means traders may be best to stick to intraday timeframes and remain nimble.
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD reversal risk builds as central bank showdown looms
USD/CAD has delivered a bullish reversal signal from established support, just as traders prepare for Fed and BoC decisions. Aggressive Canadian rate hike expectations and conflicting momentum signals make the coming session important.

EUR/USD weekly outlook: FOMC and ECB to set the tone
The current backdrop is modestly bearish. On Friday, the EUR/USD closed modestly lower, down for the third consecutive day. The pair also posted a weekly decline after staging a modest recovery attempt in the previous week. Out of the past 8 weeks, the EUR/USD has fallen on 6 occasions. There is not much supporting factors for the single currency right now. So, the upside remains capped.

USD/JPY Weekly Outlook: AI earnings could overshadow the Fed and BoJ
AI sentiment has become a major driver of US Treasury yields and USD/JPY. With Microsoft, Alphabet and Amazon reporting this week, central bank decisions may have competition for traders' attention.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.