






When will Japan Act
If the BOJ wants the Yen to weaken, they’ll need to do something soon!
Share this:

An interesting weekly report came out of Japan early in Asia today which said that Stock Investments by Foreigners fell by JPY -755B during the week of February 29th vs JPY -68.1B in the prior week. This is the largest withdrawal of funds from Japanese stocks since September 22nd, 2019. In addition, Foreign Bond Investment fell by JPY -489.7B during the week of February 29th vs JPY +656.3B a week earlier. However, the Yen is still maintaining its “flight to safety” quality, at least until the Bank of Japan decides to provide further stimulus. Market News International reported that officials signaled Japan doesn’t need additional stimulus until USD/JPY falls sharply through 105.00. The BOJ doesn’t meet again until March 18th/19th.
The US Federal Reserve (FED) cut rates on Tuesday by 50bps to 1.25%. After the GPIF was in the market during mid-February selling Yen and buying counter currencies, USD/JPY began to tank, and fear of the coronavirus began spreading around the globe. USD/JPY came off from above 112.00 to todays levels near 106.50. There is horizontal support near todays lows, but the bearish outside engulfing candle on the day (so far) isn’t showing much promise for the pair to bounce significantly. Next support is a rising weekly trendline near 105.50 dating back to mid-2016.
Source: Tradingview, City Index
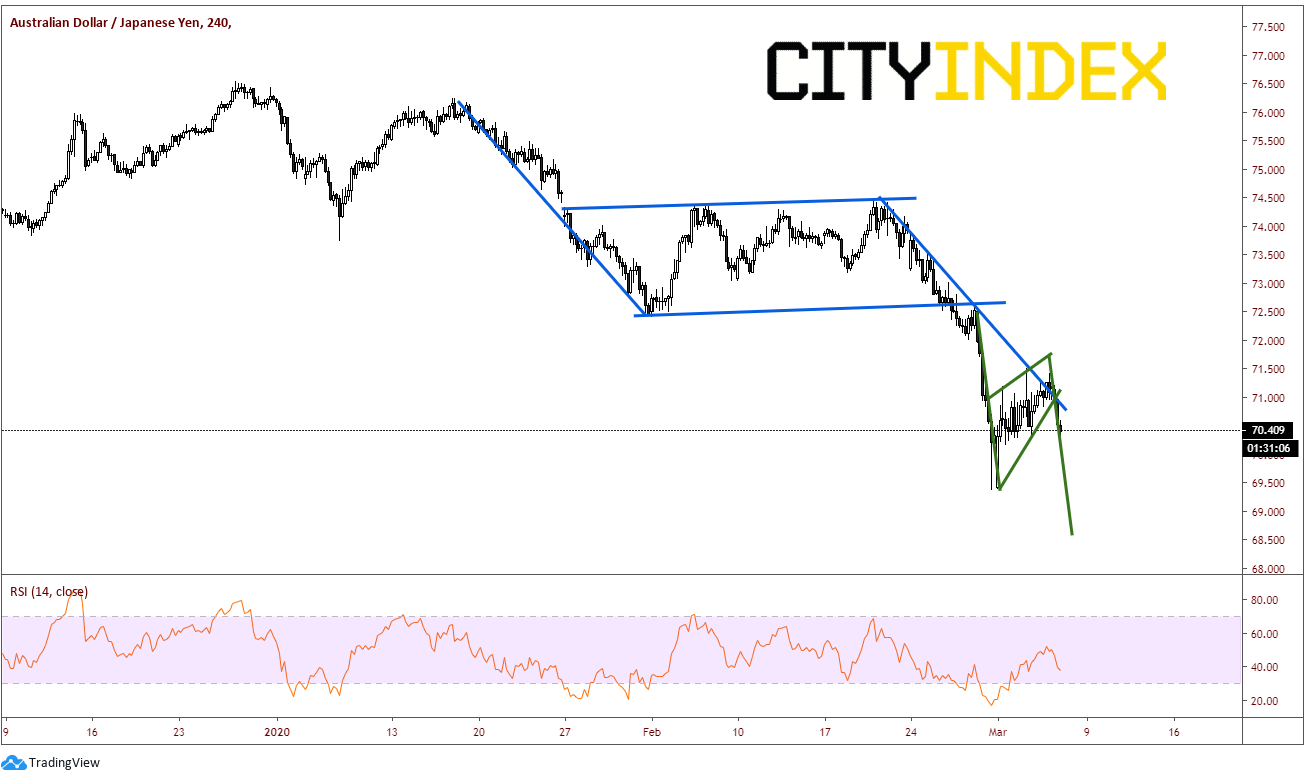
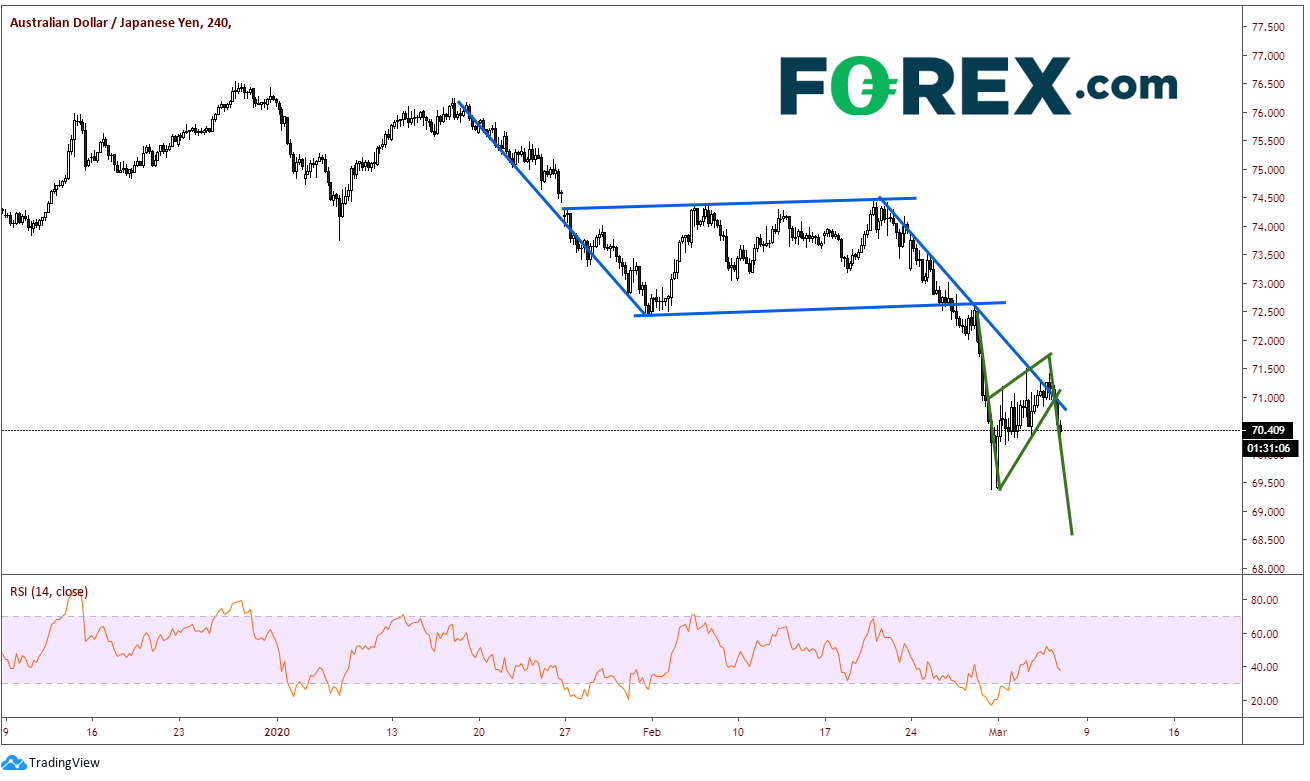
The Reserve Bank of Australia (RBA) also cut rates this week by 25bps, to an a new all-time low of 0.50%. On a 240-minute timeframe, AUD/JPY broke lower out of the flag pattern dating back to mid-January and halted near the target of 70.00. Price bounced to near 71.50, turned lower, and formed a new pennant- like formation. Today, the pair broke lower again, moving towards target near 68.60. AUD/JPY must first break the previous lows of 69.40 on its way to target.
Source: Tradingview, City Index
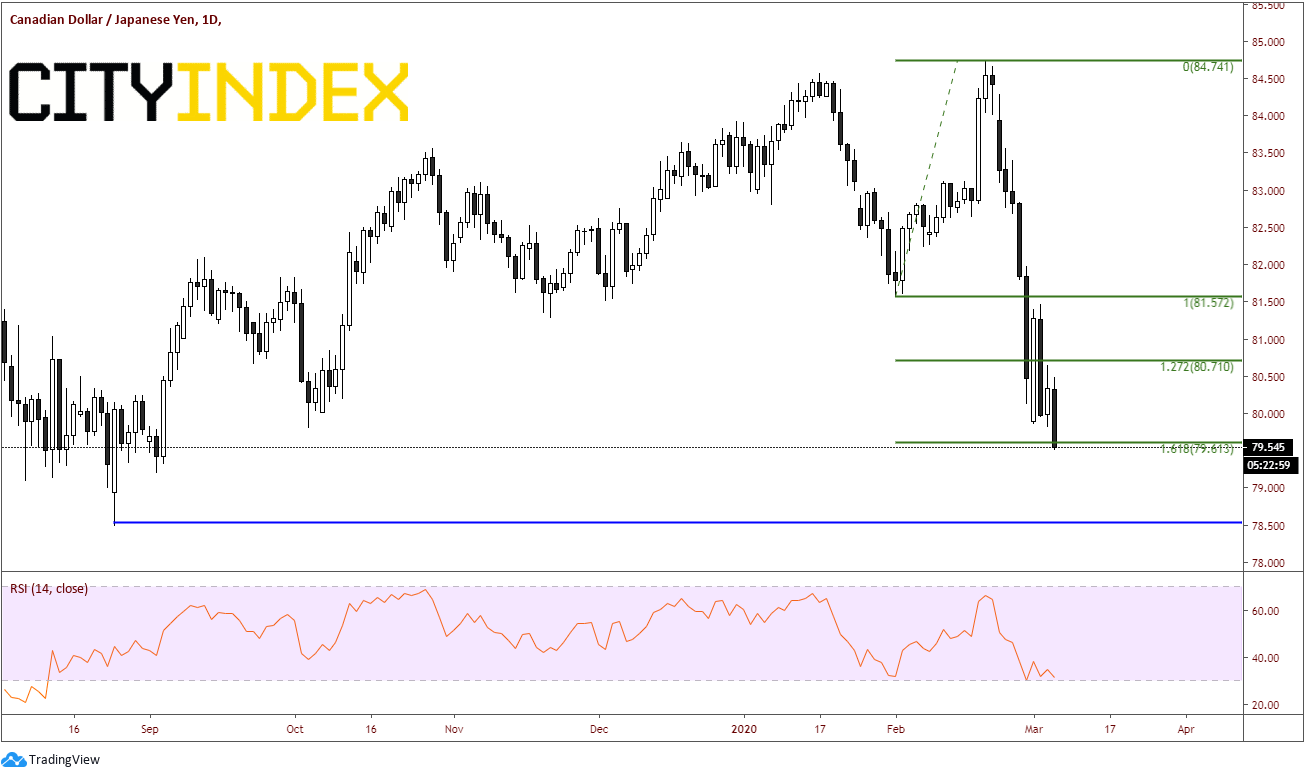
Finally, the Bank of Canada (BOC) cut rates yesterday by 50bps from 1.75% to 1.25%, and they still have additional room to move if needed. CAD/JPY as been moving lower from its highs of 84.75 in mid-February (the same time USD/JPY began moving lower). The pair has stalled at the 161.8% Fibonacci extension level from the lows on February 3rd to the highs on February 20th, neat 79.50. If price breaks through here, it could move quickly to the lows of August 26th, 2019 near 78.50. First resistance is the lows from earlier this week near 80.00.
Source: Tradingview, City Index
Although the Bank of Japan hasn’t showed signs they would provide more stimulus until their meeting in mid-March, there is always the chance they could intervene inter-meeting and provide support (as the Fed did). However, one must wonder how much more they can do, as they have been supporting the economy for over 20 years. But, if the BOJ wants the Yen to weaken, they’ll need to do something soon!
An interesting weekly report came out of Japan early in Asia today which said that Stock Investments by Foreigners fell by JPY -755B during the week of February 29th vs JPY -68.1B in the prior week. This is the largest withdrawal of funds from Japanese stocks since September 22nd, 2019. In addition, Foreign Bond Investment fell by JPY -489.7B during the week of February 29th vs JPY +656.3B a week earlier. However, the Yen is still maintaining its “flight to safety” quality, at least until the Bank of Japan decides to provide further stimulus. Market News International reported that officials signaled Japan doesn’t need additional stimulus until USD/JPY falls sharply through 105.00. The BOJ doesn’t meet again until March 18th/19th.
The US Federal Reserve (FED) cut rates on Tuesday by 50bps to 1.25%. After the GPIF was in the market during mid-February selling Yen and buying counter currencies, USD/JPY began to tank, and fear of the coronavirus began spreading around the globe. USD/JPY came off from above 112.00 to todays levels near 106.50. There is horizontal support near todays lows, but the bearish outside engulfing candle on the day (so far) isn’t showing much promise for the pair to bounce significantly. Next support is a rising weekly trendline near 105.50 dating back to mid-2016.
Source: Tradingview, FOREX.com
The Reserve Bank of Australia (RBA) also cut rates this week by 25bps, to an a new all-time low of 0.50%. On a 240-minute timeframe, AUD/JPY broke lower out of the flag pattern dating back to mid-January and halted near the target of 70.00. Price bounced to near 71.50, turned lower, and formed a new pennant- like formation. Today, the pair broke lower again, moving towards target near 68.60. AUD/JPY must first break the previous lows of 69.40 on its way to target.
Source: Tradingview, FOREX.com
Finally, the Bank of Canada (BOC) cut rates yesterday by 50bps from 1.75% to 1.25%, and they still have additional room to move if needed. CAD/JPY as been moving lower from its highs of 84.75 in mid-February (the same time USD/JPY began moving lower). The pair has stalled at the 161.8% Fibonacci extension level from the lows on February 3rd to the highs on February 20th, neat 79.50. If price breaks through here, it could move quickly to the lows of August 26th, 2019 near 78.50. First resistance is the lows from earlier this week near 80.00.
Source: Tradingview, FOREX.com
Although the Bank of Japan hasn’t showed signs they would provide more stimulus until their meeting in mid-March, there is always the chance they could intervene inter-meeting and provide support (as the Fed did). However, one must wonder how much more they can do, as they have been supporting the economy for over 20 years. But, if the BOJ wants the Yen to weaken, they’ll need to do something soon!
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


USD/CAD and USD/MXN Q4 2026 Outlook: Will the U.S. Dollar Dominate North America Again?
The final stretch of 2026 is approaching, and North America's major currencies have begun to show a shift in the strength dynamics seen earlier in the year. New expectations of a more aggressive monetary policy stance, particularly in the United States, could be significantly reshaping the outlook for the region. At the same time, this backdrop, combined with potential trade tensions across North America, may become one of the most important drivers of currency performance in the months ahead.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.