



AU inflation – a report to match Australia’s (hot) weather
There’s no escaping the fact that Australian inflation continues to point the wrong way for the RBA and consumers alike. And today’s report should quickly eradicate hopes of an RBA pause in February.
Share this:
Today’s inflation report is one that matches Australia’s weather. Hot. Choose your flavour – core CPI, trimmed mean or weighted – they’re all above expectations with no obvious signs of a ‘peak’ in sight. And that has seen any hopes of an RBA pause at their February meeting evaporate, topple the ASX 200 from its arguably overbought highs and send the Aussie higher. With higher interest likely coming for Australia, China’s reopening and higher base commodity prices, the Australian dollar could be a tough currency to bet against.
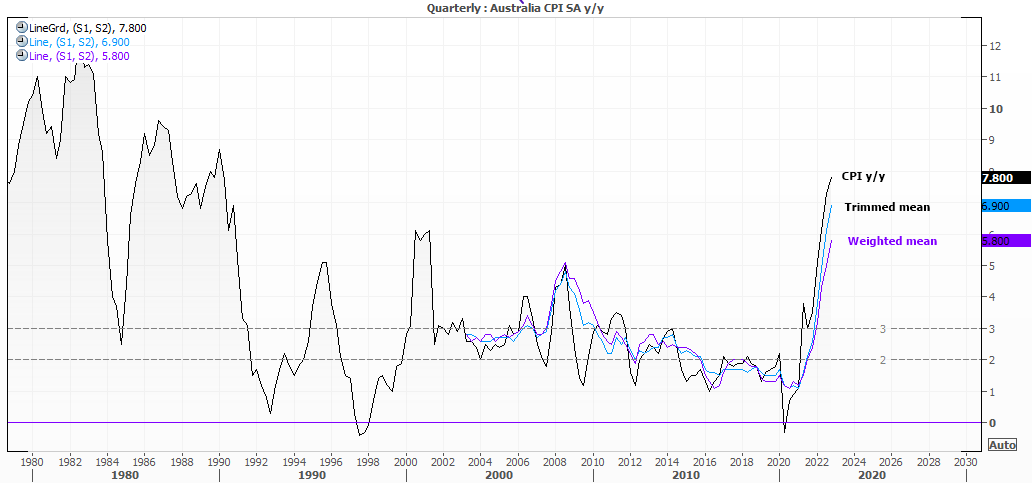
Prior to the meeting there were come hopes that inflation could soothe following NAB’s business sentiment report, which cited easing pricing pressures. But with CPI at 7.8% y/y (and the new monthly annual read at 8.2% y/y) it is hard to get excited over peak inflation just yet. For comparison, US inflation peaked in July 2022 and the Fed are still hiking interest rates. And with inflation continuing to rise in Australia it is hard to see how we’ll see a peak rate at 3.6% as markets had been expecting. The OIS curve is higher across the board following the inflation report to underscore the potential of a higher terminal rate.
Market response in a nutshell
- AUD broadly higher
- ASX 200 erased most of yesterday’s gains
- GBP/AUD touched a 15-week low
New Zealand CPI (slightly) hotter than expected
New Zealand’s Q4 inflation rose 7.2% y/y, which is slightly above 7.1% forecast yet beneath the RBNZ’s own forecast of 7.5% as of their November MPR (monetary policy report). CPI rose 1.4% q/q which is below RBNZ’s forecast of 1.7% yet above market consensus of 1.3%.
As these numbers remain high it keeps the pressure on RBNZ to tame the inflationary beast, so in all likelihood are still on track for a 50bp hike in February to take rates form 4.25% to 4.475%. As per their own projections, the RBNZ see rates peaking at 5.5% in September, although the 9-month OIS suggest a peak rate of 5.1%.
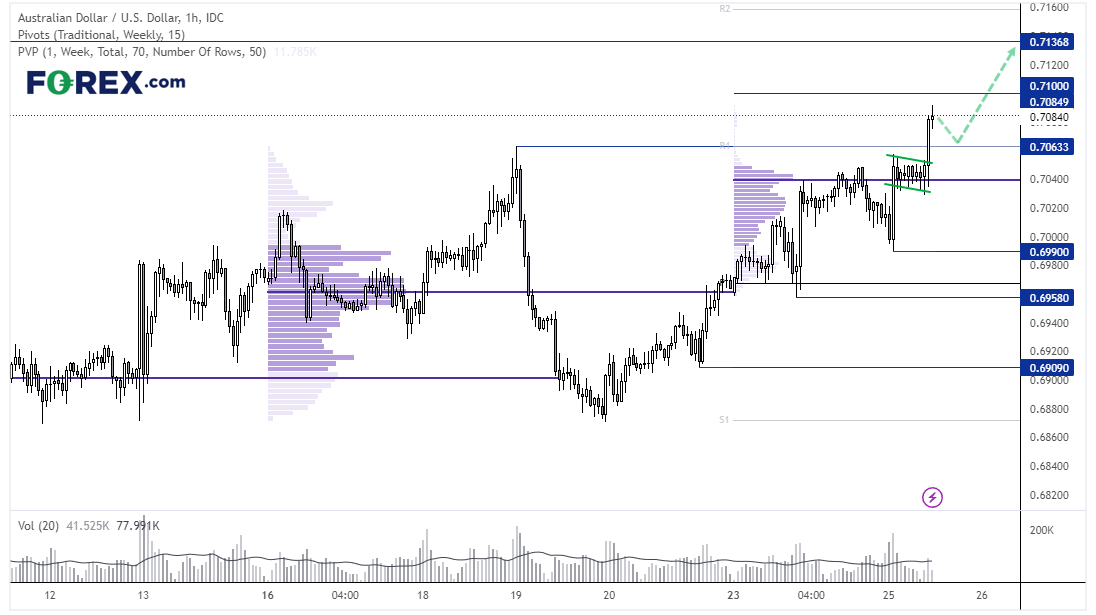
AUD/USD 1-hour chart:

The Aussie sprang higher out of its consolidation and came close to testing 0.7100 – a scenario discussed today’s client report. Yet 0.7100 is acting as resistance due to its ‘round number’ status, so perhaps we’ll see a slight pullback before its next leg higher. From here bulls could seek bullish setups above the 0.7063 high in anticipation of potential break above 0.7100.
AUD/NZD daily chart:


It has been a tail of two inflation reports, and its conclusion is perfectly captured on AUD/NZD. With AU inflation rising and NZ inflation below RBNZ’s own forecasts, AUD/NZD has turned higher. At the time of writing the cross is testing last week’s highs and trying to close above the 100 and 200-day EMA’s. RSI (14) is holding above 50 to show positive momentum and confirming the rise higher on the price action. Next up could be the 1.1000 - 1.1045, a break above which brings 1.1200 into focus for bulls.
ASX 200 daily chart:
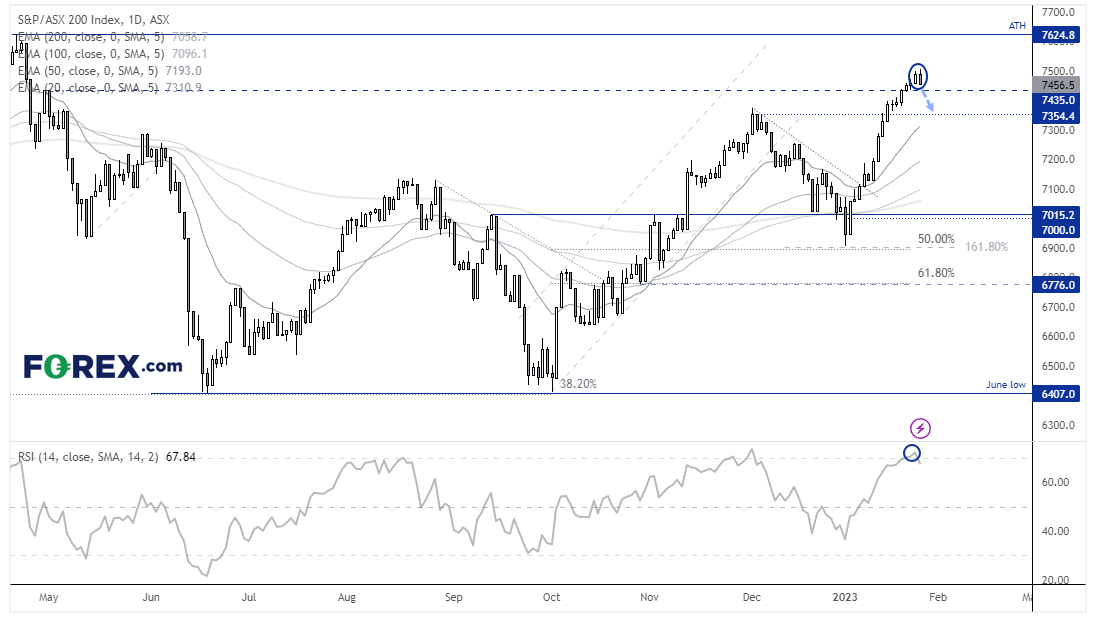
The ASX 20 has erased all of yesterday’s gains, and today’s inflation report could be the trigger which prompts an arguably needed correction. It’s had a great start to the year and has seen little in the way of a pullback. Rising trading volumes have complemented its latest rally so we do not see an overall threat to the trend, but we may see a 3-wave countertrend move. A break below 7435 would be a good first step to confirming such a pullback, with a break below 7354 suggesting a deeper correction.

Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.