



S&P 500 forecast: Investors weigh hawkish Fed against weak oil prices
Following the sharp post-Federal Reserve sell-off, global equity markets staged a recovery overnight. US futures moved higher alongside stronger European indices, before coming off their highs. Continued dollar strength maintained pressure on precious metals and several major currencies.
Share this:
Following the sharp post-Federal Reserve sell-off, global equity markets staged a recovery overnight. US futures moved higher alongside stronger European indices, before coming off their highs. Continued dollar strength maintained pressure on precious metals and several major currencies. Our S&P 500 forecast has turned a little more cautious now. Investors are weighing enthusiasm around artificial intelligence-led growth and falling energy prices against a Federal Reserve that has clearly adopted a firmer policy stance. While policymakers remain divided over the need for further tightening this year, the latest meeting represented a notable departure from the more accommodative tone seen previously.
S&P 500 forecast: Crude oil weakness limit downside but correction risks increase
The recent collapse in oil prices offers an important offset. Should lower energy costs continue to filter through to inflation data, policymakers may ultimately find sufficient justification to keep rates unchanged for an extended period rather than resume tightening. Had it not been for the sharply lower oil prices, yesterday’s FOMC announcement would have triggered a much bigger slide in equity markets.
What is almost certain to happen now is that markets will become increasingly data-dependent once again. For now, equity bulls maintain some control. However, with valuations still elevated and a lack of obvious near-term catalysts, the prospect of profit-taking or a modest correction has become more plausible following the Fed’s hawkish pivot.
Warsh triggers hawkish repricing of US rates
Federal Reserve Chair Kevin Warsh’s first meeting at the helm delivered a message that markets interpreted as distinctly hawkish. The immediate consequence was a stronger US dollar and a period of weakness across risk assets before sentiment stabilised overnight.
The key driver of the reaction was the Fed’s renewed emphasis on inflation risks, reinforced by a more hawkish set of rate projections. Nine of the eighteen policymakers now expect at least one additional rate increase before year-end. The Fed is basically signalling a readiness to respond should inflationary pressures re-emerge.
With both the policy statement and subsequent press conference offering limited forward guidance, incoming economic releases are likely to carry greater weight in shaping market expectations over the months ahead.
My view remains that inflation should moderate gradually over the coming months, and this might allow the Fed to maintain current policy settings rather than implement fresh tightening.
Markets are currently pricing approximately 30 to 35 basis points of tightening this year, compared with less than 20 basis points prior to the latest FOMC meeting. Whether those expectations prove justified will depend heavily on forthcoming inflation data.
Europe holds steady
Meanwhile, European markets had a slightly more constructive session, even if gains have moderated from their intraday highs. Several major indices remain close to record territory, supported by a combination of softer energy prices, reasonably resilient economic data and growing confidence that central banks are approaching the end of their recent inflation-driven tightening bias.
While concerns over global growth have not disappeared entirely, investors appear increasingly willing to re-engage with risk assets. Continental European markets, in particular, continue to benefit from relatively attractive valuations compared with some international peers.
Provided energy prices remain contained and economic conditions avoid a meaningful deterioration, the region’s equity markets should continue to attract investor interest.
Falling crude keeps risk appetite intact
One of the most significant drivers behind the recent improvement in market sentiment has been the sharp decline in oil prices. Crude futures extended their losses for a sixth consecutive session, helping to reinforce expectations that inflationary pressures may continue to ease in the months ahead.
For investors, cheaper energy offers a double benefit. Lower input costs support corporate profitability, while reduced inflation risks lessen the likelihood of additional monetary tightening from major central banks. As a result, declining oil prices have become an increasingly important pillar supporting the broader equity rally.
Technical S&P 500 forecast
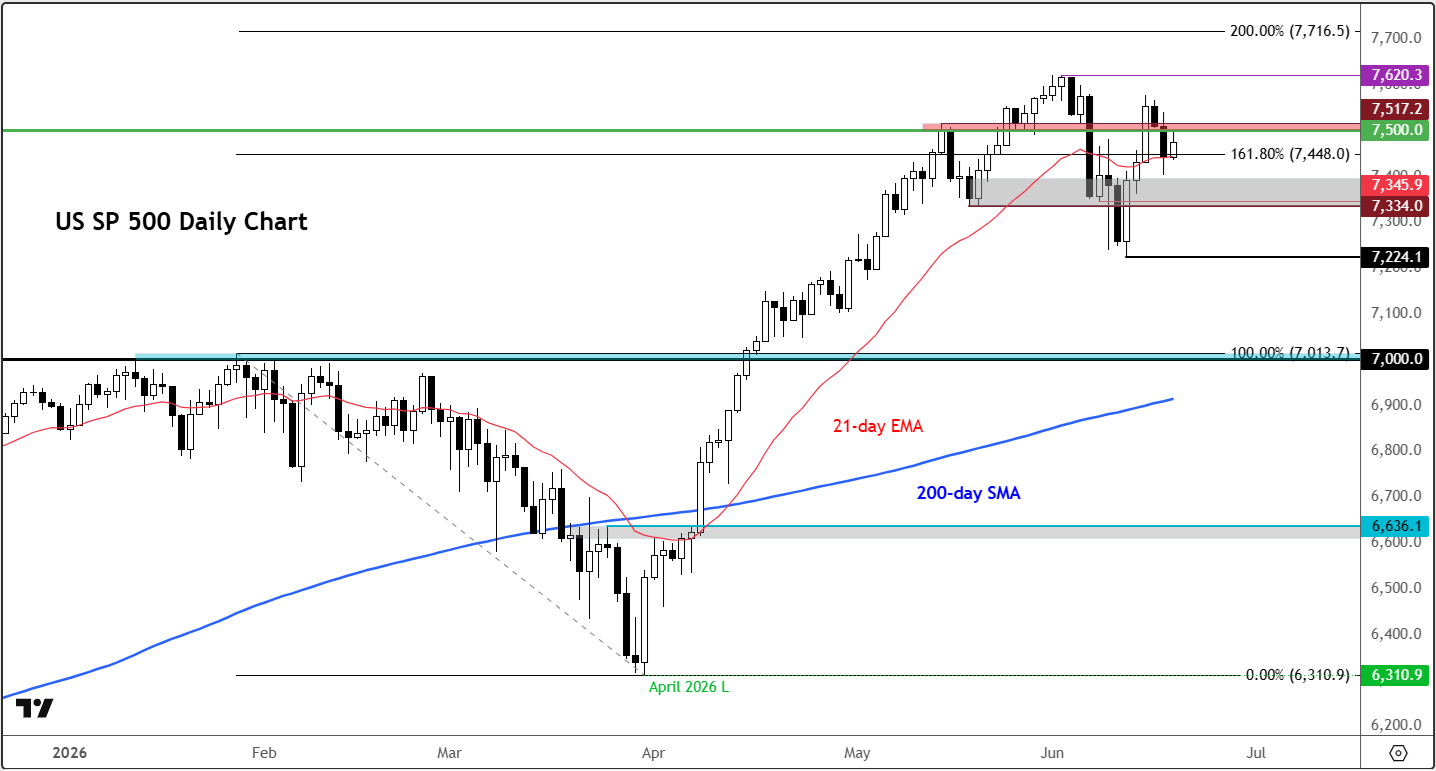
The rebound following the FOMC decision is encouraging for bulls, although our SPX500 chart, which tracks the underlying S&P 500 futures, now faces an important technical hurdle between 7,500 and 7,517. This zone previously acted as support and may now serve as resistance following the bearish reversal seen after the Fed meeting.
At present, the uptrend remains intact. However, confirmation of renewed weakness would require a decisive move back below yesterday’s low at least. Such a break could encourage a deeper pullback and shift short-term S&P 500 forecast in favour of sellers, in particular if 7334 also breaks.
A break beneath this area would materially weaken the technical outlook and expose the market to a move towards liquidity resting below last week’s low near 7,224. Should selling pressure intensify further, the longer-term support zone around 7,000 cannot be dismissed as a potential downside destination.
On the upside, a sustained break above the 7,500-7,517 resistance band would likely open the door for a retest of recent highs circa 7620.
Beyond that, the next major upside target is the 200 per cent extension of the January-to-March decline, which comes in around 7,716 and remains the key bullish objective should momentum reaccelerate.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.