



US Open: Stocks rise cautiously ahead of a key week for risk events
Stocks head cautiously higher ahead of a busy week which sees Fed Chair Powell testify before Congress and Friday's NFP.
Share this:

US futures
Dow futures +0.17% at 33450
S&P futures +0.3% at 4057
Nasdaq futures +0.5% at 12355
In Europe
FTSE -0.57% at 7930
Dax 0.2% at 15670
- Stocks rise in March after weak February
- Tesla rises after more price cuts
- EURUSD holds steady after weak retail sales
- Oil falls after weak China GDP projection
March sees a strong start after a weak February
US stocks pointing to mild gains on the open amid a cautious market mood as investors look ahead to a big week for risk events. This week sees Federal Reserve Chair Jerome Powell testifies before Congress and the February non-farm payroll report. Together these events could set expectations for future rate hikes and set the tone in the market for the next few weeks until the US FOMC meeting.
After weakness across February as the markets repositioned for more rate hikes for longer, there now finally seems to be an acceptance that the Fed could need to continue acting aggressively to bring down stubbornly high inflation. The S&P500 lost 2.6% in February and trades 1.9% higher in March so far, a typically strong month for US equities.
Today US factory orders are due to be released and are expected to show that orders fell -1.8% in January after rising 1.8% in December.
Corporate news
Tesla rises pre-market after the EV maker announce more price cuts to some of its premium models. The Model S price will be cut by 4% and the more expensive Model X by 9%.
Apple rises pre-market after Goldman Sachs initiated coverage on the iPhone maker with a buy rating, saying that it could rally by more than 30% on the back of its services business.
Where next for the S&P500?
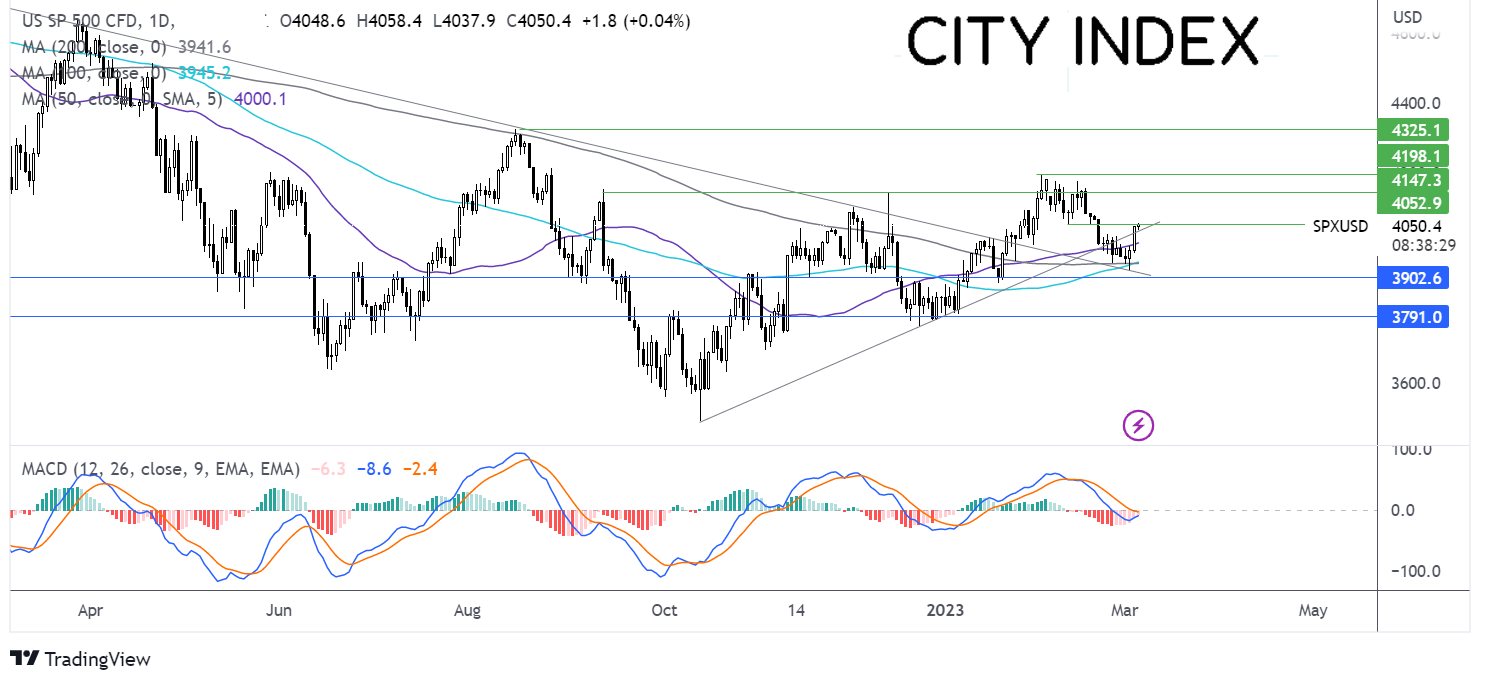
The S&P500 closed above the 200 sma on Thursday and extended gains above the 100 sma and the rising trend line resistance in a bullish signal. This combined with the receding bearish bias on the MACD keeps buyers hopeful of further gains. Buyers are testing resistance at 4050 the Friday 10 low, with a rise above here brining 4100 the round number, and 4150, the December high into play. On the flip side, a fall below the rising trendline resistance turned support could see the price test the 200 sma at 3940. A break below 3920 creates a lower low.

FX markets – USD steady, AUD falls
The USD is holding steady after losses last week in cautious trade ahead of a big week for the USD. Fed Chair Powell and US jobs data are likely to set the direction of the USD for the coming weeks until the March FOMC meeting.
EUR/USD is clinging to gains just below 1.0650 after eurozone retail sales rose by less than expected in January to 0.3% MoM, up from -2.7%. Expectations had been for a rebound to 1%. Stubbornly high prices continue to impact the consumer. Eurozone Sentix investor confidence also fell by more than expected dropping to -11.1 in March, down from -8.0
AUD/USD is falling, dragged lower by the Chinese yuan after China’s GDP forecast disappointed at 5%, below the 5.3% expected. Attention will now turn to the RBA meeting, where the central bank is expected to raise rates for a 10th straight meeting. Hints that the RBA could hike again in Q2 could lift the AUD.
EUR/USD +19% at 1.0615
AUD/USD -0.64% at 0.6725
Oil drops on China growth concerns
Oil prices fooling at the start of the week, reversing games from the previous week amid the ongoing tug-of-war between China reopening and fed jitters.
Upbeat data from China, the world’s largest importer of oil, has helped oil prices climb higher over the past four weeks. However, over the weekend, China set a lower-than-expected GDP projection of 5%, below the 5.3% expected. Weaker expected growth in China hurts the oil demand outlook.
Today’s drop in oil prices comes after oil jumped on Friday on rumors that the UAE was considering leaving OPEC.
Looking ahead, attention will be on Fed Chair Jerome Powell’s testimony, where he could provide clues on the future path of rate hikes. Higher interest rates mean slower growth which could hurt the oil demand in the US, the world’s largest oil consumer.
WTI crude trades -1.4% at $77.50
Brent trades at +0.45% at $84.43
Looking ahead
15:00 US factory orders
15:00 CAD Ivey purchasing PMI
US futures
Dow futures +0.17% at 33450
S&P futures +0.3% at 4057
Nasdaq futures +0.5% at 12355
In Europe
FTSE -0.57% at 7930
Dax 0.2% at 15670
- Stocks rise in March after weak February
- Tesla rises after more price cuts
- EURUSD holds steady after weak retail sales
- Oil falls after weak China GDP projection
Learn more about trading indices
March sees a strong start after a weak February
US stocks pointing to mild gains on the open amid a cautious market mood as investors look ahead to a big week for risk events. This week sees Federal Reserve Chair Jerome Powell testifies before Congress and the February non-farm payroll report. Together these events could set expectations for future rate hikes and set the tone in the market for the next few weeks until the US FOMC meeting.
After weakness across February as the markets repositioned for more rate hikes for longer, there now finally seems to be an acceptance that the Fed could need to continue acting aggressively to bring down stubbornly high inflation. The S&P500 lost 2.6% in February and trades 1.9% higher in March so far, a typically strong month for US equities.
Today US factory orders are due to be released and are expected to show that orders fell -1.8% in January after rising 1.8% in December.
Corporate news
Tesla rises pre-market after the EV maker announce more price cuts to some of its premium models. The Model S price will be cut by 4% and the more expensive Model X by 9%.
Apple rises pre-market after Goldman Sachs initiated coverage on the iPhone maker with a buy rating, saying that it could rally by more than 30% on the back of its services business.
Where next for the S&P500?
The S&P500 closed above the 200 sma on Thursday and extended gains above the 100 sma and the rising trend line resistance in a bullish signal. This combined with the receding bearish bias on the MACD keeps buyers hopeful of further gains. Buyers are testing resistance at 4050 the Friday 10 low, with a rise above here brining 4100 the round number, and 4150, the December high into play. On the flip side, a fall below the rising trendline resistance turned support could see the price test the 200 sma at 3940. A break below 3920 creates a lower low.
FX markets – USD steady, AUD falls
The USD is holding steady after losses last week in cautious trade ahead of a big week for the USD. Fed Chair Powell and US jobs data are likely to set the direction of the USD for the coming weeks until the March FOMC meeting.
EUR/USD is clinging to gains just below 1.0650 after eurozone retail sales rose by less than expected in January to 0.3% MoM, up from -2.7%. Expectations had been for a rebound to 1%. Stubbornly high prices continue to impact the consumer. Eurozone Sentix investor confidence also fell by more than expected dropping to -11.1 in March, down from -8.0
AUD/USD is falling, dragged lower by the Chinese yuan after China’s GDP forecast disappointed at 5%, below the 5.3% expected. Attention will now turn to the RBA meeting, where the central bank is expected to raise rates for a 10th straight meeting. Hints that the RBA could hike again in Q2 could lift the AUD.
EUR/USD +19% at 1.0615
AUD/USD -0.64% at 0.6725
Oil drops on China growth concerns
Oil prices fooling at the start of the week, reversing games from the previous week amid the ongoing tug-of-war between China reopening and fed jitters.
Upbeat data from China, the world’s largest importer of oil, has helped oil prices climb higher over the past four weeks. However, over the weekend, China set a lower-than-expected GDP projection of 5%, below the 5.3% expected. Weaker expected growth in China hurts the oil demand outlook.
Today’s drop in oil prices comes after oil jumped on Friday on rumors that the UAE was considering leaving OPEC.
Looking ahead, attention will be on Fed Chair Jerome Powell’s testimony, where he could provide clues on the future path of rate hikes. Higher interest rates mean slower growth which could hurt the oil demand in the US, the world’s largest oil consumer.
WTI crude trades -1.4% at $77.50
Brent trades at +0.45% at $84.43
Learn more about trading oil here.
Looking ahead
15:00 US factory orders
15:00 CAD Ivey purchasing PMI0
Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.