



FOMC Minutes Dissension in the Ranks Raises Stakes for Powell at Jackson Hole
See why we may see more dissents from Fed officials moving forward...
Share this:

As my colleague Fiona Cincotta noted earlier today,“[g]iven the outdated nature of the minutes in light of the recent US - Sino trade dispute escalation and global recession fears, the reaction to the minutes could be limited.”
Interestingly, while the international economic outlook has worsened due to new tariffs and an outright contraction in German GDP, US data released since last month’s Fed meeting has generally improved. Since then, we’ve seen a solid (if unspectacular) Non-Farm Payrolls report, a hotter-than-expected CPI report, and a strong retail sales reading. More to the point, Fed speakers in the intervening weeks (Bullard and Daly) haven’t implied any change in their outlooks since last month’s “mid-cycle adjustment.”
The just-released minutes confirmed the Fed’s generally optimistic domestic/pessimistic international outlook. Top headlines from the minutes follow [emphasis mine]:
- A NUMBER OF FED OFFICIALS STRESSED NEED FOR FED FLEXIBILITY
- A FEW POLICYMAKERS EXPRESSED CONCERN OF 3M/10Y YIELD CURVE INVERSION
- SEVERAL SAID UNCERTAINTIES REMAINED ABOUT EFFICACY OF QE
- SEVERAL FAVORED MAINTAINING RATES UNCHANGED
- MOST VIEWED A 25 BP CUT AS A … MID-CYCLE ADJUSTMENT
- A COUPLE POLICYMAKERS WOULD HAVE PREFERRED A 50 BP CUT TO ADDRESS LOW INFLATION
- THOSE WHO FAVORED CUT POINTED TO DECELERATING ECONOMY, ELEVATED RISKS ON GLOBAL ECONOMY AND INFLATION
- PARTICIPANTS SAID FORWARD GUIDANCE AND QE MIGHT NOT BE ENOUGH TO ELIMINATE PROTRACTED RISKS AT LOWER BOUND
The divergent viewpoints (“several” favored unchanged rates, “a couple” would have preferred a 50bp cut) suggests that we may continue to see dissents in response to future Fed decisions. Therefore, it will be particularly important to watch comments from central bank’s leadership (Powell and Clarida) for the most accurate signals on future policy.
Market Reaction
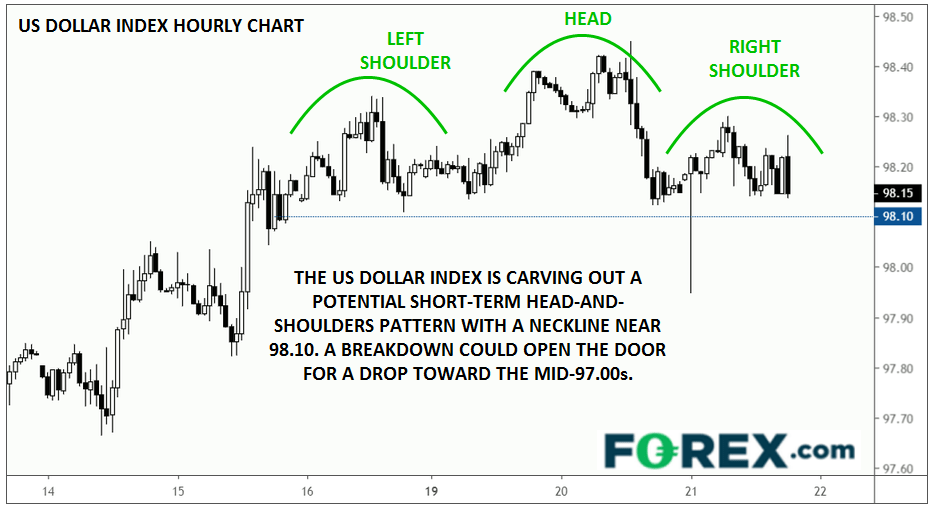
To call the market’s reaction to the FOMC minutes lackluster would be an understatement. The US dollar ticked about 5 pips higher against its rivals before reversing and trading about 5 pips below pre-Fed levels as we go to press – as the chart below shows, rates are showing a potential short-term head-and-shoulders topping pattern. Gold prices bumped up a couple bucks to $1506 while major US indices and Treasury yields are essentially unchanged.
All eyes now turn to Fed Chairman Powell’s big speech on "Challenges for Monetary Policy" at Jackson Hole Friday morning.
Source: TradingView, FOREX.com




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Outlook: Historic yield squeeze leaves Aussie bears in control
Australian bond yields have fallen below their US equivalents as the Fed's hawkish repricing gathers momentum. With the Aussie weakening broadly, technical signals suggest sellers remain in control.
GBP/USD approaches breaking point as US yields surge
A historic repricing of US interest rate expectations has propelled the dollar higher, leaving GBP/USD testing a crucial support level ahead of UK GDP.
EUR/USD, DXY, Silver Price Outlook: Bullish Rebounds on Hold?
EUR/USD, DXY, Silver Price Outlook: Bullish rebounds across currency markets, precious metals, and risk assets are facing renewed pressure as U.S. CPI comes in above expectations and oil-tanker attacks persist in the Strait of Hormuz.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.