



Nasdaq reeling after big reversal ahead of US tech earnings
Sentiment is quite downbeat following Thursday’s reversal in risk appetite ahead of earnings from Alphabet, Microsoft, Meta, Apple and Amazon
Share this:
We have seen some big moves across the financial markets in the aftermath of hawkish commentary from the Fed with traders dumping equities, precious metals and commodity currencies. Jerome Powell has more or less now confirmed that the Fed will hike by 50-bps at their next meeting. But there’s even talk of 75 basis point hikes in the upcoming meetings. This is what is spooking equity market bulls, especially on US technology sector where the dividend yields are low and becoming increasingly less attractive as government bond yields continue to rise. The Fed’s hawkishness has also more than outweighed any positive vibes that came our way earlier in the week from Europe, where the Ukraine conflict is no longer having the same impact on asset prices as it did when the invasion first started while there’s also been some optimism ahead of the French election on Sunday, with far-right Le Pen falling behind in the polls.
So, as we look ahead to the US session and weekend, sentiment is quite downbeat following Thursday’s reversal in risk appetite. Powell’s hawkish remarks have been echoed by several other FOMC members such as Daly and Bullard, with the latter saying the Fed is behind the curve. We won’t be hearing much from Fed speakers in the next couple of weeks as we enter the blackout period ahead of the central banks May 4 meeting. But the damage has already been done and the massage has been loud and clear: US Federal Funds Rate will most likely rise by 50 basis points at that meeting.
Investors’ focus will remain on inflation and company earnings. Should we see further signs that price pressures are not weakening, this will likely keep technology stocks under pressure, especially as expectations are downbeat ahead of the Big Tech earnings. Alphabet, Microsoft, Meta, Apple and Amazon are all due to report their quarterly results in the week ahead. Inflation and supple chain headwinds are among the major themes likely to dominate the agenda this earnings season. So, be prepared for some disappointment.
If you want to learn more about what to expect from this earnings season, read my stock-focused-analyst colleague Joshua Warner’s preview HERE. Note that some of these tech names are among the most shorted stocks, with Amazon topping the list this week, according to City Index’s UK client data.
Meanwhile, the major US induces are continuing to look bearish, especially the Nasdaq 100 and Russell 2000. Rising rate hike expectations and continued bearish-looking price action on the major indices suggests we may see more selling pressure in the weeks ahead.
Thursday’s sell-off has pushed the Nasdaq below last week’s low, which means the index is now down for the third consecutive week, reversing a big chunk of the rally that started in mid-March:
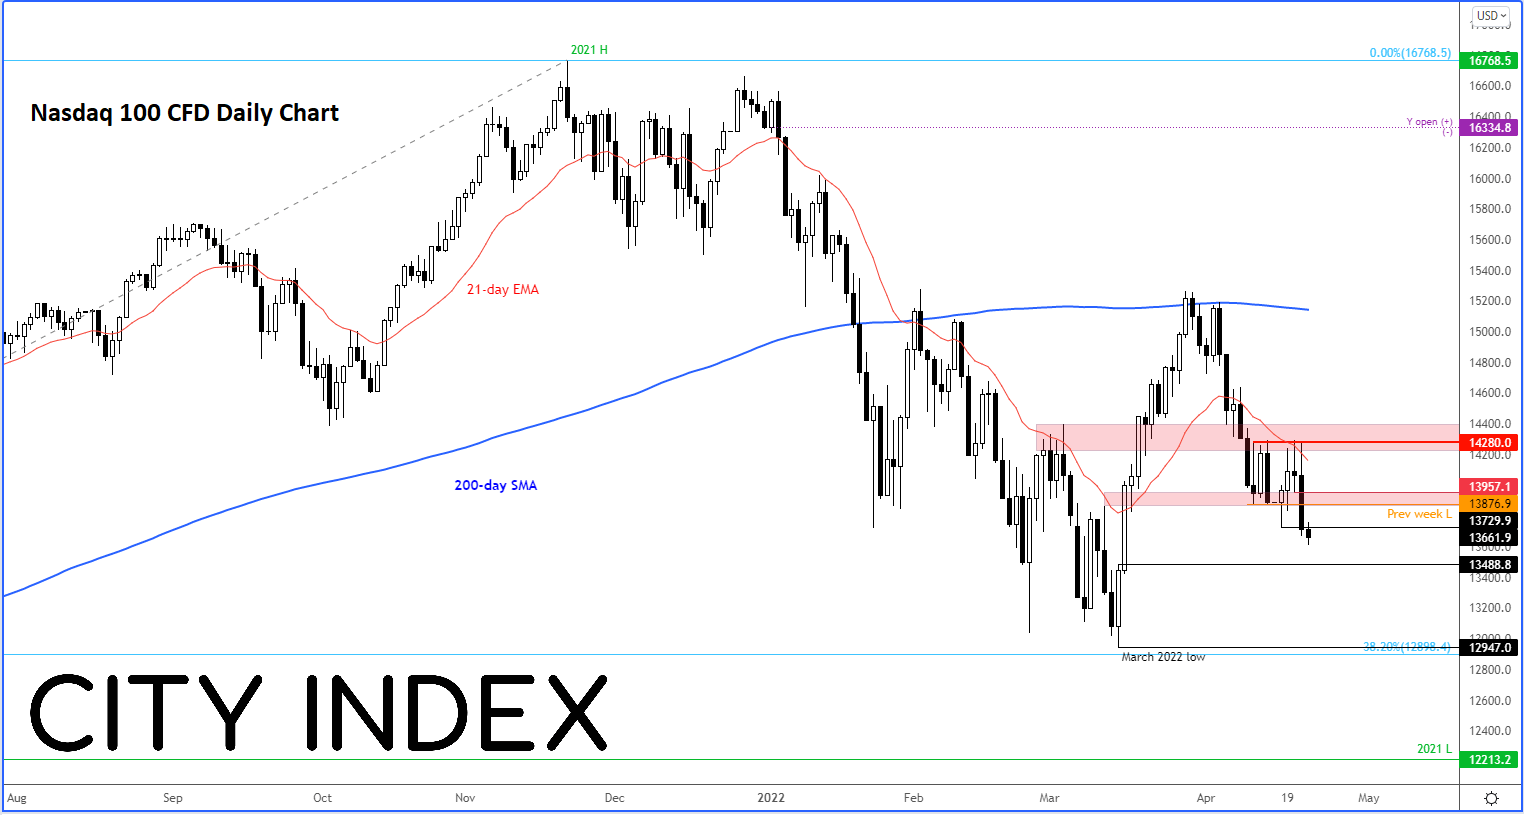
Unless Thursday’s high breaks in the coming days, the path of least resistance would thus remain to the downside. The bears may step in on any short-term strength that we might see shortly after the US open. Clearly, there are many traders that feel left out after Thursday’s sudden drop, so they will be keen to get on board as well on any short-term strength today.
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
We have seen some big moves across the financial markets in the aftermath of hawkish commentary from the Fed with traders dumping equities, precious metals and commodity currencies. Jerome Powell has more or less now confirmed that the Fed will hike by 50-bps at their next meeting. But there’s even talk of 75 basis point hikes in the upcoming meetings. This is what is spooking equity market bulls, especially on US technology sector where the dividend yields are low and becoming increasingly less attractive as government bond yields continue to rise. The Fed’s hawkishness has also more than outweighed any positive vibes that came our way earlier in the week from Europe, where the Ukraine conflict is no longer having the same impact on asset prices as it did when the invasion first started while there’s also been some optimism ahead of the French election on Sunday, with far-right Le Pen falling behind in the polls.
So, as we look ahead to the US session and weekend, sentiment is quite downbeat following Thursday’s reversal in risk appetite. Powell’s hawkish remarks have been echoed by several other FOMC members such as Daly and Bullard, with the latter saying the Fed is behind the curve. We won’t be hearing much from Fed speakers in the next couple of weeks as we enter the blackout period ahead of the central banks May 4 meeting. But the damage has already been done and the massage has been loud and clear: US Federal Funds Rate will most likely rise by 50 basis points at that meeting.
Investors’ focus will remain on inflation and company earnings. Should we see further signs that price pressures are not weakening, this will likely keep technology stocks under pressure, especially as expectations are downbeat ahead of the Big Tech earnings. Alphabet, Microsoft, Meta, Apple and Amazon are all due to report their quarterly results in the week ahead. Inflation and supple chain headwinds are among the major themes likely to dominate the agenda this earnings season. So, be prepared for some disappointment.
If you want to learn more about what to expect from this earnings season, read my stock-focused-analyst colleague Joshua Warner’s preview HERE. Note that some of these tech names are among the most shorted stocks, with Amazon topping the list this week, according to City Index’s UK client data.
Meanwhile, the major US induces are continuing to look bearish, especially the Nasdaq 100 and Russell 2000. Rising rate hike expectations and continued bearish-looking price action on the major indices suggests we may see more selling pressure in the weeks ahead.
Thursday’s sell-off has pushed the Nasdaq below last week’s low, which means the index is now down for the third consecutive week, reversing a big chunk of the rally that started in mid-March:
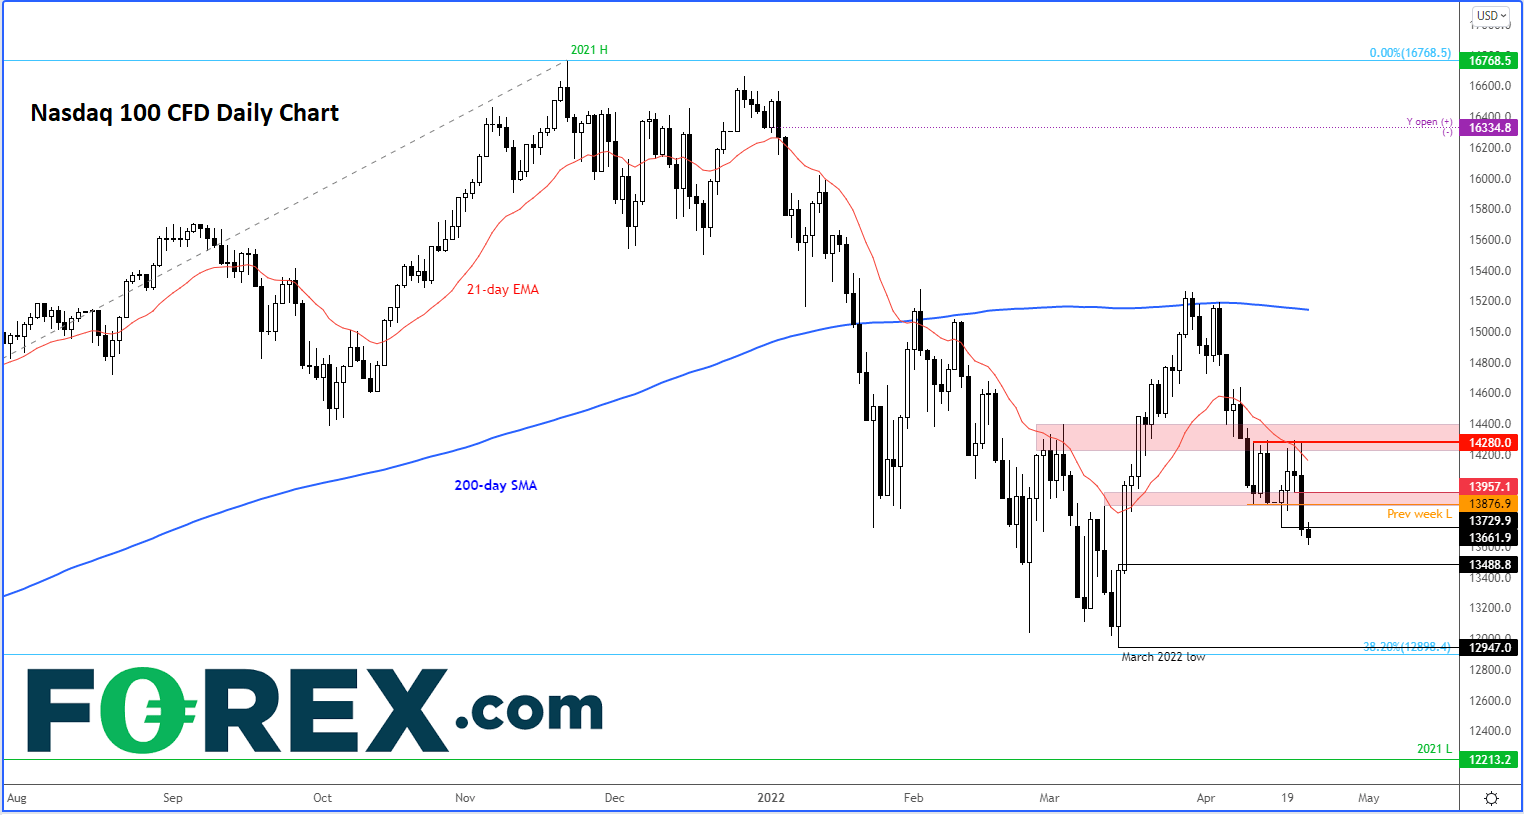
Unless Thursday’s high breaks in the coming days, the path of least resistance would thus remain to the downside. The bears may step in on any short-term strength that we might see shortly after the US open. Clearly, there are many traders that feel left out after Thursday’s sudden drop, so they will be keen to get on board as well on any short-term strength today.
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Outlook: Potential to Bounce Sits on a Knife Edge
ASX 200 bounce prospects remain on a knife edge as oversold technicals clash with weak financials, commodity pressures and global risk aversion.

US dollar rally loses yield support as Nvidia looms
US yields are retreating, but the dollar isn't following. With risk aversion potentially keeping it supported, Nvidia's results could determine whether emerging reversal signals in AUD/USD and EUR/USD develop further.


GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.