



NFP in focus as Q4 kicks off
Next week is set to be another interesting one as the fourth quarter officially gets underway.
Share this:

A rather volatile week is drawing to a close and it has been a very interesting one indeed. The dollar started the week on the back foot and it fell initially in the immediate aftermath of the Fed’s rate hike in mid-week, which had been widely anticipated. However, the greenback then staged a sharp recovery on Thursday, gaining significant ground against the euro, pound, yen and some commodity currencies. The Canadian dollar was an exception, which gained ground as Brent crude prices broke to a fresh four-year high after the OPEC+ refused to increase their crude production levels despite a plea from the US President Donald Trump last week. Positive Canadian GDP data on Friday gave the Loonie another shot in the arm, leading to a nice breakout for the CAD/JPY cross. Meanwhile the euro was shot down along with Italian banks, leading to a sharp drop in the EUR/USD exchange rate and European indices, most notably the FTSE MIB. This was in response to news that the Italian government had agreed to set a higher-than-expected budget deficit target of 2.4% of GDP for the next three years. But as we go to press, the euro and pound were trying to make a comeback with the cable bouncing off 1.30 long-term support. Gold also enjoyed a rebound amid short covering ahead of the weekend, but remained below that pivotal $1205/$1215 area, which needs to break in order to signal the a low has been formed.
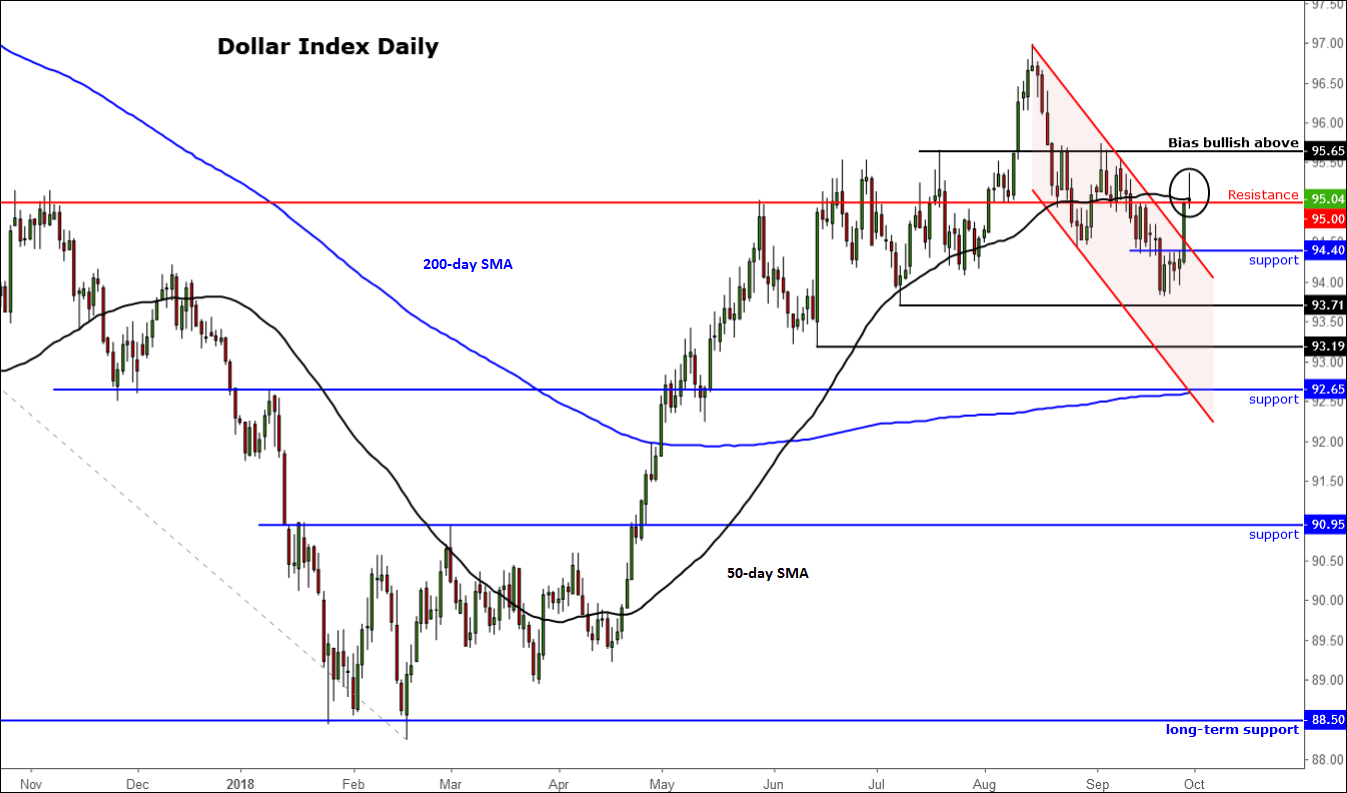
Next week is set to be another interesting one as the fourth quarter officially gets underway. Will the dollar rise further – if so, against which currencies? How about the still-buoyant US stock markets – will the rising government bond yields unnerve investors on Wall Street? Traders will have time over the weekend to re-assess the Federal Reserve’s latest policy decision and what the outlook holds for US monetary policy given the risks arising from the mid-term elections to trade disputes, among other things. So far, the market has deemed the Fed to have been overall moderately hawkish than had been expected. My colleague Matt Weller summarised it very neatly: “though the central bank removed the phrasing about monetary policy remaining accommodative from its statement, Fed Chair Powell was at pains to emphasize that that change was more procedural than anything. At the end of the day, the Federal Reserve is the only major central bank engaging in sustained interest rate increases, and until that dynamic starts to change, the greenback could maintain its recent strength.”
Could a run of bad US data or significantly positive news elsewhere change that view? Well, time will tell. Heading into next week, the first major piece of data will be released on Sunday actually and it will be from China: manufacturing PMI. After the introduction of the tariffs, let’s see how this has impacted Chinese factories, if at all. UK and US manufacturing PMIs will be released on Monday, when we also have German retail sales. Tuesday is the RBA rate decision day – no hike expected but let’s see if there are any hints about a potential tightening in the foreseeable future. If so, the Aussie could rally, otherwise, it may well extend its decline from the top of its bearish channel. By Wednesday, we will have had all three PMIs from the UK economy, with services being the key one to watch. With the latest setback in Brexit negotiations, it is likely that businesses may have erred on the side of caution in September and so the purchasing managers are likely to report slightly weaker numbers. Meanwhile, two of the biggest pre-NFP leading indicators will also be released on Wednesday: the ADP private sector payrolls report and the employment component of the non-manufacturing sector from ISM. Thursday will be a non-event, potentially the calm before the storm – the proverbial storm being the US non-farm payrolls report on Friday. With jobs at full throttle and inflation on the rise, wages need to catch up now. If average hourly earnings show a big surprise then this should be dollar-positive. Otherwise with most of the positivity almost priced in for the dollar, we could see currencies where the central banks are turning hawkish bounce back. One of those is the Canadian dollar, which has already been on the rise. It could rise further should Friday’s Canadian employment report show a positive surprise.
Source: TradingView.com and FOREX.com. Please note, this product is not available to US clients
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.
EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.


Forex & Gold Outlook: Dollar Dominates, Crosses Diverge
The US dollar rally gathers momentum as forex crosses develop contrasting technical setups. Matt Simpson examines eight FX markets and gold for potential trading opportunities.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.