- The RBA hiked to 4.85% as widely expected, with the SOMP's cash rate assumptions suggesting scope for one more hike.
- Only six of nine Board members voted for a hike, compared with a unanimous decision in September.
- Inflation forecasts were revised higher, while weaker growth, rising unemployment and housing market pressures complicate the outlook.
- The Aussie dollar weakened as the hike was already priced in and the RBA's tone was slightly less hawkish than expected.
- Bond market repricing hints at a potential end to the RBA's tightening cycle.
RBA Rate Decision: Why AUD/USD Fell Despite Higher Inflation
RBA Hikes to 4.85%, but Split Vote Signals Caution
The RBA delivered the expected 25bp hike today, taking its cash rate to 4.85% – its highest level since November 2008. But it seems the Board has stepped off the gas where further tightening is concerned.
Six of the nine Board members voted for today's hike, meaning three preferred to hold rates steady. This contrasts with the unanimous decision to tighten back in September. Moreover, the RBA removed an explicit reference to the possibility of further rate hikes from its forward guidance.
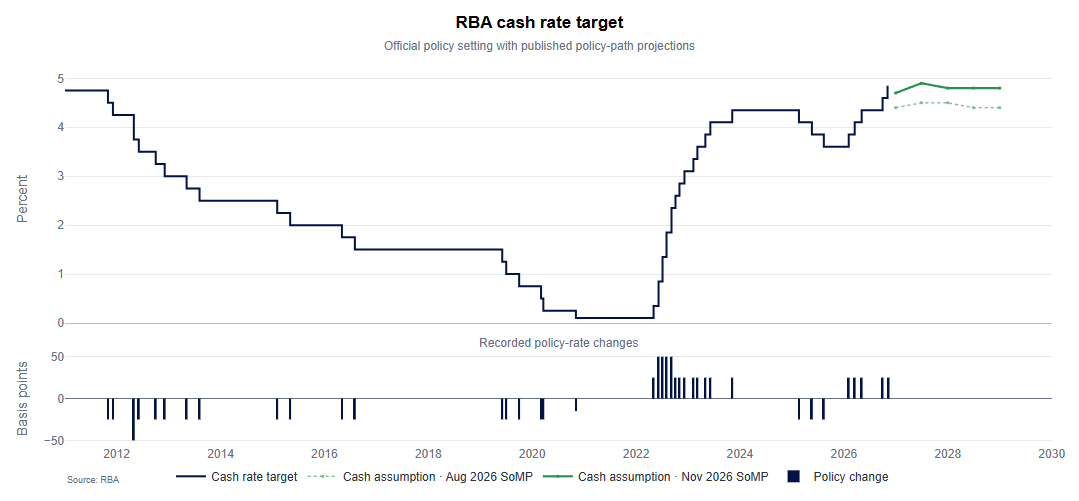
While the RBA vowed to “do what it considers necessary to bring inflation sustainably back to target” – as it did in September – it removed the part that said “including increasing the cash rate target further if needed”.
This comes despite a materially higher inflation outlook, with inflation now expected to remain above 3% for the coming year and not return to the upper end of the RBA's target range until late 2027. The unemployment rate is also expected to rise by more than previously forecast.
The RBA also released its updated forecasts in the Statement on Monetary Policy (SOMP), with the cash rate assumption reportedly revised higher to 4.9% by June 2027, just shy of market pricing of a 5% peak.
Ultimately, today's hike was priced in, and the removal of explicit hawkish guidance alongside a split vote means the meeting could be interpreted as slightly dovish relative to expectations. However, persistent inflation risks suggest the RBA is not necessarily finished tightening.
RBA Revises Inflation Higher, Growth Lower and Unemployment Up
- GDP: Growth revised lower from mid-2027, reaching just 1.3% in late 2027 and early 2028, versus 1.6% previously.
- Headline CPI: Inflation revised sharply higher, peaking around 4.5% in late 2026 before gradually returning towards 2.4% by late 2028.
- Trimmed Mean CPI: Underlying inflation is expected to remain stickier, near 3.5% through early 2027, before easing to 2.4% by late 2028.
- Unemployment: Revised higher across the forecast horizon, reaching 5.1% by late 2028 versus 4.8% previously.
- Wages: Wage growth revised modestly higher in the near term, peaking at 3.4%, before easing to 2.9% by late 2028.
- Cash Rate: The technical assumption has been raised substantially, peaking around 4.9% in early 2027 and remaining near 4.8% through 2028, compared with 4.4% previously.
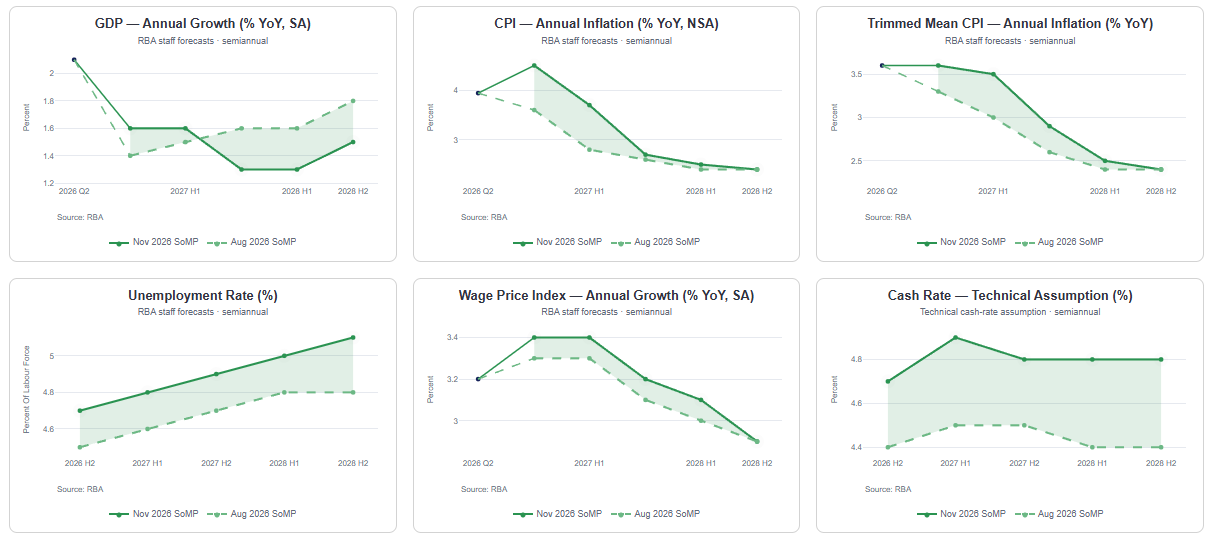
Ultimately, the RBA now expects higher inflation, weaker growth and rising unemployment despite assuming significantly tighter monetary policy.
AUD/USD Falls as Bond Yields Retreat and Risk Appetite Weakens
Australia’s bond yields have dragged the Aussie dollar lower, with the 5-year back down to 4.8% and the 2-year below 4.9%. The AU 2-year minus 10-year yield spread fell from around -17bp to -21bp, signalling a steepening yield curve as shorter-dated yields declined faster than longer-dated yields. This suggests bond traders are scaling back expectations for further RBA hikes following the softer forward guidance and split Board vote.
The AU–US 2-year yield spread has also narrowed as Australian yields fall relative to US yields, adding further pressure on AUD/USD as it tests its 200-day EMA and heads towards a third consecutive daily decline.
Note that the Australian dollar is also lower against all FX majors as it contends with a risk-off tone ahead of the US midterm elections and a repricing of RBA rate expectations.
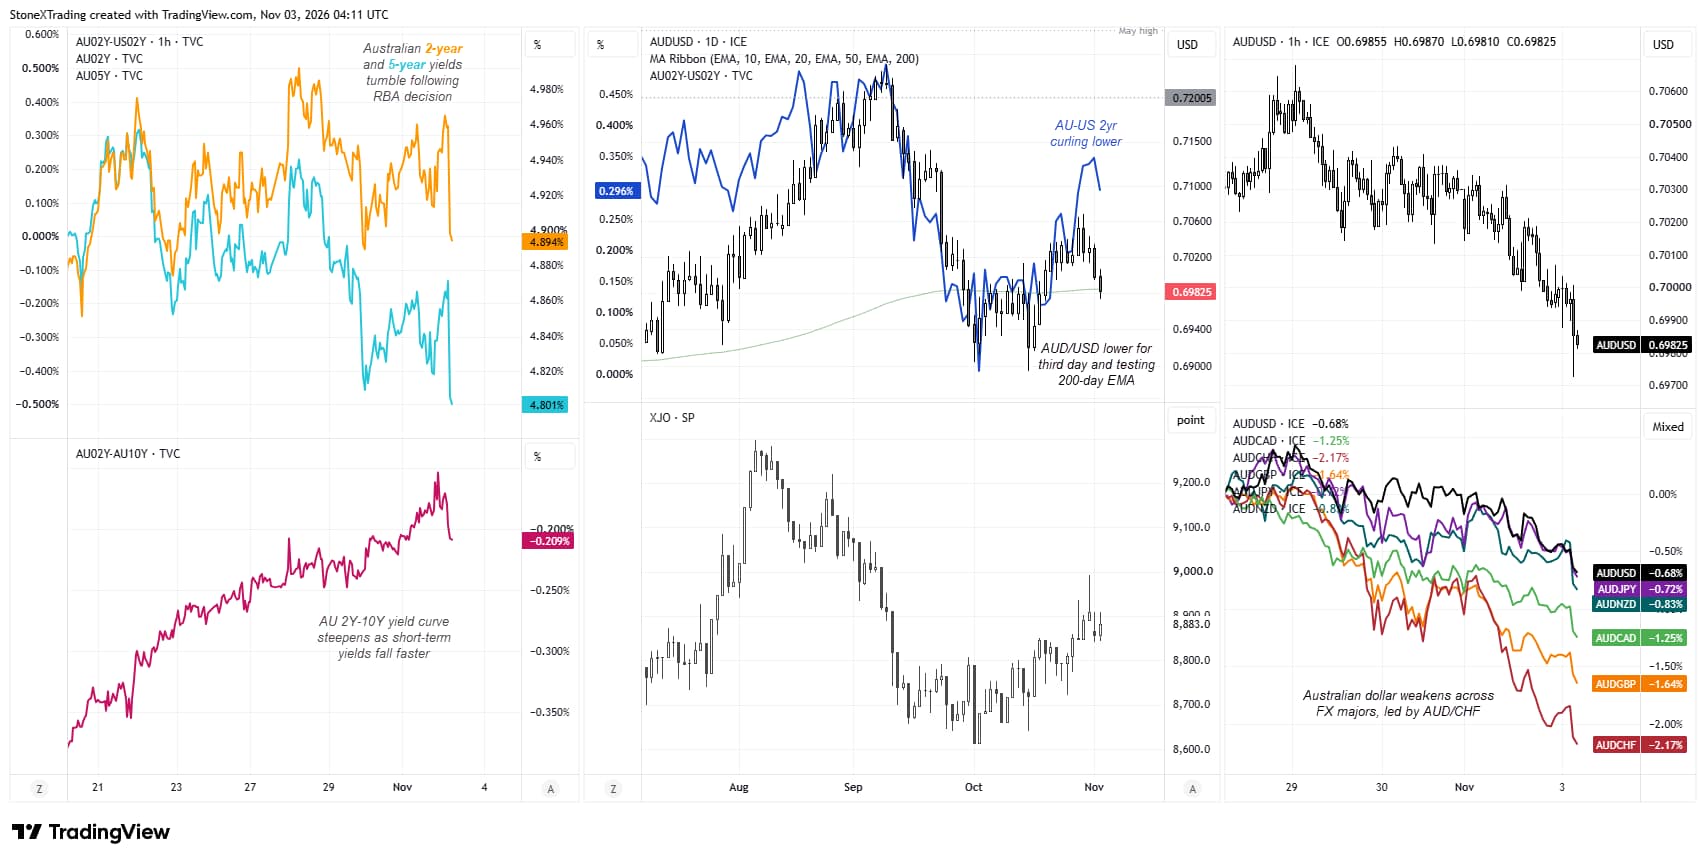
Source: ICE, TradingView
View related analysis:
- USD/CHF Feels the Weight of US Midterms, USD/CAD Clings to Support
- Yen Bulls Loaded Up into BOJ as Euro Shorts Hit 11-Year Extreme | COT report
- AUD/USD Weekly Outlook: RBA Hike, US Midterms and NFP Collide
- Forex, Gold and Oil Outlook: FX Crosses May Have the Edge