

US futures
Dow futures 0.36%, S&P futures 0.26% & Nasdaq futures 0.21%
In Europe
FTSE 0.15% & DAX0.20%
- Stocks steady ahead of Powell’s speech
- A patient Powell could send stocks lower
- Nvidia falls on reports of a H20 production halt
- Oil rises across the week
A cautious Powell could send stocks lower
Stocks are pointing to a higher open on Friday, recovering slightly from yesterday's losses, as investors look ahead to Federal Reserve chair Jerome Powell's speech at the Jackson Hole symposium for clues on the future path for rates.
His speech comes amid signs of a weakening labour market and ongoing uncertainty surrounding the impact of trade tariffs on inflation. Powell’s speech will play a pivotal role in shaping the rate cut expectations for September. A dovish stance could see stocks rebound higher and the USD give up this week’s gains. However, should Powell suggest that the Fed is prepared to wait longer due to concerns over rising inflation, US stocks could fall sharply.
Currently, the market is pricing in a 73% chance for a 25 basis point rate reduction at the September meeting, down from 90% just a week ago. Investors had increased right but expectations following weak non-farm payroll data, although sticky PPI data saw pricing of expectations.
SNP 500 has booked a fifth straight loss on Thursday amid a rotation out of tech stocks into value. The Nasdaq also closed lower for a fifth day. Tech is the weakest sector across the week, energy, and real estate are on track for mild weekly gains.
Corporate news
Nvidia is falling over 1% on reports that the chip designer has asked some component suppliers to halt production of its China-specific H20 AI chip, amid increased scrutiny over the chip from Beijing.
Mesa is rising 0.2% after the tech giant agreed to an 18 billion deal with Alphabet. Mitchell C will use Google Cloud Storage and other services over the next six years.
Zoom is rising 5% after the communication company posted strong Q2 results and boosted its full-year revenue forecast, with continued expansion of its enterprise business.
S&P500 forecast – technical analysis
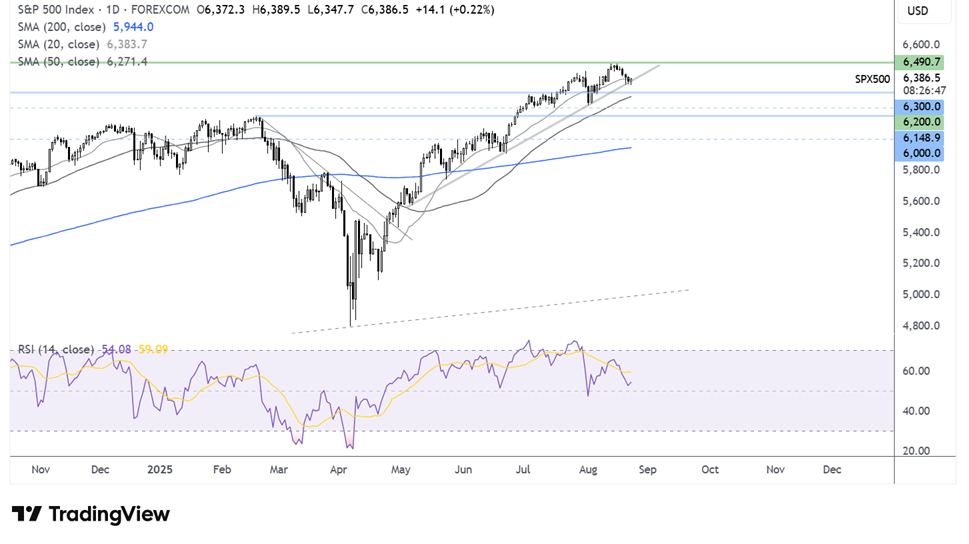
The S&P 500 has eased back from its record high of 6485, testing its rising trendline support. Should buyers defend this support a recovery above 6400 and towards 6485 could be on the cards. A break below the trendline could open the door to a deeper decline towards 6300 and 6225, the August low. Below here the 6200 comes into play.
FX markets – USD rises, EUR/USD falls
The USD is rising, putting gains across the week at 0.9% as traders rein in Fed rate cut expectations ahead of Powell’s speech shortly.
The EUR/USD is falling for a second straight session after German GDP contracted at a steeper pace in Q2, dropping back into recessionary territory. Q2 GDP was downwardly revised to -0.3% a deeper contraction than initially feared, as exports and investments dropped.
The GBP/USD is unchanged at 1.34 but is down 1% this week despite hotter-than-expected inflation and stronger-than-forecast PMI data. However, concerns over the outlook for the economy and expectations that the BoE may cut rates more aggressively next year have kept the pound under pressure.
Oil prices are set for a weekly gain
Oil prices are rising for a third straight day and are on track to gain 1.5% across the week as hopes of peace between Russia and Ukraine dim.
The 3.5-year war is showing no signs of abating, with attacks on both sides ongoing. Reports of Ukraine hitting a Russian oil refinery and an oil pumping station are supporting the oil price.
Trump is seeking a trilateral summit with the Russian and Ukrainian leaders as part of efforts to broker a peace deal. However, discussions surrounding security guarantees are facing obstacles.
Larger-than-expected drawdowns of US food stockpiles have also supported oil prices over the past week. US crude stockpiles fell by 6 million barrels in the week ending August 15, pointing to solid demand..




