



A fourth 50bp RBA rate hike leaves AUDUSD neither shaken nor stirred
At its monthly meeting this afternoon, the Reserve Bank Board raised its official cash rate for a fourth consecutive time by 50bp from 1.85% to 2.35%.
Share this:
At its monthly meeting this afternoon, the Reserve Bank Board raised its official cash rate as expected by 50bp from 1.85% to 2.35%.
In a statement, little changed from August, the RBA again reiterated its commitment to see inflation return to the 2-3% range over time while attempting to keep the economy on an even keel. "The path to achieve this balance is a narrow one and clouded in uncertainty, not least because of global developments."
It continues to see inflation rising to around 7 ¾ % over 2022 before falling back to 4% over 2023 and expects the Australian economy to continue to grow "solidly" boosted by the terms of trade at record highs.
The RBA noted that the unemployment rate was expected to fall to new lows and included this notable addition on wages growth.
"Wages growth has picked up from the low rates of recent years, and there are some pockets where labour costs are increasing briskly. Given the tight labour market and the upstream price pressures, the Board will continue to pay close attention to both the evolution of labour costs and the price-setting behaviour of firms in the period ahead.
The second notable change to the statement was on the impact of higher inflation and higher interest rates on household spending. An addition that hints at a more moderate pace of rate hikes in the future "with the full effects of higher interest rates yet to be felt in mortgage payments."
Supported by the final paragraph, where the RBA again reiterated that while the Board expects to increase interest rate in the months ahead, that policy is "not on a pre-set path" and "The size and timing of future interest rate increases will be guided by the incoming data and the Board's assessment of the outlook for inflation and the labour market."
Our base case remains for a 25bp rate hike in October, which would see the cash rate rise to 2.60%, into mildly restrictive territory before year-end. The RBA is then likely then pause to allow time to assess the full impact of the rate hiking cycle on inflation, growth, and labour market data.
What does it mean for the AUDUSD?
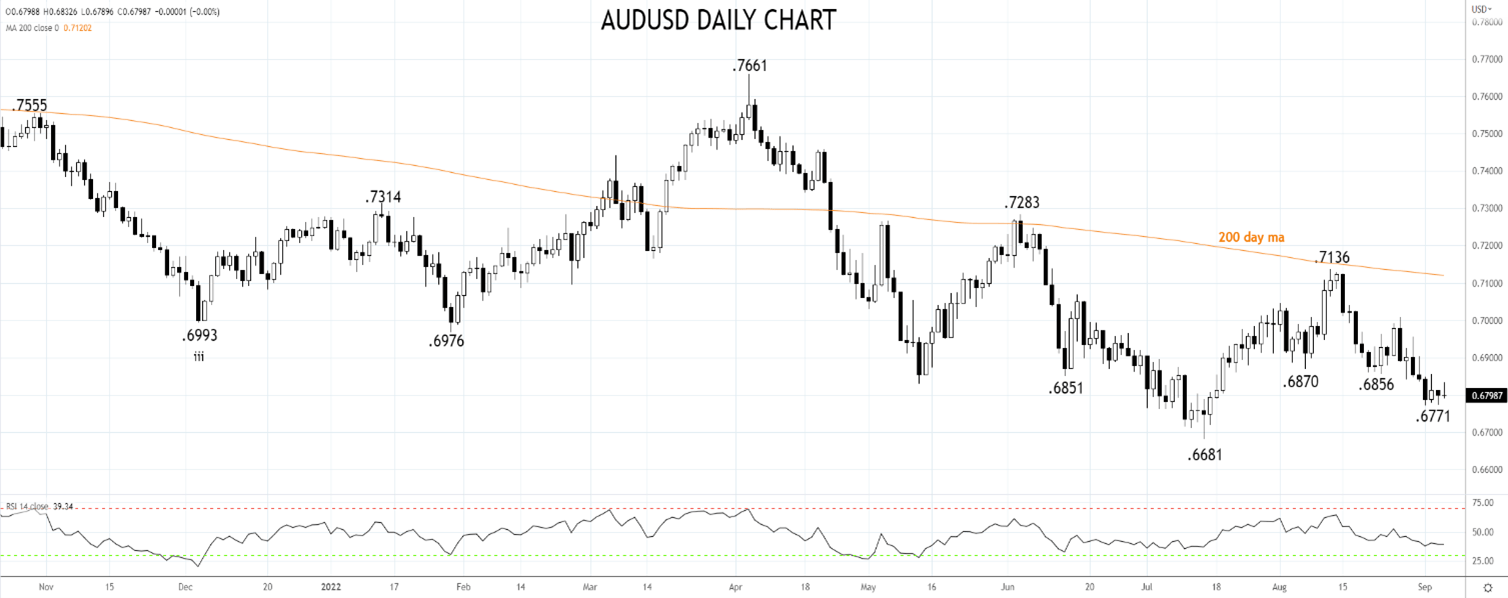
Following the release of the RBA statement, the reaction in the AUDUSD has been relatively muted, trading in a 20-pip range between .6810 and .6790.
Over the past few trading sessions, the AUDUSD has been well capped by resistance .6850/70. The AUDUSD needs to break above this resistance region to alleviate the downside risks after its 4.75% fall from the mid-August .7136 high.
Source Tradingview. The figures stated are as of September 6th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
At its monthly meeting this afternoon, the Reserve Bank Board raised its official cash rate as expected by 50bp from 1.85% to 2.35%.
In a statement, little changed from August, the RBA again reiterated its commitment to see inflation return to the 2-3% range over time while attempting to keep the economy on an even keel. "The path to achieve this balance is a narrow one and clouded in uncertainty, not least because of global developments."
It continues to see inflation rising to around 7 ¾ % over 2022 before falling back to 4% over 2023 and expects the Australian economy to continue to grow "solidly" boosted by the terms of trade at record highs.
The RBA noted that the unemployment rate was expected to fall to new lows and included this notable addition on wages growth.
"Wages growth has picked up from the low rates of recent years, and there are some pockets where labour costs are increasing briskly. Given the tight labour market and the upstream price pressures, the Board will continue to pay close attention to both the evolution of labour costs and the price-setting behaviour of firms in the period ahead.
The second notable change to the statement was on the impact of higher inflation and higher interest rates on household spending. An addition that hints at a more moderate pace of rate hikes in the future "with the full effects of higher interest rates yet to be felt in mortgage payments."
Supported by the final paragraph, where the RBA again reiterated that while the Board expects to increase interest rate in the months ahead, that policy is "not on a pre-set path" and "The size and timing of future interest rate increases will be guided by the incoming data and the Board's assessment of the outlook for inflation and the labour market."
Our base case remains for a 25bp rate hike in October, which would see the cash rate rise to 2.60%, into mildly restrictive territory before year-end. The RBA is then likely then pause to allow time to assess the full impact of the rate hiking cycle on inflation, growth, and labour market data.
What does it mean for the AUDUSD?
Following the release of the RBA statement, the reaction in the AUDUSD has been relatively muted, trading in a 20-pip range between .6810 and .6790.
Over the past few trading sessions, the AUDUSD has been well capped by resistance .6850/70. The AUDUSD needs to break above this resistance region to alleviate the downside risks after its 4.75% fall from the mid-August .7136 high.
Source Tradingview. The figures stated are as of September 6th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.

Nasdaq 100 forecast: Stocks rebound but AI concerns linger
The Nasdaq 100 was finding some support at 28,000 after recent sell-off amid concerns about the AI trade. Even with oscillators oversold, the risk to the near-term forecast is tilted to the downside.

USD/JPY Analysis: Rising U.S. Yields Leave the Yen on the Defensive
As the first week of November progresses, renewed weakness in the Japanese yen is once again becoming evident in the short term. This dynamic can be seen in the recent performance of USD/JPY, which has posted two consecutive bullish sessions and gained more than 0.7%, reflecting a return of buying interest in the dollar while the yen continues to lose momentum.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.