


Crude Oil Weekly Outlook: Back to 2025 Lows
Chinese tariffs are back in the headlines, along with ceasefire deals and OPEC supply cut unwinds. Crude oil prices took another dip, mimicking the April 2025 sell-off. Will crude prices hold above 55 again?
Share this:
Key Events
- Renewed tariff tensions between the U.S. and China, alongside Middle East ceasefire headlines, are pressuring crude prices below 60.
- Daily oversold conditions on crude oil drop to levels last seen in April 2025.
- OPEC supply cut unwinds add surplus risks into 2026.
The scenario of crude oil prices dropping below the 60 mark—supported by OPEC oversupply concerns and tariff war tensions between the world’s two largest economies—appears to be back in play. OPEC’s latest unwind of 137,000 barrels, although smaller in magnitude than previous ones, still contributes to increased market supply amid renewed tariff fears between the U.S. and China.
However, sentiment pricing is being watched closely for any quick rebounds, given that geopolitical uncertainty still poses risks tied to Russia–Ukraine tensions and Trump’s sanctions on crude as new tariff deals develop. Tariff threats are expected to dominate headlines until favorable trade agreements emerge, potentially realigning crude oil into another uptrend in line with future growth trends.
Crude Oil Outlook: Daily Time Frame – Log Scale
Source: Tradingview
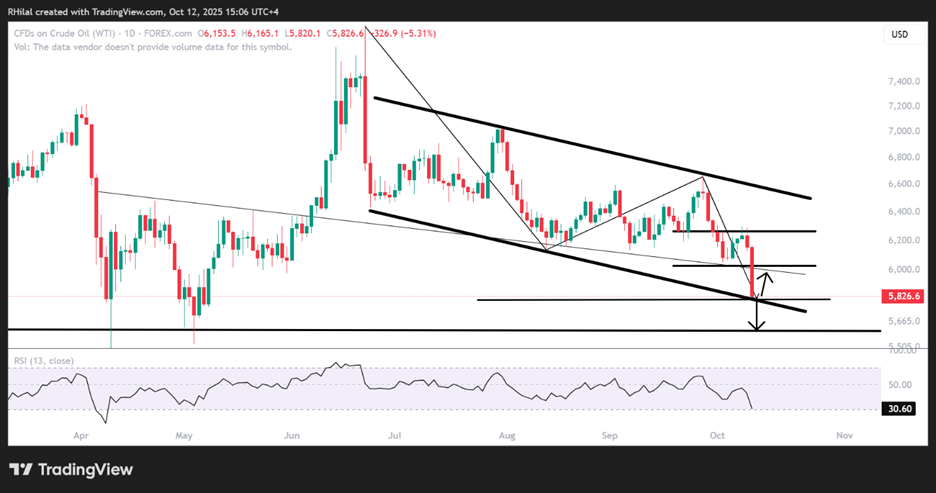
Following the June 2025 peak, crude oil prices have been moving in a sideways-to-bearish consolidation, respecting the bounds of a parallel channel and recently landing near the 58 support. The 58 level aligns with the 0.5 Fibonacci extension of the trend defined by 78.70 (June 2025), 61.40 (August 2025), and 64.80 (September 2025).
A clean break below 58 may open the way for another leg down toward the 0.618 extension at 56. On the upside, a clean hold above 58 could realign gains toward 60 and 63.
Crude Oil Outlook: Monthly Time Frame – Log Scale

Source: Tradingview
From a monthly time-frame perspective, the overall move for crude oil since the 2022 peak is likely a corrective phase within the broader 2020–2022 uptrend. Monthly oversold levels are now realigning with those last seen in 2022, suggesting a possible long-term rebound for crude prices from the 55–49 zone. This area also aligns with the 0.618 retracement of the 2020–2022 rally.
Market sentiment toward fully pricing in OPEC oversupply risks—alongside renewed tariff fears similar to the April low scenario—remains under watch for potential reversal signals, which could present long-term bullish rebound opportunities on the crude oil chart.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Crude Oil, DXY Outlook: Geopolitical Risks Halt Sell-Offs in the Dollar and Oil
The U.S. Dollar Index, Brent and WTI are rebounding from key support levels and oversold conditions after steep sell-offs. U.S.–Iran tensions, inflation risks and rate expectations remain in focus.
dax-record-high-banks-cyclicals-election-relief-rally-european-stocks
The DAX has surged to fresh record highs as investors continue to rotate into banks, industrials and cyclical stocks following the US midterm elections. Falling bond yields, lower oil prices and improving sentiment have supported risk appetite across Europe, helping the index move decisively above 26,000. The focus now shifts from political relief to whether earnings and macroeconomic data can justify the rally's next leg higher.


Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.