


DAX Consolidates Near Highs | Markets Hold Firm Amid US Shutdown
The DAX is consolidating near 24,500 resistance after a strong rally, showing neutral-to-bullish momentum. US equities held firm as the government shutdown entered its second week, led by tech and consumer stocks. Trade tensions rise with Trump’s new truck tariffs and EU steel duties, while gold approaches record highs at $4,900/oz. Global politics stay in focus with Middle East peace talks and renewed US–Ukraine friction
Share this:
Market Overview
US equities were mostly firmer despite the ongoing government shutdown, which entered its second week with no signs of resolution. Gains were led by Consumer Discretionary, Technology, and Utilities, while Real Estate, Consumer Staples, and Health Care lagged.
- S&P 500: +0.36% to 6,740
- Nasdaq 100: +0.78% to 24,979
- Dow Jones: -0.14% to 46,695
- Russell 2000: +0.41% to 2,486
Europe
- France: Political instability persists after PM Lecornu’s resignation; final talks ongoing.
- ECB’s Lagarde: Disinflation phase “over”; policy remains data-dependent with no rate path precommitment.
DAX Remains around key resistance zone
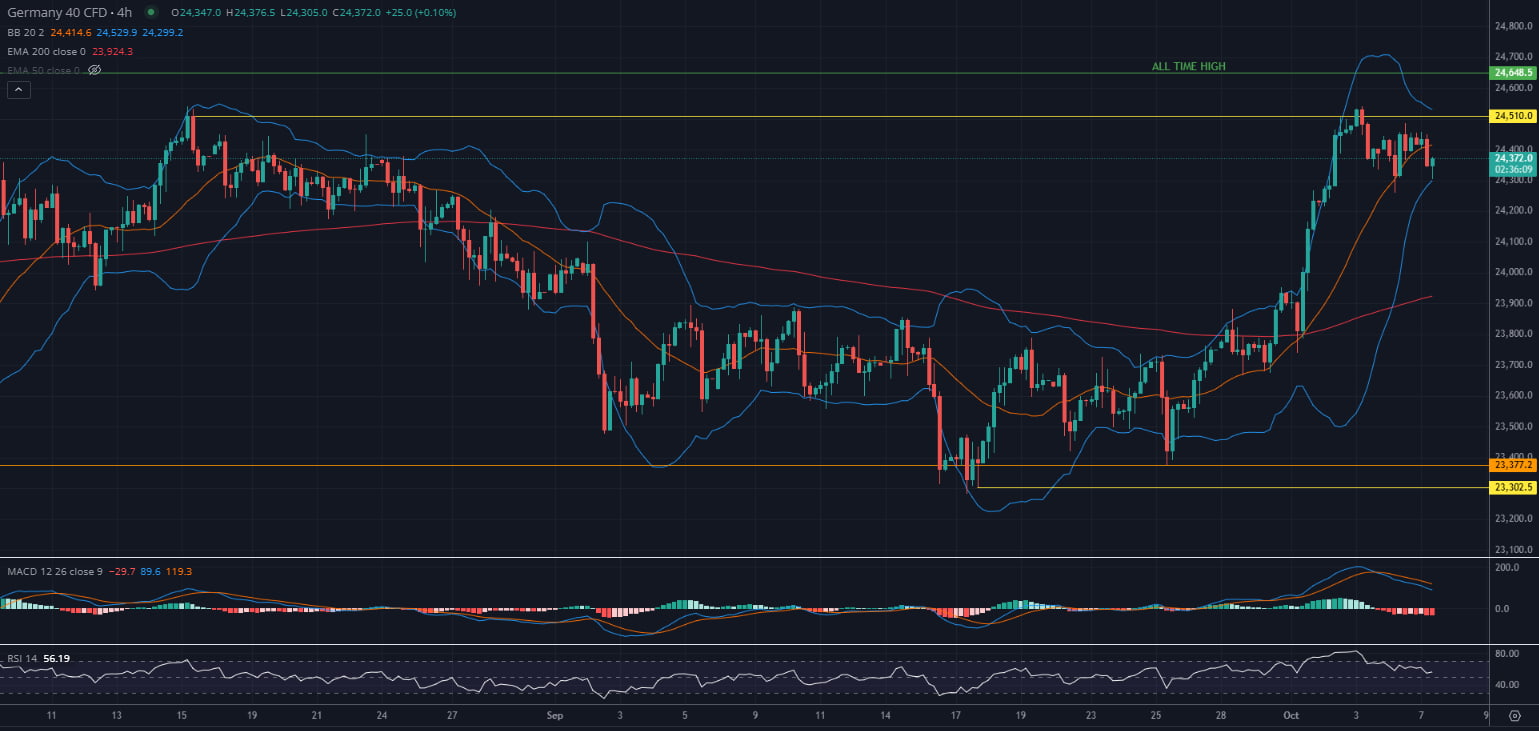
The Germany 40 (4H) continues to consolidate after a recent rally towards the 24,510 resistance area. Price has softened to 24,350–24,300, and is finding support near the 20-EMA and mid-Bollinger Band. This pullback remains within the uptrend that began from the late-September base near 23,300. The RSI (~56) shows that momentum has cooled from overbought territory, and the MACD has crossed lower, reflecting a pause rather than a breakdown. Short-term tone: neutral-to-constructive consolidation.
Trade & Tariffs
- US President Trump announced a 25% tariff on all imported medium and heavy-duty trucks, effective Nov 1.
- Japan will assess details and respond accordingly.
- Trump held “very good” trade calls with Brazil’s President Lula and plans a visit to Brazil.
- The White House confirmed Trump will meet Canada’s PM Carney (Tuesday) and Finland’s President (Thursday); trade discussions are expected.
- Tariff rebates are under discussion but undecided.
- The EU is preparing to impose 50% tariffs on global steel imports exceeding 2013 quota levels (FT).
- White House AI adviser Sacks argued against selling advanced AI chips to China, calling Nvidia CEO Huang a strategic national asset.
US Politics & Economy
- Fed’s Schmid: Inflation remains too high but policy is “slightly restrictive.”
- Government shutdown negotiations stalled; both Republican and Democrat bills failed in the Senate.
- Trump warned layoffs may follow if shutdown persists and reiterated willingness to negotiate on healthcare subsidies once the government reopens.
- Schumer (D) said Democrats are ready to work with Trump but no negotiations yet.
- Trump threatened to invoke the Insurrection Act if unrest escalates; 300 Illinois National Guard members have been federally mobilised.
- A federal judge refused to block the Guard deployment.
APAC Session
- Trading was mixed amid multiple holiday closures (China, HK, South Korea).
- Nikkei 225 hit record highs, boosted by optimism over incoming PM Takaichi and strong household spending data.
- ASX 200 fell on weak consumer confidence.
- US and European futures were subdued amid shutdown uncertainty.
FX:
- USD held gains; JPY remained weak above 150.
- EUR pressured by French political uncertainty.
- GBP steady amid lack of domestic drivers.
- AUD/NZD rangebound ahead of the RBNZ rate decision tomorrow (split views between 25bps or 50bps cut).
Fixed Income:
- USTs flat; supply concerns linger.
- Bunds softer ahead of German data.
- JGBs firmed after strong 30-year auction results.
Commodities:
- Oil rangebound after OPEC+ decisions.
- Gold near record highs; Goldman Sachs raised its 2026 target to $4,900/oz (prev. $4,300).
- Copper steady amid muted China activity.
Crypto:
- Bitcoin eased after hitting a record above $126,000.
Geopolitics
Middle East:
Trump said a Gaza deal is close, with Turkey, Iran, and Jordan expressing support. Negotiations ended “positively” per Egyptian media.
Russia-Ukraine:
Trump is reviewing Tomahawk missile deliveries to Ukraine; EU to restrict Russian diplomats’ movement amid sabotage concerns.
Other:
Trump suspended outreach to Venezuela (NYT).
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Nears New Highs as Investors Rotate Back Into Growth
The DAX continues to push higher, trading above 26,500 as investors extend last week's recovery. Falling oil prices, improving sentiment toward technology stocks and stronger-than-expected German industrial production have helped support risk assets globally. Attention now turns to US inflation data and a busy earnings calendar, which will determine whether the rally can continue toward fresh record highs.
DAX Rebounds as Investors Look Beyond the AI Selloff
The DAX has started the week on a stronger footing, recovering from last week's technology-driven selloff and pushing back toward the key 26,000 level. Improving sentiment across global markets, easing oil prices and a positive reassessment of technology valuations have helped support the rebound. Attention now shifts to Tuesday's US inflation report and a busy earnings calendar, both of which will determine whether the recovery can extend further.
DAX Weakens as Tech and Defence Stocks Come Under Pressure
European equities are under pressure as the global technology selloff extends into a second session. Concerns about AI-related capital expenditure, semiconductor demand and regulatory risks are weighing heavily on technology stocks, while rising oil prices add another layer of uncertainty. With the US jobs report due later today, investors are reassessing valuations, growth expectations and the outlook for interest rates.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.