



FX Futures Positioning: Dollar Rebound Meets Diverging Forex Bets | COT Report
US dollar longs held firm into Jackson Hole, while euro, yen and commodity FX positioning diverged ahead of ISM and NFP.
Share this:
US dollar futures traders remained firmly net-long ahead of Jackson Hole, even as aggregate exposure fell by $8 billion to $26.3 billion. Warsh’s hawkish speech has since driven a rebound in the dollar, putting pressure on several major FX pairs.
Yet positioning beneath the surface remains mixed. Euro longs had begun to recover, yen positioning diverged sharply between large speculators and asset managers, while AUD, NZD and CAD futures showed very different shifts in exposure. This week’s ISM and NFP reports could determine whether the US dollar rebound extends or begins to fade.
View related analysis:
Dollar Rebound Meets Diverging Forex Futures Positioning
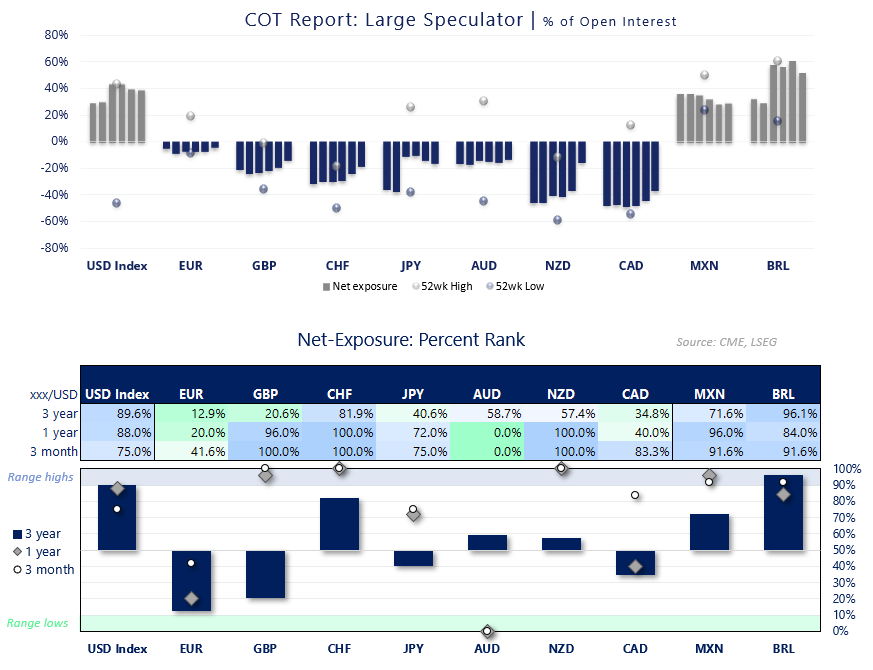
Large Speculator Positioning from the COT report
Source: CFTC (COT), LSEG
- US Dollar: Futures traders reduced aggregate USD exposure by $8 billion ahead of Jackson Hole, though remained firmly net-long by $26.3 billion.
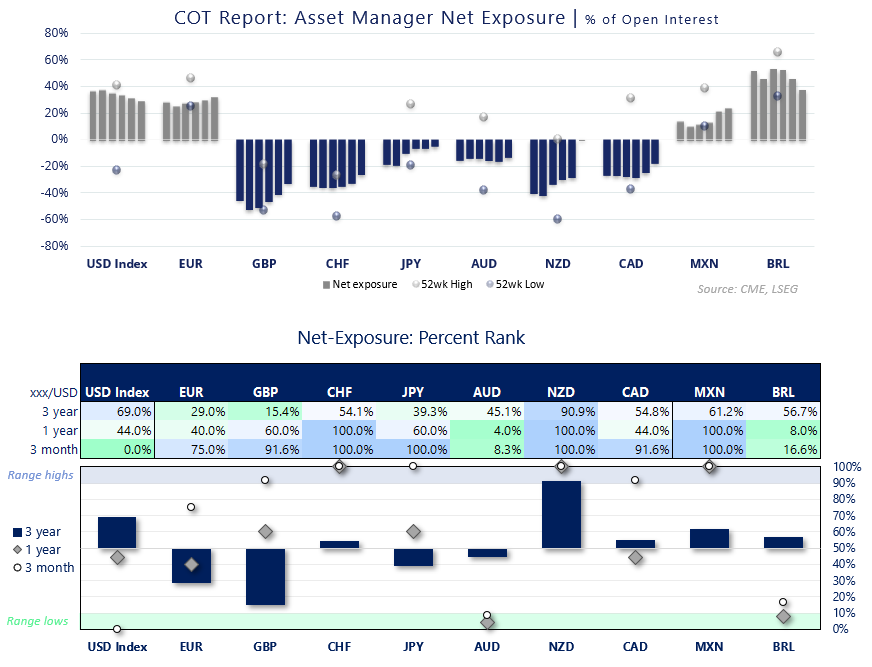
- EUR/USD: Net shorts declined by 22.7k contracts among large specs, while net longs rose by 24k among asset managers.
- GBP/USD: Large specs reduced net shorts by 10k contracts to a 15-week low of 44.5k.
- USD/JPY: Asset managers reduced net-short exposure to a 16-week low of 20.1k contracts, around 60k below the post-MOF intervention peak.
- USD/CHF: Gross longs rose 58% (13.2k contracts) among large specs and 30.2% (12.8k contracts) among asset managers, reducing combined net-short exposure by 16k contracts after the US Treasury announced the bond buyback plan
- USD/CAD: Rising longs and reduced shorts saw combined net-short exposure fall by 67k contracts.
- AUD/USD: Open interest rose to a record high, pointing to strong overall demand from futures traders.
- NZD/USD: Asset managers flipped net-long for the first time since July.
Asset Manager Positioning | COT Report
Source: CFTC (COT), LSEG
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
FX Futures Positioning | COT Report (IMM Data)
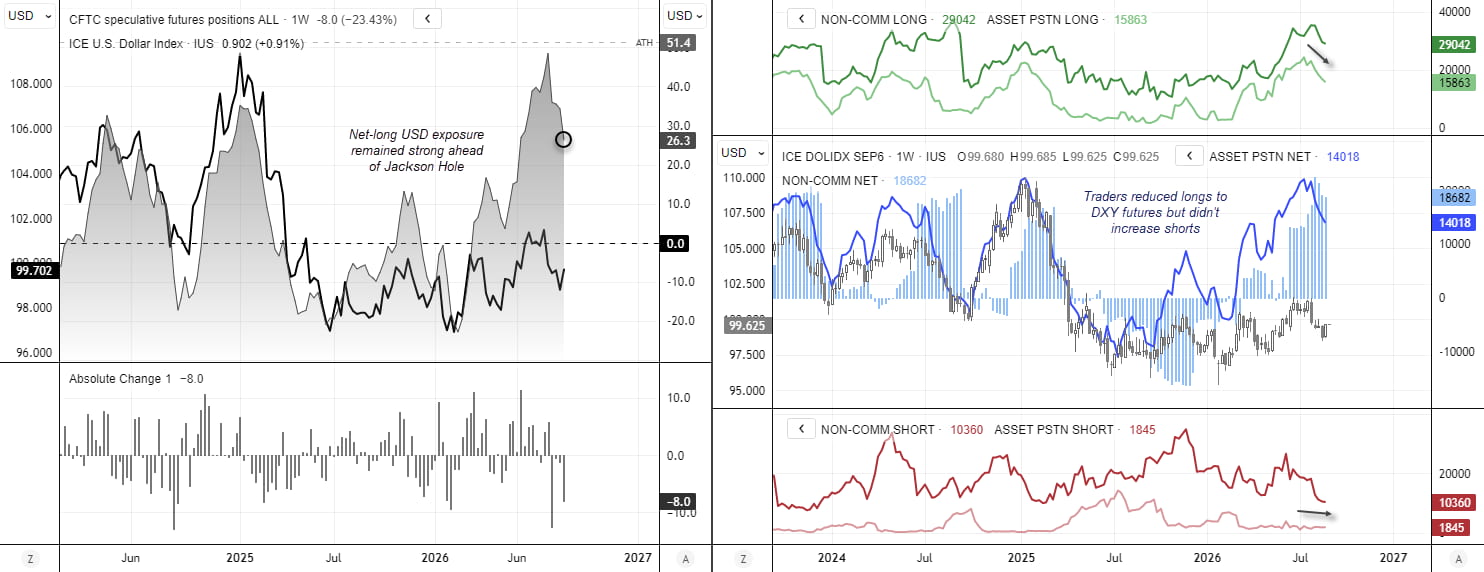
US Dollar Index (DXY) Futures Positioning | COT Report
I had noted over the past couple of weeks that traders had remained relatively net-long despite the pullback in the US dollar. That left the market vulnerable to a rebound heading into Jackson Hole, particularly given the likelihood of a hawkish tone — which was clearly delivered.
Markets against the US dollar are now correcting, at least over the near term. This week’s ISM and NFP reports will help determine how much further the USD rebound can extend by Friday’s close.
Notably, short interest did not pick up in US dollar index futures markets (right chart), either among large speculators or managed funds. And while gross longs were lower, they remained relatively firm overall. The same was true of aggregate net-long exposure among futures traders, which stood at $26.3 billion on Tuesday, ahead of the Jackson Hole speech.
If ISM and NFP remain firm, the US dollar could extend its rebound and see FX majors against it retrace further.
Source: CFTC (COT), ICE, LSEG
EUR/USD Futures Positioning | COT Report
Futures traders were gently warming to the idea of getting long the euro, with gross longs edging higher after several weeks of gross-short reduction. Yet the EUR/USD chart shows a bearish engulfing candle formed following Warsh’s hawkish Jackson Hole speech, which I suspect has already cleared out some of those cautious longs.
Large speculators seem unlikely to return to net-long exposure soon while the anticipated retracement lower in EUR/USD plays out. Asset managers also seem likely to reduce their net-long exposure over the coming weeks, although there is no immediate threat of them flipping net-short.
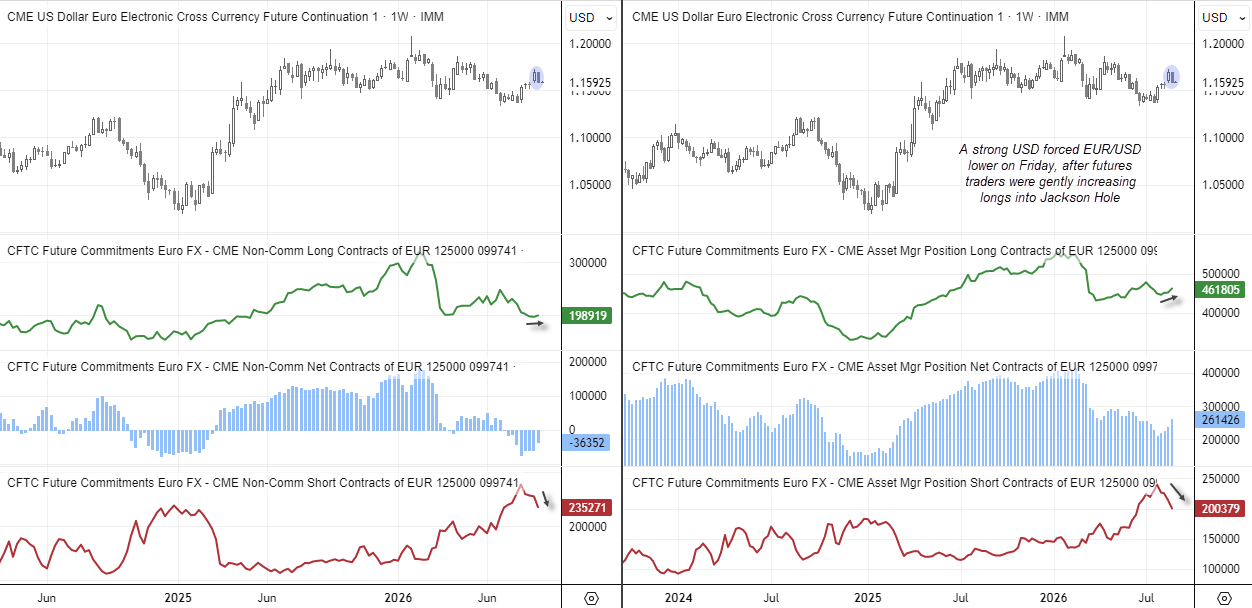
Source: CFTC (COT), CME, LSEG
USD/JPY Futures Positioning | COT Report
It’s interesting to note that net-short exposure among futures traders has diverged. Large speculators increased their net-short position to 63k contracts, while asset managers trimmed theirs to 20k.
Considering this comes after two MOF interventions — one of them a joint operation with the Fed — it almost seems brave for both groups to have reduced their short exposure so substantially. Yet asset managers are now not far from flipping net-long, despite the threat of further intervention from the MOF.
Around two-thirds of economists expect a 25bp hike from the BOJ at its next meeting, according to a recent Reuters poll, while money markets have effectively priced in a hike. Recent inflation data from Japan shows price pressures remain elevated, although momentum has slowed. That could be tempering expectations for imminent hikes beyond the anticipated September move.
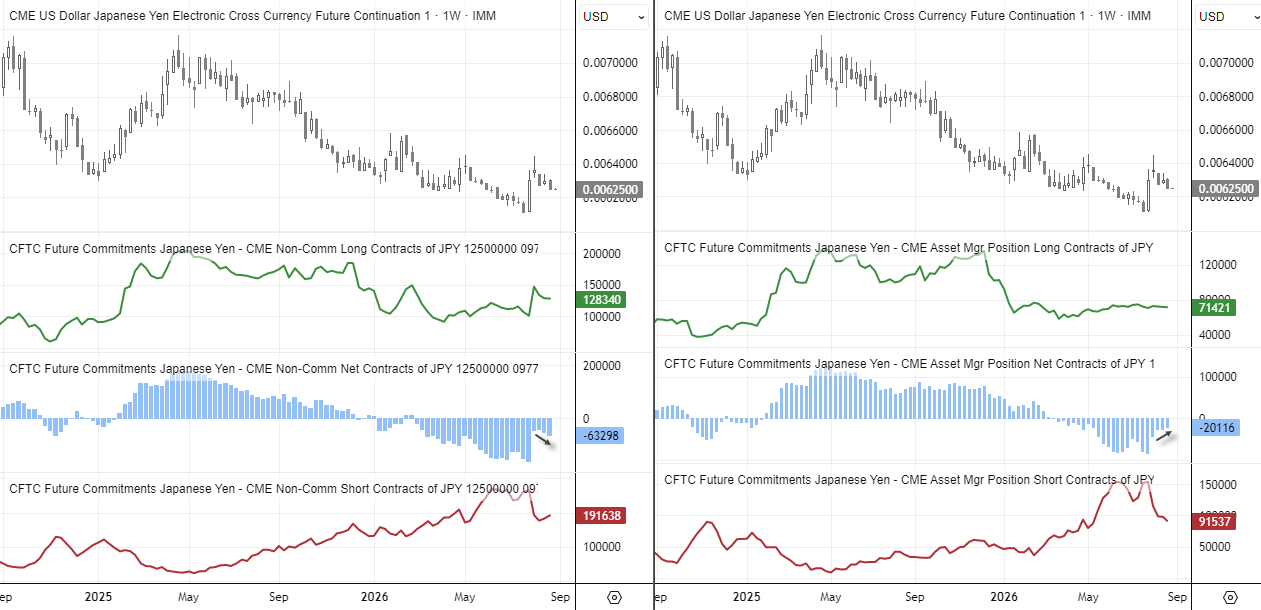
Source: CFTC (COT), CME, LSEG
Commodity FX Futures Positioning (AUD, CAD, NZD) | COT Report
While net-short exposure was effectively flat on the week for AUD/USD futures, both longs and shorts continued to rise. To me, this suggests a lot of hedging was taking place, although Friday’s price action may have cleared out some of those shorts. Still, given the potential for an RBA hike, the pullback in AUD/USD may be limited unless incoming data disappoints to the downside.
The RBNZ is in a clear hawkish phase, and markets have been pricing it accordingly, with gross longs rising and gross shorts falling. A 25bp hike is fully expected in September, with markets betting on another 25bp by December and a third in March. The pullback in NZD/USD may therefore also be limited despite renewed bets of Fed hikes.
Canadian dollar traders have been caught off guard by the resurgence of trade tensions between Canada and the US. This could therefore see a reversal of the recent trend, with net-short exposure potentially increasing in the coming weeks as longs fall and shorts rise.
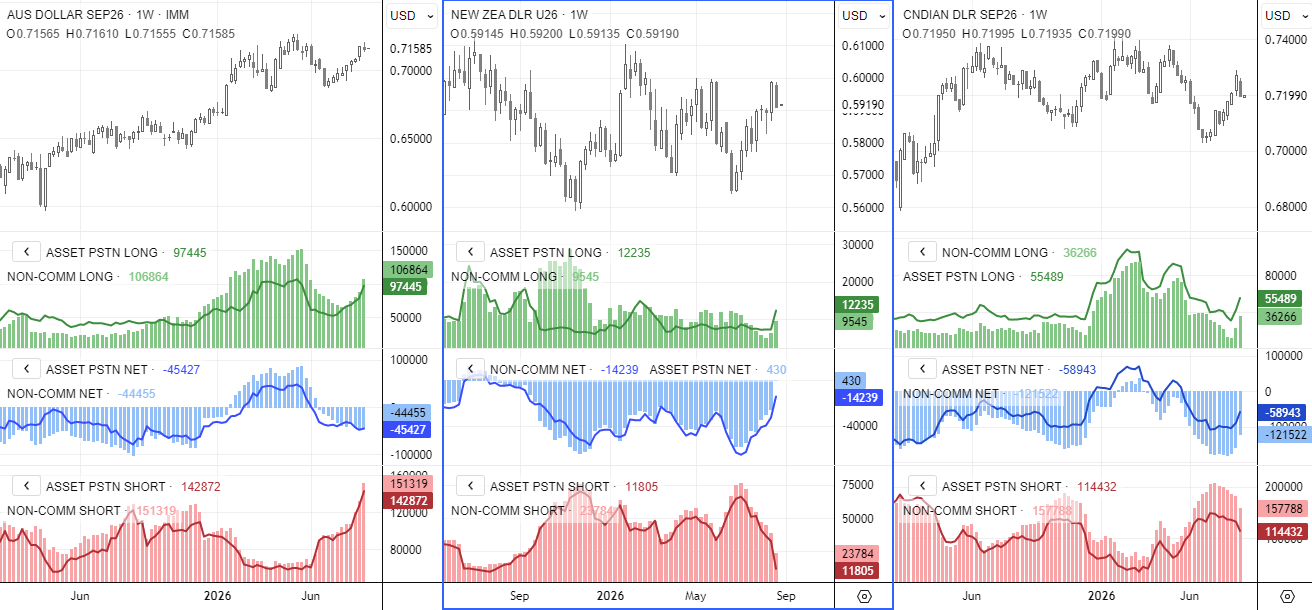
Source: CFTC (COT), CME, LSEG
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

USD/CAD Forecast: Canadian Dollar Gains Ground After U.S. Midterm Elections
The trading week continues to unfold and the recovery in the Canadian dollar has once again become a relevant theme in the short term. This can be clearly seen in the recent performance of USD/CAD, which is down nearly 0.4% during the session, reflecting a consistent recovery in the CAD against the U.S. dollar.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.