




How the US election could impact the Fed
The US dollar and yields have enjoyed a strong rally over the past five weeks, thanks to hotter US data, Fed members pushing back on rate cuts, and Trump leading in many polls. But with the US election on our doorstep and the potential for a delayed result, could this tie the Fed’s hands at this week’s meeting?
Share this:
The US dollar and yields have enjoyed a strong rally over the past five weeks, thanks to hotter US data, Fed members pushing back on rate cuts, and Trump leading in many polls. But with the US election on our doorstep and the potential for a delayed result, could this tie the Fed’s hands at this week’s meeting?
With Fed fund futures implying a 99.7% chance of a 25bp cut this week, it would come as an almighty shock to markets if they didn’t. And unlike other central banks such as the BOJ or SNB, the Fed tend not to surprise much these days. Instead they slowly shape their message to guide markets where they want, with various levels of success and of course failure. This means the Fed are very likely to cut this week regardless of the fact it lands on election week. However…
Which way the election swings could dictate the Fed’s forward guidance
The bigger question for traders is if the Fed hint at another 25bp in December. While Fed fund futures imply they will cut in December with an 81.5% probability, those odds could very quickly plunge if Trump wins the presidency as his policies are deemed to be inflationary.
Besides, US economic data remains strong, and the case for higher rates becomes stronger if data continues to outperform overall.
The US economy remains robust, but there are bumps in the road
We know that US economic data has generally surprised to the upside in recent weeks. In fact it began turning for the better back in July according to the Citi Economic Surprise Index (CESI), with data falling shorts of gloomy forecasts through to October before it began to beat more favourable forecasts over the next five weeks. This saw traders drastically scale back their dovish Fed bets and sent the US dollar and yields soaring.
What has since excited doves is the weak NFP payroll last Friday, which saw a mere 12k job added (its lowest since the pandemic). Yes, that is a weak number, but unemployment remains low at 4.1% and average earnings also increased. This makes it tricky for the Fed to be too dovish this week in my opinion, especially if Trump wins.
A Trump Presidency and the Fed:
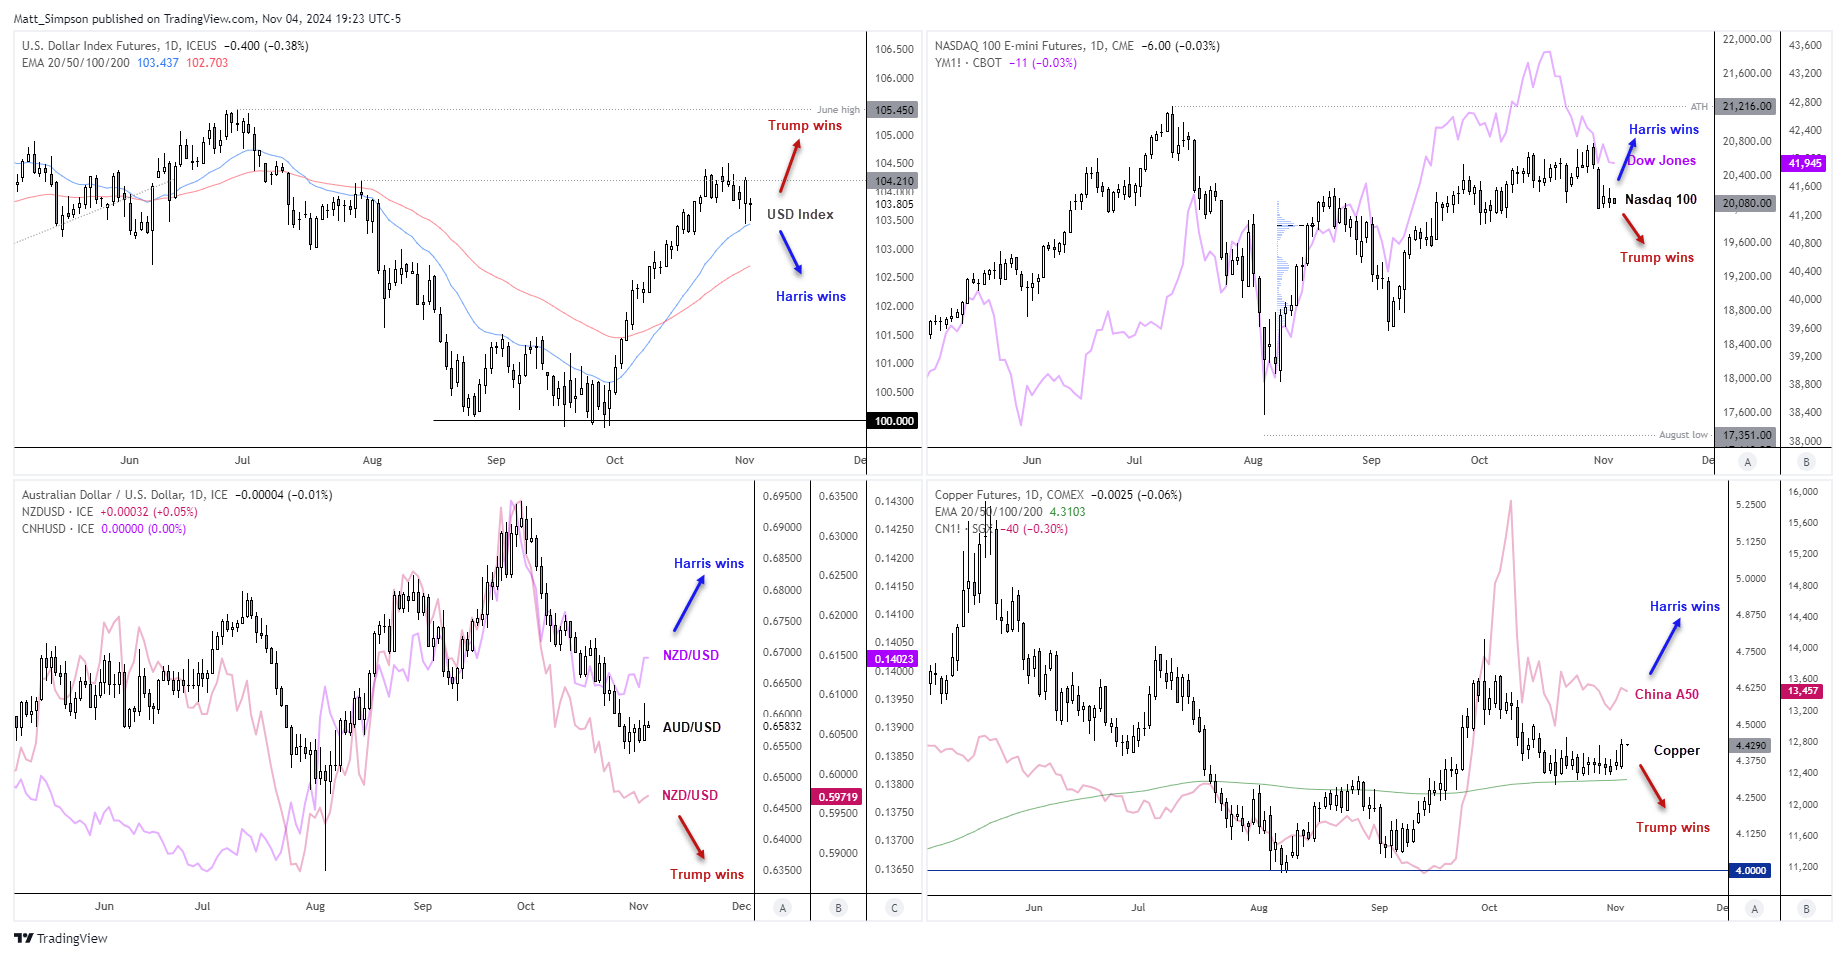
At a fundamental level, Trump's policies are considered to be more inflationary. This implies that another Trump presidency could maintain the elevated levels of the US dollar and the yield curve, or even increase them, on the assumption that the Federal Reserve will need to keep interest rates higher for an extended period. This argument becomes even stronger if US data continues to outperform.
- It could also be risk off for sectors and markets tied to trade, given Trump plans to slap a hefty 60% tariff on China’s imports, alongside less chunky tariffs for other trade partners
- Technology, manufacturing, energy, healthcare and consumer goods stocks could fade selling pressure from Wall Street
- USD/CNH could outperform as the USD rallies and China allow their currency to weaken in an effort to maintain competitive for trade
- This could spell trouble for AUD/USD (and therefore NZD/USD) which currently share a strong correlation with the yuan
A Harris Presidency and the Fed:
Conversely, a Harris win could weigh on the USD and yields, as it could allow the Fed more wriggle room to cut in the face of weaker data. I suspect it could also trigger a risk-on rally which should be supportive of commodities and therefore commodity currencies.
- AUD/USD and NZD/USD could lead gains against the US dollar in a risk-on bounce
- Wall Street indices are likely to perform, led by the Nasdaq 100 as part of a relief rally
- Copper could bounce alongside other base metals on the aversion of a trade war
- USD/CNH could turn lower as Beijing sighs in relief that another trade war is less likely to materialise
But what if they election results take too long to arrive?
If neither candidate has secured the 270 votes by Thursday to secure their place in the Whitehouse, the Fed may need to revise their message. And I suspect the Fed will keep their cards close to their chest and not feel inclined to be too dovish if they cut, assuming that they do at all.
Conclusion
- A Trump win could seriously hamper the Fed’s ability to cut again in December.
- If the election drags on and we do not know the winner by Thursday, the Fed may feel inclined to keep the lid on any forward guidance.
- And knowing markets, that will be taken as ‘no cut for Christmas’ and potentially send the USD higher.
- A Harris win could allow the Fed to deliver a dovish cut, prompt a risk-on rally for commodities, commodity FX and Wall Street
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.