



Jackson Hole FX Returns: Volatility Analysis for USD Dollar, FX Majors
Jackson Hole takes centre stage as Kevin Warsh makes his Fed Chair debut, with 27 years of FX returns revealing a clear volatility pattern.
Share this:
Kevin Warsh’s first Jackson Hole speech as Fed Chair arrives with rate expectations finely balanced and markets still learning how to interpret his policy signals. Historical analysis since 1998 shows volatility tends to rise sharply on speech day, while directional returns across the US dollar and FX majors are far less consistent.
View related analysis:
View related analysis:
How USD and FX Majors Trade Around Jackson Hole
Jackson Hole takes centre stage this week, with Kevin Warsh set to deliver his first speech at the symposium as Federal Reserve Chair. While the event has historically been a platform for important policy signals, expectations are lower that Warsh will use the occasion to telegraph the Fed’s next rate decision.
Instead, traders will be looking for greater clarity on how the Warsh Fed intends to operate, given the relatively little time markets have had to adjust to his less explicit communication style. Ultimately, markets may learn more about how Warsh intends to run the Fed than what it plans to do at its next meeting. Whether that includes the Fed’s reaction function to inflation and growth, the rise in crude oil and Treasury yields, or clues on the balance sheet and communication framework remains to be seen. That leaves plenty of scope for volatility if Warsh challenges how markets currently understand the Fed, even without signalling an imminent policy change.
Fed Hike Odds Sit on a Knife Edge
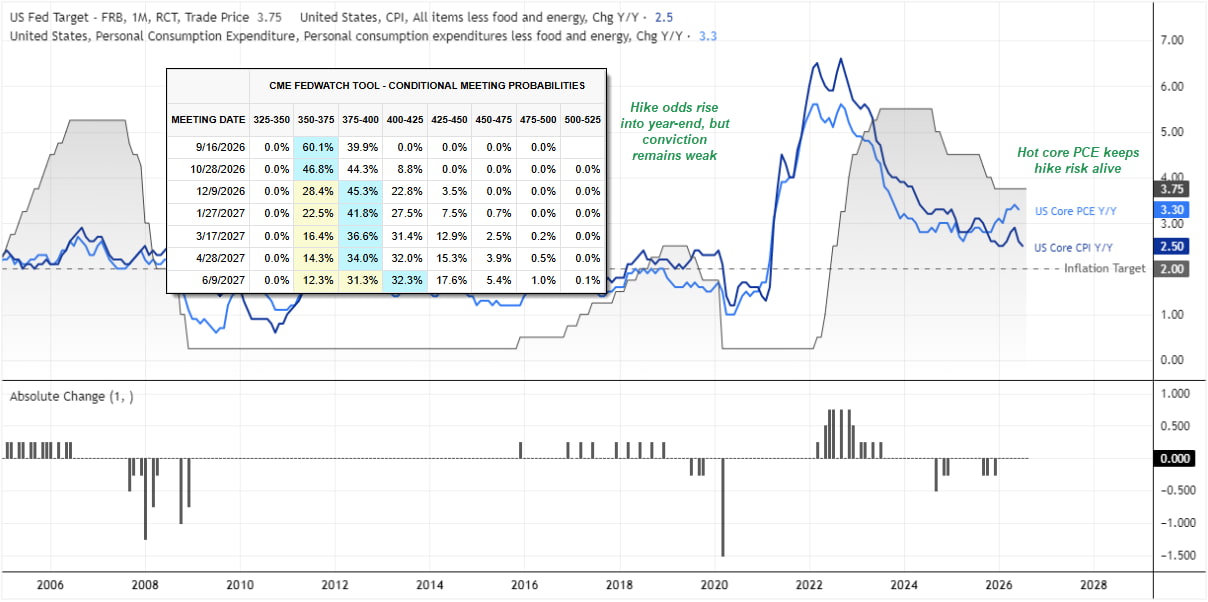
Traders are currently pricing just one Fed hike for the remainder of 2026, but conviction around its timing remains weak. Fed funds futures imply roughly a 35% chance of a September hike and around 66% by December, leaving the outlook finely balanced between no further tightening and one final move higher.
That uncertainty has only increased since the July meeting, where Warsh’s less explicit guidance left markets searching for a clearer reaction function. With inflation still elevated but recent jobs and spending data softer, Jackson Hole could shift those odds sharply even if Warsh stops short of signalling an imminent hike.
PCE inflation is released ahead of Warsh’s speech, making it an important final input for traders assessing the likelihood of another Fed hike. A hotter or softer print could shift rate expectations before Jackson Hole even begins.
Source: CME
Warsh Needs No Policy Shift to Move Markets
Jackson Hole has produced some major policy signals, but not every Fed Chair has used it to announce a shift. Some speeches have barely moved markets; others have materially changed how investors viewed the Fed. So while Warsh may not reveal an imminent policy change, even a subtle shift in tone could move Treasury yields and the US dollar sharply, and trigger broader market volatility.
|
Year |
Fed Chair |
Jackson Hole Takeaway |
Notable Market Reaction |
|
1998 |
Greenspan |
Global stress preceded Fed easing |
USD and equities volatile amid Russia/LTCM stress |
|
2007 |
Bernanke |
Fed signalled willingness to respond to the subprime crisis |
Rate-cut expectations increased as credit stress intensified |
|
2010 |
Bernanke |
Helped lay the groundwork for QE2 |
USD weakened as further QE expectations grew |
|
2012 |
Bernanke |
Reinforced the case for further QE |
USD came under pressure; gold and equities benefited |
|
2020 |
Powell |
Introduced flexible average inflation targeting |
USD weakened as markets priced greater tolerance for inflation |
|
2022 |
Powell |
Delivered a forceful hawkish inflation message |
Stocks plunged and Treasury yields rose; USD strengthened |
|
2024 |
Powell |
Signalled the time had come to adjust policy |
USD and Treasury yields fell; equities rallied |
|
2025 |
Powell |
Shifted focus towards labour-market risks and easing |
USD and short-term yields fell; equities rallied |
|
2026 |
Warsh |
TBC |
TBC |
How the US Dollar Index Trades Around Jackson Hole
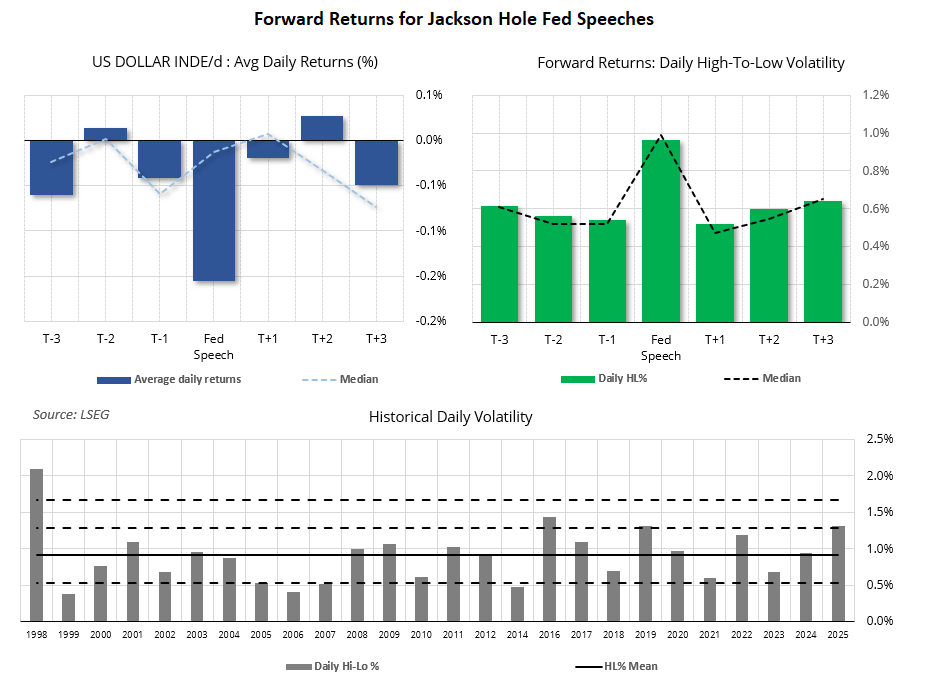
While history shows why Jackson Hole can matter, it also highlights how inconsistent the directional response can be from one year to the next. The more reliable historical pattern is volatility, with DXY tending to see its largest average move on the Fed Chair’s speech day itself.
Data since 1998 show daily volatility tends to peak on the day of the Fed speech. The US dollar index has posted an average daily range of 0.9% and a median of 1%. With the two measures so close, the pattern looks relatively robust — and that is broadly reflected across the three trading days either side of the speech.
DXY Volatility Rises, but Direction Remains Uncertain
Notice how volatility gradually declines from T-3 to T-1, which ties in with my earlier point that markets could quieten heading into Warsh’s speech. Volatility then tends to fall to its lowest level on the first trading day afterwards (T+1), before gradually picking up again.
The lower chart shows that while the average speech-day range is 0.91%, volatility has fallen below one standard deviation at 0.53% on five occasions, but exceeded one standard deviation at 1.29% just three times. The most volatile was Greenspan’s 1998 speech, when the daily range topped 2%.
Interestingly, DXY has generated an average return of around -0.2% on speech day, although the median is only marginally negative at -0.01% — effectively flat. That suggests picking direction from historical performance is closer to a coin flip than simply observing that volatility tends to rise. Ultimately, Jackson Hole may create opportunity through larger moves, but the directional bias for the US dollar is far less certain.
Source: ICE, TradingView
For a closer look at FX performance, I will also provide the average returns and volatility levels for some of the key FX majors.
EUR/USD (Euro) Forward Returns Analysis
Source: LSEG
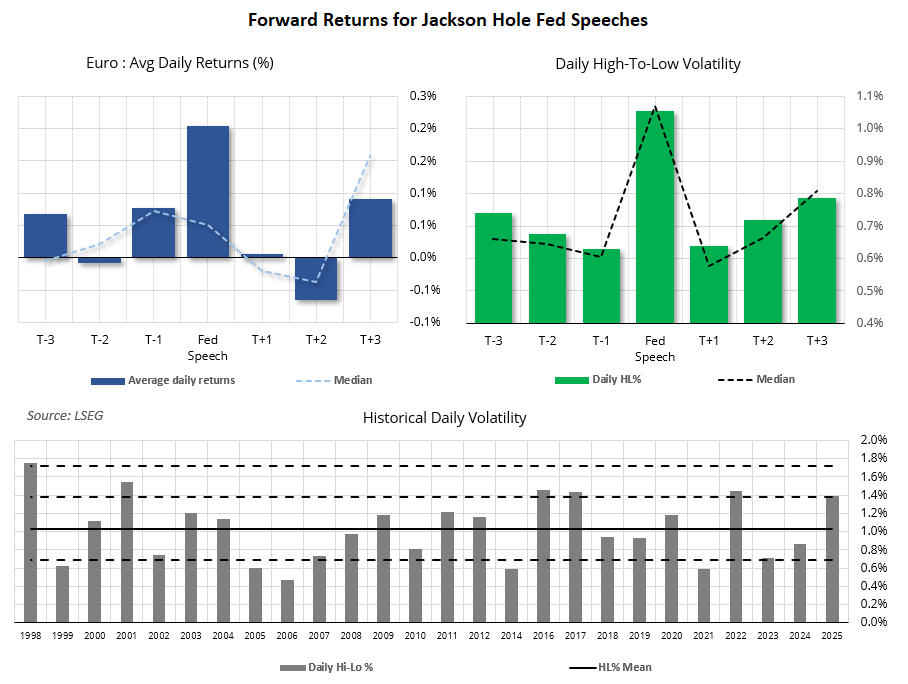
- Euro volatility peaks on Fed speech day, with the average high-low range rising to roughly 1.0%.
- Average speech-day EUR/USD returns are positive at around 0.2%, though the median is much smaller, suggesting limited directional consistency.
- Volatility tends to ease into the speech from T-3 to T-1, then drops sharply on T+1 before rebuilding.
- Speech-day volatility has varied widely by year, from roughly 0.5% to 1.8%, reinforcing that Jackson Hole is more reliable as a volatility event than a directional signal.
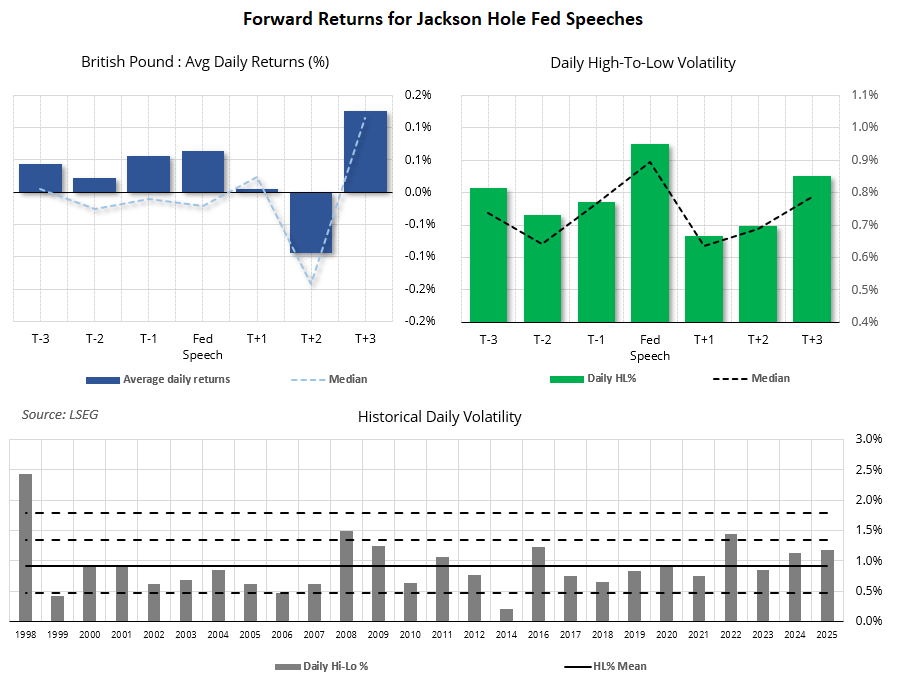
GBP/USD (British Pound) Forward Returns Analysis
GBP/USD shows much less directional bias on speech day than EUR/USD, with average and median returns close to flat despite volatility still rising.
Source: LSEG
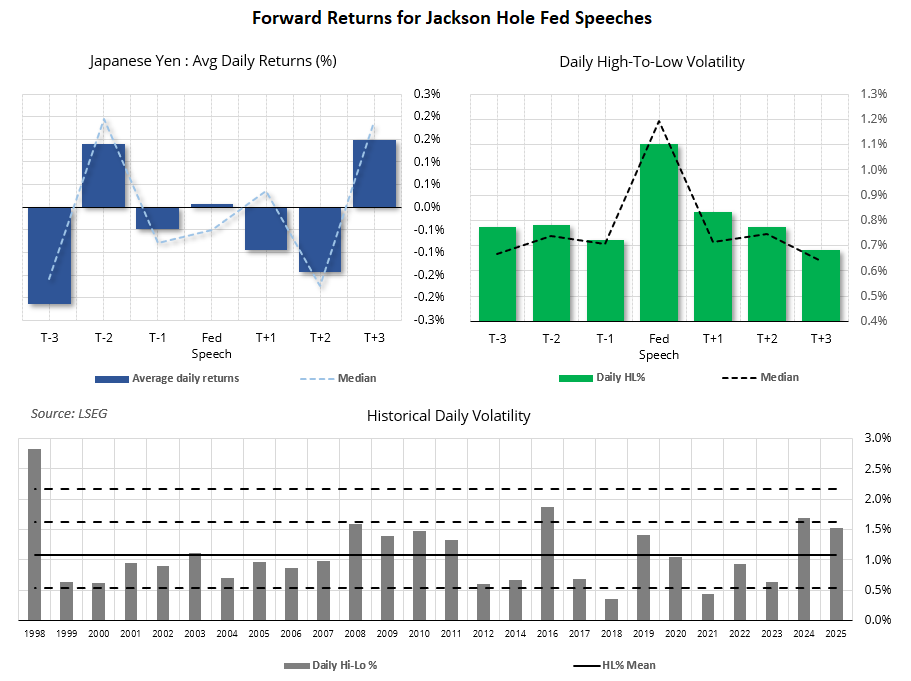
USD/JPY (Japanese Yen) Forward Returns Analysis
USD/JPY shows unusually weak directional consistency around Jackson Hole, with the average speech-day return almost flat despite a clear jump in intraday volatility to roughly 1.1%. That makes it look more like a two-way volatility trade than a clean directional setup.
Source: LSEG
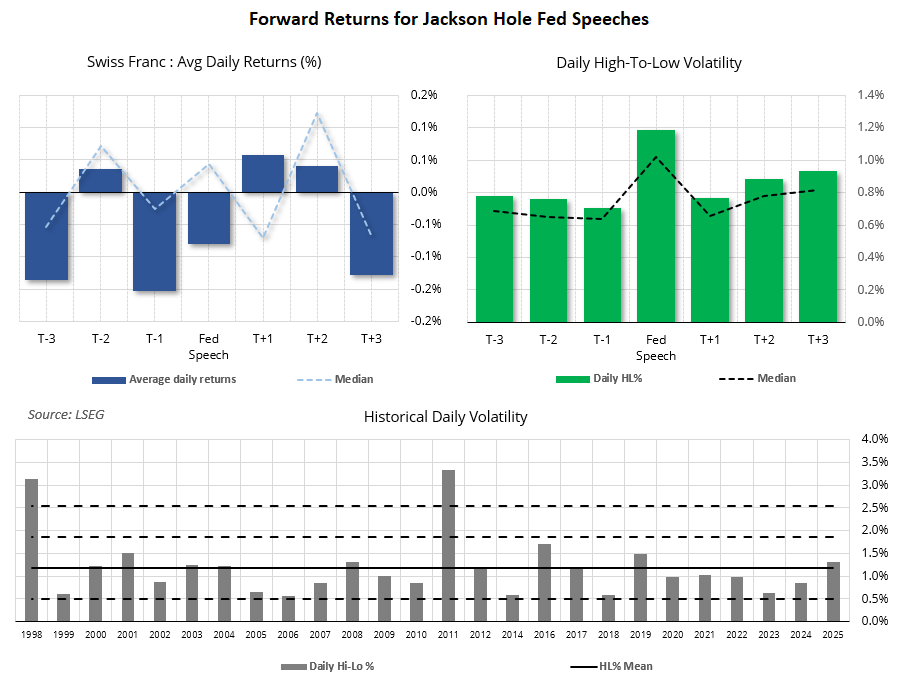
USD/CHF (Swiss Franc) Forward Returns Analysis
USD/CHF stands out for tail risk, with 2011 producing a speech-day range above 3% — far beyond the typical Jackson Hole move.
Source: LSEG
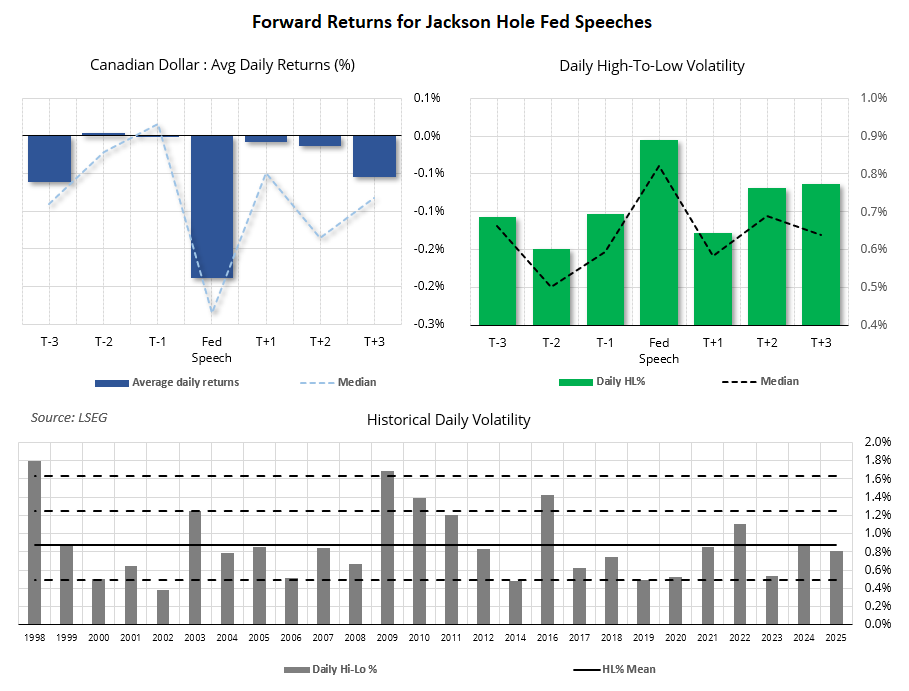
USD/CAD (Canadian Dollar) Forward Returns Analysis
USD/CAD shows one of the clearest bearish speech-day biases, with both average and median returns around -0.2% to -0.3%. Speech-day volatility rises to roughly 0.9%, but remains relatively contained compared with some other FX majors.
Source: LSEG
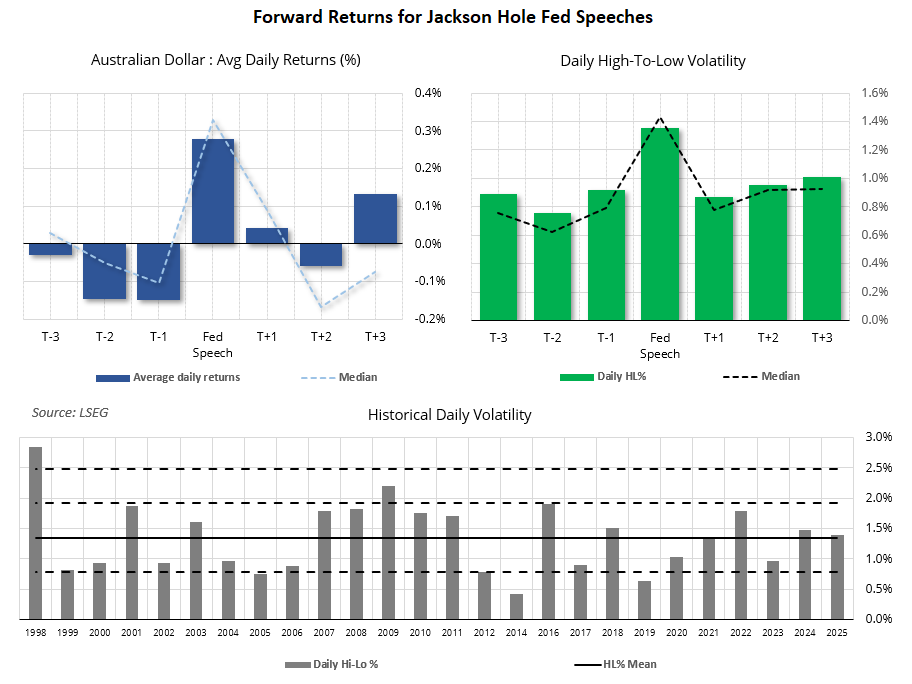
AUD/USD (Australian Dollar) Forward Returns Analysis
AUD/USD shows one of the clearer positive speech-day biases, with both average and median returns notably above zero, while volatility also rises sharply on the day of the Fed speech.
Source: LSEG
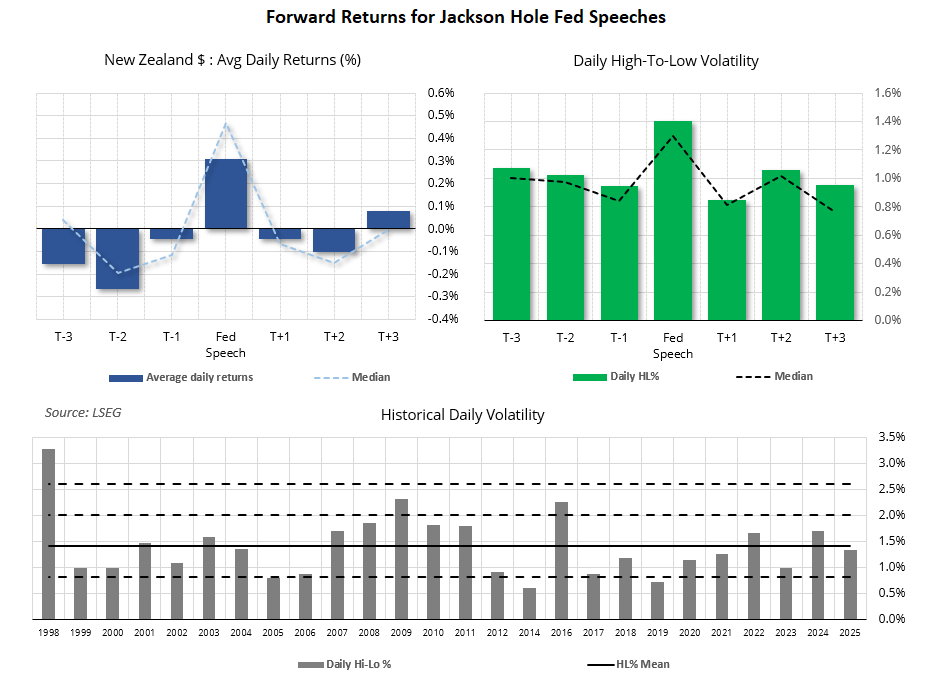
NZD/USD (New Zealand Dollar) Forward Returns Analysis
NZD/USD shows the strongest positive speech-day bias of the FX majors so far, with both average and median returns clearly positive.
Source: LSEG
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

USD/CAD Forecast: Canadian Dollar Gains Ground After U.S. Midterm Elections
The trading week continues to unfold and the recovery in the Canadian dollar has once again become a relevant theme in the short term. This can be clearly seen in the recent performance of USD/CAD, which is down nearly 0.4% during the session, reflecting a consistent recovery in the CAD against the U.S. dollar.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.