



NFP Preview: How the Jobs Report Could Force the Fed’s Hike or Hold Decision
NFP leading indicators point to a potentially above-expected reading in this month’s jobs report, with headline job growth coming in somewhere in the 75-125K range, with a chance the report tips the scales on the FOMC interest rate decision later this month.
Share this:
NFP Key Points
- NFP report expectations: +55K jobs, +0.3% m/m earnings, unemployment at 4.1%.
- NFP leading indicators point to a potentially above-expected reading in this month’s jobs report, with headline job growth coming in somewhere in the 75-125K range.
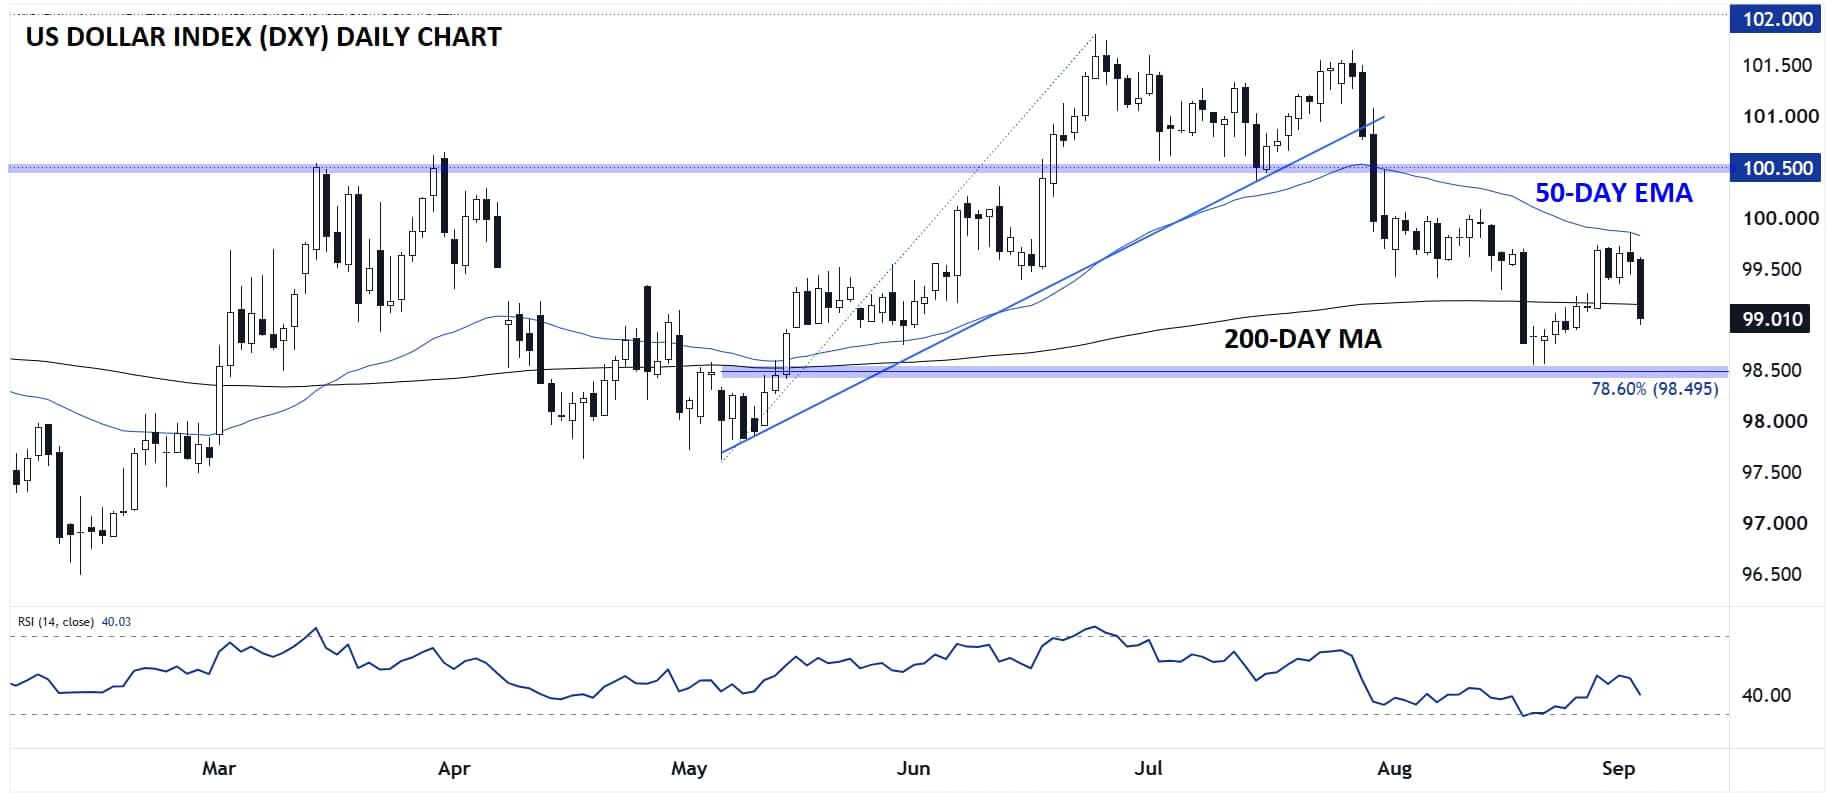
- The US Dollar Index (DXY) is holding roughly in the middle of the year-to-date range, though with today’s selloff, it’s nearing the lowest level it has traded at since mid-May.
When is the August NFP Report?
The August NFP report will be released on Friday, September 4, at 8:30 ET.
NFP Report Expectations
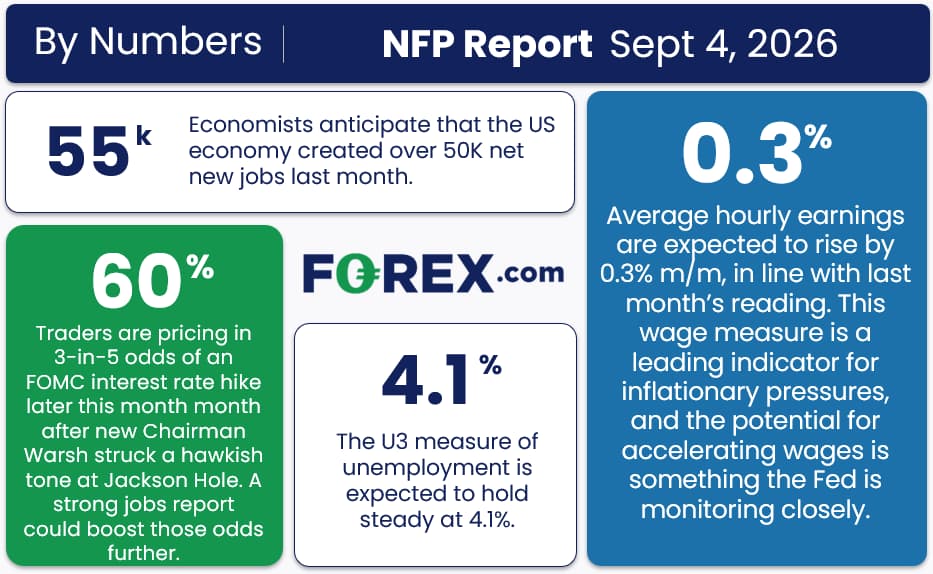
Traders and economists expect the NFP report to show that the US created 55K net new jobs, with average hourly earnings rising 0.3% m/m (3.0% y/y) and the U3 unemployment rate at 4.1%.
NFP Overview
Last month’s jobs report changed the conversation around the US labor market. The outright decline in jobs (-23K) and negative revisions to previous reports raised concerns about the start of an AI “jobpocalypse” and potential stagflation down the road, at the same time that the Federal Reserve turned in a decidedly more hawkish direction amidst elevated price pressures.
Perhaps surprisingly against that backdrop, traders are anticipating a reasonably solid report this month:
Source: StoneX
As the graphic above shows, expectations are for a return to positive territory, with modest job growth, stable unemployment, and continued gradual wage increases.
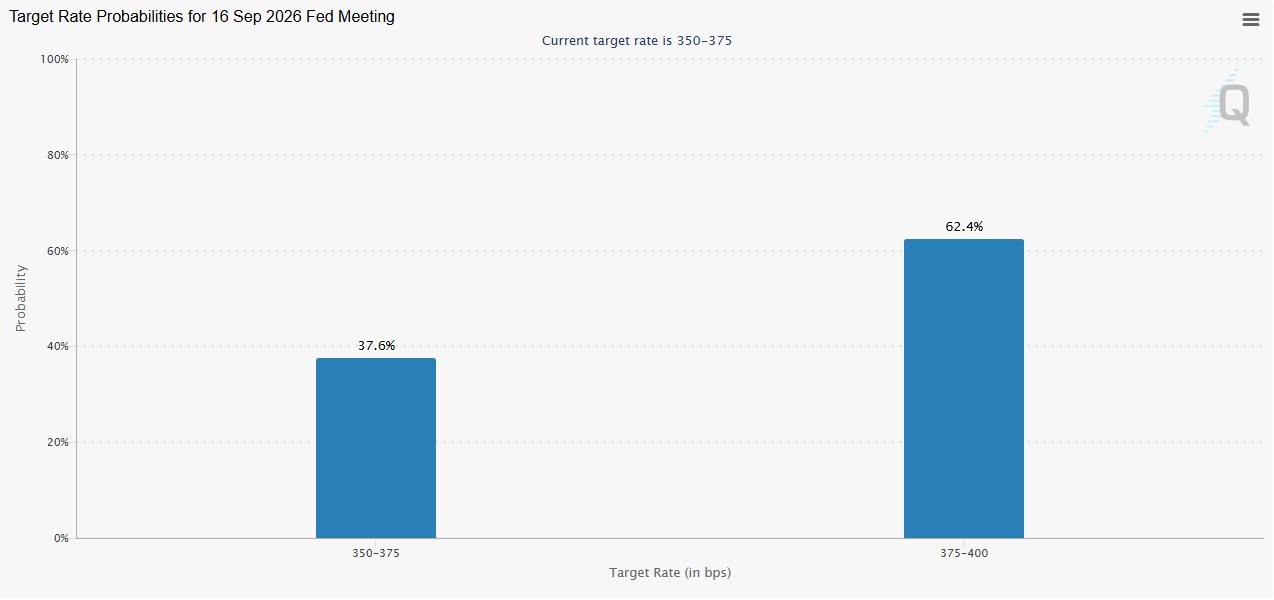
With inflation holding well above the Federal Reserve’s 2% target, traders are pricing in another interest rate hike from the Federal Reserve as soon as this month, with the CME’s FedWatch tool showing about a 60% probability of such a move, after Chairman Warsh struck a relatively hawkish tone at the Jackson Hole Economic Symposium last month:
Source: CME FedWatch
NFP Forecast
As regular readers know, we focus on four historically reliable leading indicators to help handicap each month’s NFP report:
- The ISM Manufacturing Employment subindex rose to 51.2 from 51.8 last month.
- The ISM Services Employment subindex ticked higher to 47.8 from 47.4 last month.
- The ADP Employment report came in at 38K jobs, down incrementally from last month’s 46K reading.
- The 4-week moving average of initial unemployment claims fell to 207K, up from 199K last month.
Weighing the data and our internal models, the leading indicators point to a potentially above-expected reading in this month’s jobs report, with headline job growth coming in somewhere in the 75-125K range, albeit with a big band of uncertainty given the limited response rates.
Regardless, the month-to-month fluctuations in this report are notoriously difficult to predict, so we wouldn’t put too much stock into any forecasts (including ours). As always, the other aspects of the release, including the closely watched average hourly earnings figure and unemployment rate will also impact how markets react to the release.
Potential NFP Market Reaction
|
Wages < 0.2% m/m |
Wages 0.2-0.4% m/m |
Wages > 0.4% m/m | |
|
< 25K jobs |
Bearish USD |
Slightly Bearish USD |
Neutral USD |
|
25-125K jobs |
Neutral USD |
Neutral USD |
Neutral USD |
|
> 125K jobs |
Slightly Bullish USD |
Slightly Bullish USD |
Bullish USD |
Technically speaking, the US dollar is trading near its lowest level in three months, but off the lows from the start of last week, leaving the technical outlook relatively balanced.
US Dollar Index Technical Analysis – DXY Daily Chart
Source: TradingView, StoneX
As the chart above shows, the US Dollar Index (DXY) is holding roughly in the middle of the year-to-date range, though with today’s selloff, it’s nearing the lowest level it has traded at since mid-May. Technically speaking, there’s not a clear directional trend across the medium-term as traders await more clarity on the Fed’s reaction function under Chairman Warsh.
Accordingly, a strong jobs report that alleviates any concerns about the labor market would increase the odds of a rate hike in less than two weeks’ time, likely boosting the greenback and bringing the 50-day EMA in the upper-99.00s back into sight. Conversely, a weak jobs report could give Warsh and Company an excuse to hold off for another meeting, weighing on DXY and putting the 3.5-month low at 98.50 under pressure.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.