

NZD Hit as Softer CPI Keeps RBNZ Easing in Play
Despite some sticky spots, New Zealand’s latest CPI report points to fading inflation risks—keeping a further RBNZ cut firmly in play.
Share this:
- Q2 CPI rose 2.7% y/y vs 2.8% expected, 2.6% RBNZ forecast
- Core inflation ticked up to 2.7% but stayed within target
- Market sees 85% chance of RBNZ cut in August
- NZD/USD weaker, stays in firm downtrend
NZD Summary
Consumer prices in New Zealand rose less than forecast in the June quarter, delivering a modest decline in the New Zealand dollar. While marginally above what the Reserve Bank of New Zealand (RBNZ) forecast in May, the underlying detail of the report points to the likelihood of at least one additional rate cut from policymakers over the remainder of the year.
Inflation Remains Contained
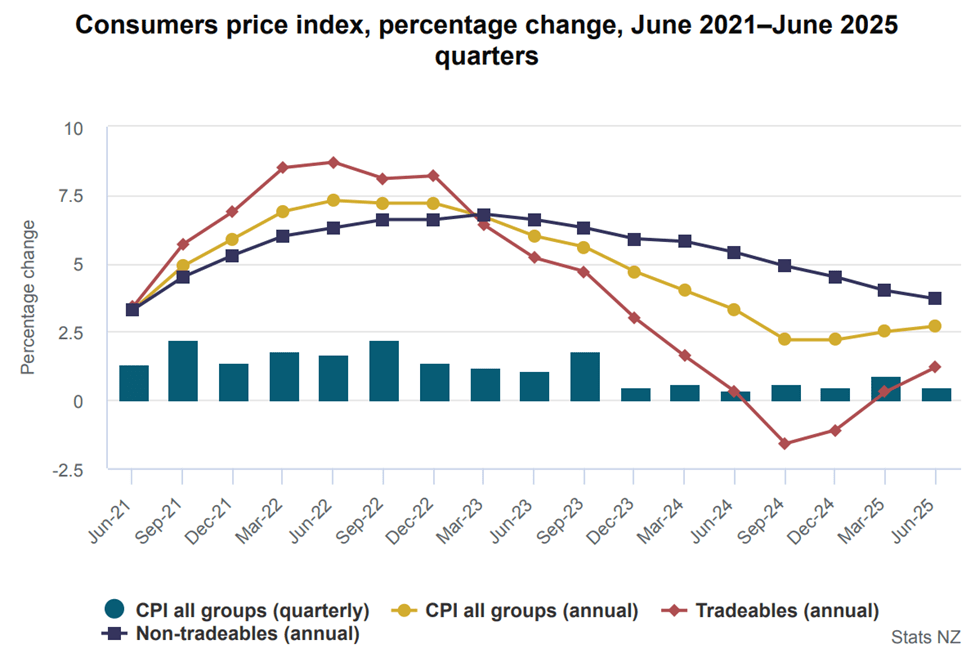
New Zealand’s CPI rose 0.5% in the June quarter and 2.7% over the year, a touch hotter than the RBNZ’s 2.6% forecast but below the 2.8% pace expected by markets. It marked a slight pickup from 2.5% in Q1 but remained within the RBNZ’s 1–3% target band for a fourth consecutive quarter. The biggest driver of the annual increase was local authority rates, up 12.2% and accounting for 13% of the rise—though that lift was captured back in the September 2024 quarter. Petrol prices fell 8% over the year, helping contain the headline result. Excluding petrol, CPI rose 3.2% annually.
Source: StatsNZ
Non-tradeable prices—which typically reflect domestic demand and supply factors—rose 0.7% for the quarter and 3.7% over the year, continuing the disinflationary trend established in early 2023 when it peaked at an annual rate of 6.8%. Tradable prices which largely reflect offshore factors increased by 0.3% for the quarter, seeing the annual pace accelerate modestly to a still-weak 1.2%.
Core inflation, excluding food, household energy and vehicle fuels, rose 0.4% on the quarter and 2.7% over the year, up from 2.6% in Q1 but still within target. The RBNZ’s sectoral factor model, its preferred measure of underlying inflation, will be released at 3pm Wellington (1pm Sydney).
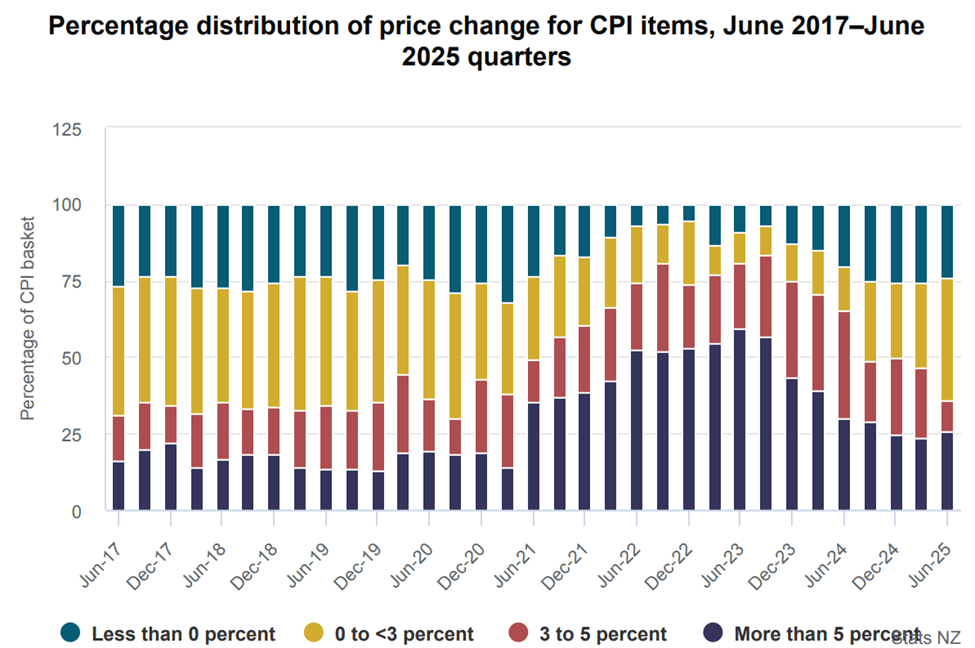
Adding to confidence that inflationary pressures remain contained despite 225 basis points worth of rate cuts from the RBNZ already this cycle, the proportion of the CPI basket with price increases of 3% or less increased to 64.3% in Q2, the highest proportion since Q3 2020.
Source: StatsNZ
Keeping RBNZ Rate Cuts in Play
Following the inflation report, swaps markets put the probability of the RBNZ reducing the cash rate by a further 25 basis points to 3% on August 20 at 85%. Looking further out, a full cut it priced by the bank’s October meeting with a 42% probability seen of a second 25-pointed by year-end.
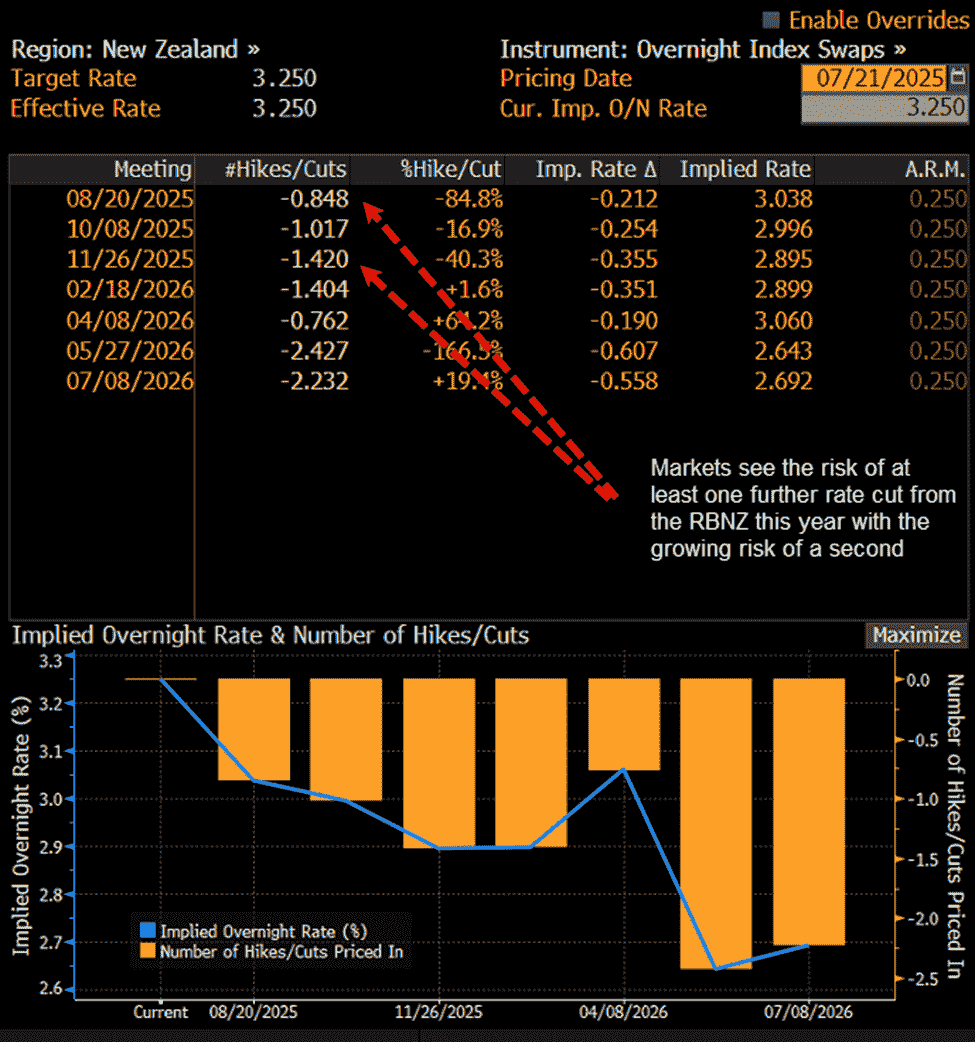
Source: Bloomberg
With markets paring expectations for multiple rate cuts from the Federal Reserve this year, it’s combined with the slightly softer Kiwi inflation report to push NZD/USD weaker in early Asian trade on Monday.
NZD/USD Remains in Downtrend
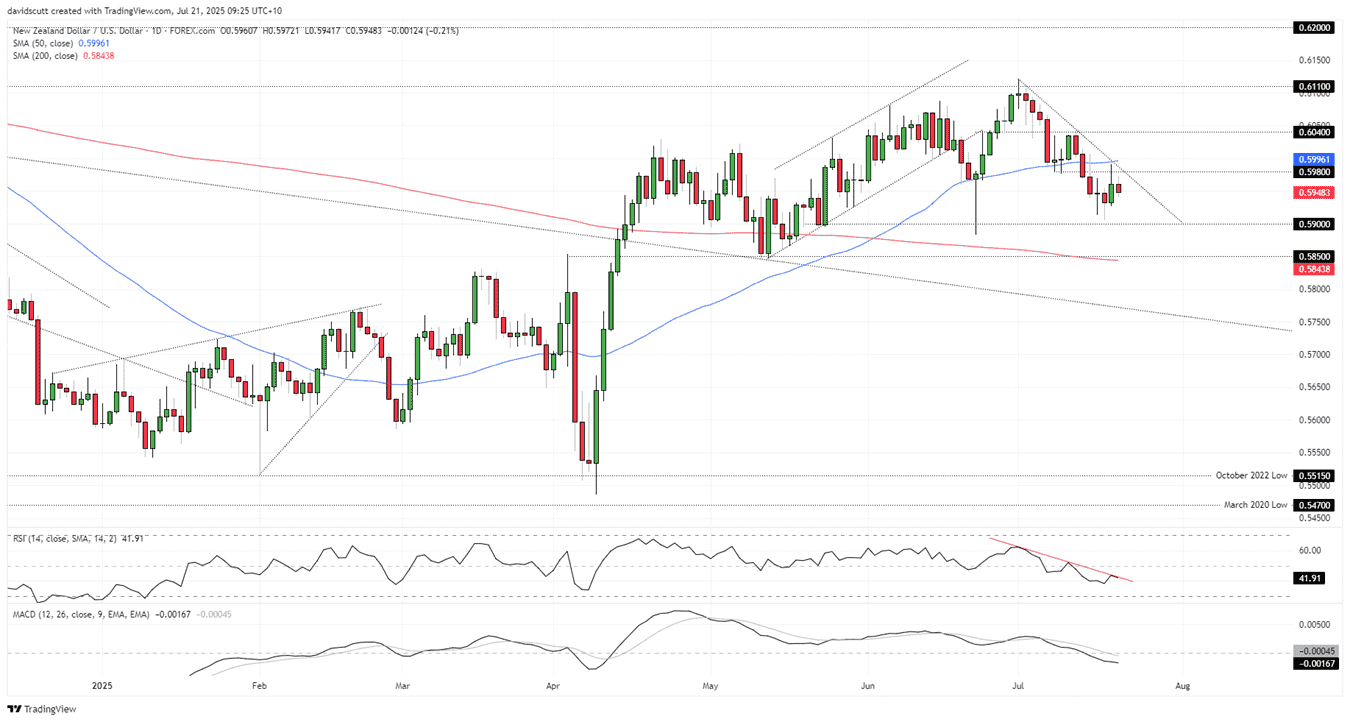
Source: TradingView
For the moment, NZD/USD remains a sell-on-rallies play, sitting in an established downtrend with momentum indicators like RSI (14) and MACD trending lower and sitting in negative territory, favouring a bearish bias.
Resistance kicks in at .5980 and again at the 50-day moving average located some 16 pips above. On the downside, bids have been noted recently ahead of support at .5900. If they were to be overrun, .5850 and the 200-day moving average would be the next two downside levels of note.
AUD/NZD Key Reversal?
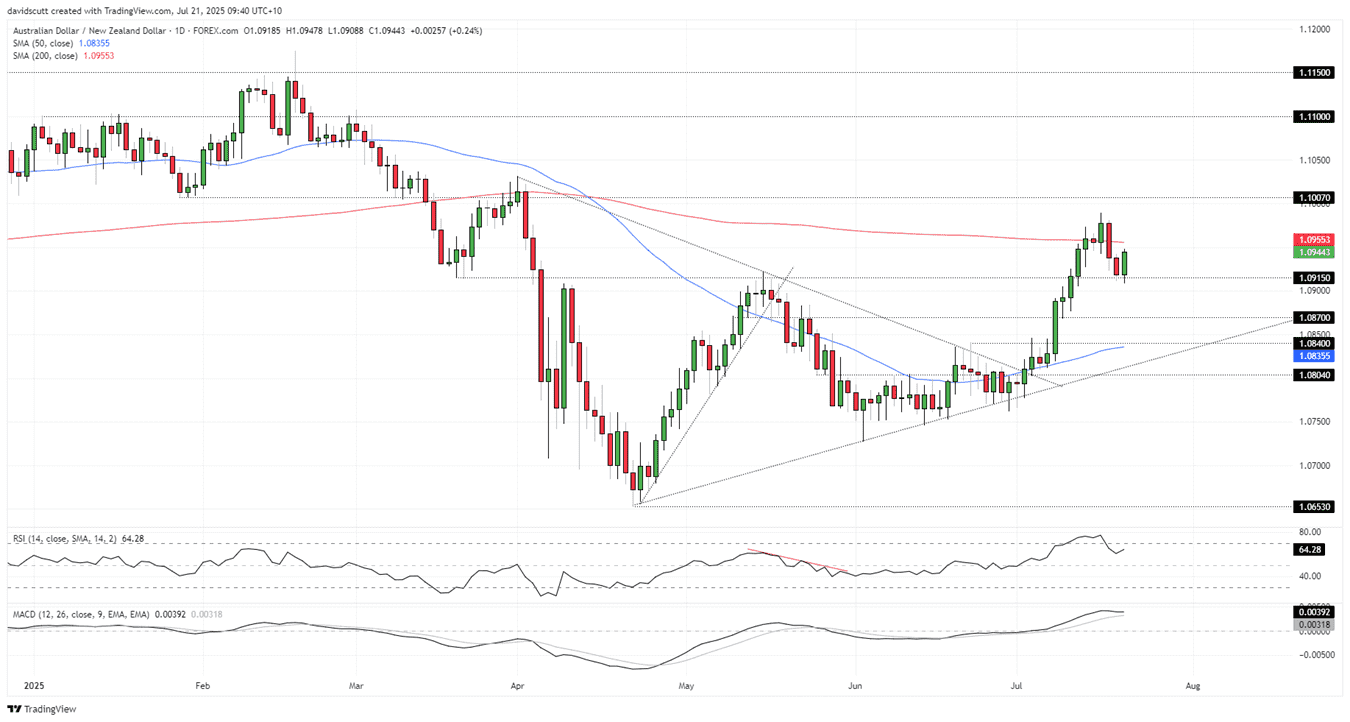
Source: TradingView
Looking briefly at AUD/NZD, the pair found buying support late last week at 1.0915 and again in early trade on Monday, with the inflation report helping to spark a reversal back above Friday’s opening level. Things could quickly change, but the daily candle will print as a key bullish reversal if it closes at or above these levels, pointing to the potential for further gains ahead should it eventuate.
Levels to watch on the topside include the 200-day moving average, Wednesday’s high around 1.0990, along with horizontal resistance at 1.1007. Benearth 1.0915, 1.0870 and 1.0840 are levels of note.
From a directional perspective, a bullish bias remains favoured with MACD and RSI (14) remaining in positive territory even with the moderation in topside momentum seen in recent days.
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Kiwi crushed as RBNZ delivers shock hold
RBNZ shocks, Kiwi collapses. NZD/USD faces a major technical test while AUD/NZD surges on diverging interest rate expectations. Is there more to come?
EUR/USD Outlook: AI sentiment returns as French debt fears fades
French debt was the market's obsession a week ago. Now, short-term correlations suggest technology sentiment may be calling more of the shots, with central bank decisions and heavyweight tech earnings threatening to accelerate the euro's decline.
FOMC Meeting Preview: Is Warsh Even Capable of Delivering a Hawkish Hold?
Fed Funds futures traders are pricing in ~90% odds that the FOMC leaves rates unchanged this week, but the big question is whether FOMC Chairman Warsh can deliver a true hawkish hike.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.