



Tankan Backs BOJ Tightening, but Yen Rate Expectations Ease
Japan’s Tankan supports further BOJ tightening, although softer rate expectations could limit support for the Japanese yen.
Share this:
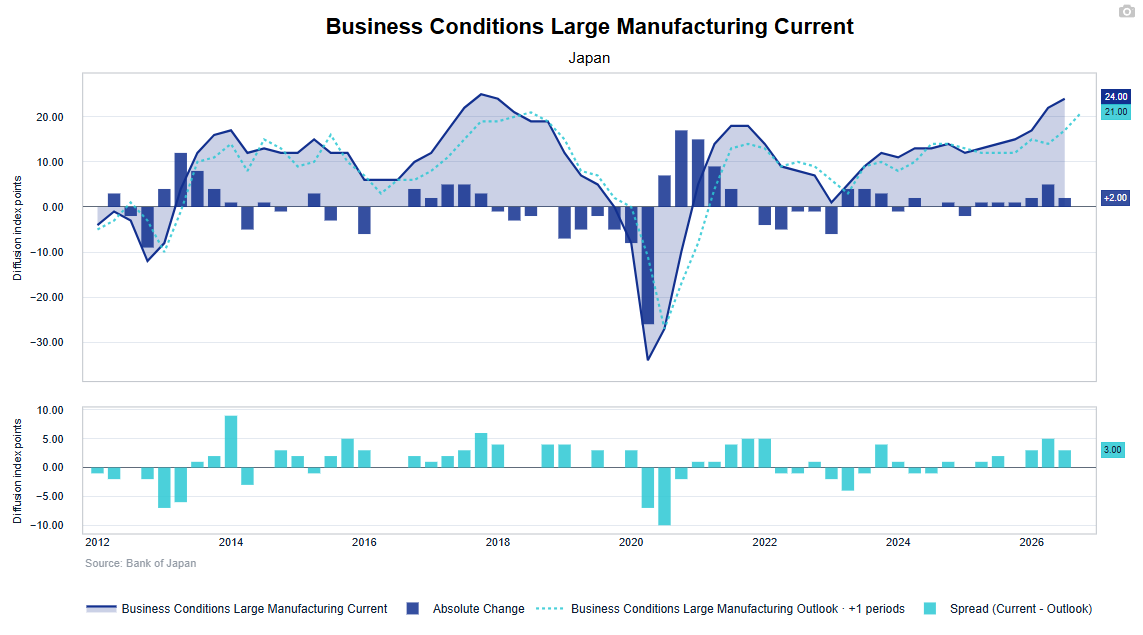
Japan’s latest Tankan kept the case for further BOJ tightening intact, with manufacturing sentiment improving, labour shortages persisting and firms expecting further price increases. Yet softer forward conditions and easing JPY OIS rates suggest traders see little urgency for the BOJ to accelerate its tightening cycle.
View related analysis:
Japan Tankan Supports BOJ Tightening as Yen Rate Pricing Softens
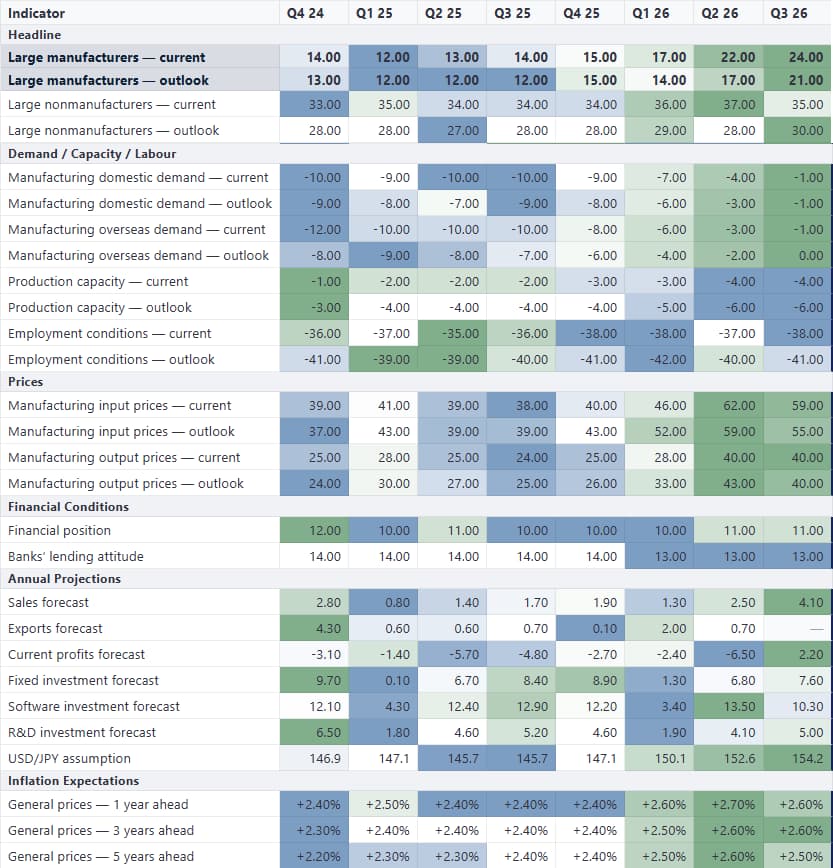
Japan’s latest Tankan report painted a reasonably constructive picture of the economy, even if the strength was far from uniform. Sentiment among large manufacturers improved to 24 from 22, its strongest reading in years, while small manufacturers strengthened to 14 from 9. The services side was less convincing, with large non-manufacturers slipping to 35 from 37 and small non-manufacturers holding at 15.
Manufacturers also expect conditions to soften over the coming quarter, with the large-manufacturing outlook at 21. Yet other parts of the survey remain relatively firm, with employment conditions staying deeply negative at -38 and signalling persistent labour shortages.
Firms Expect Further Output Price Increases
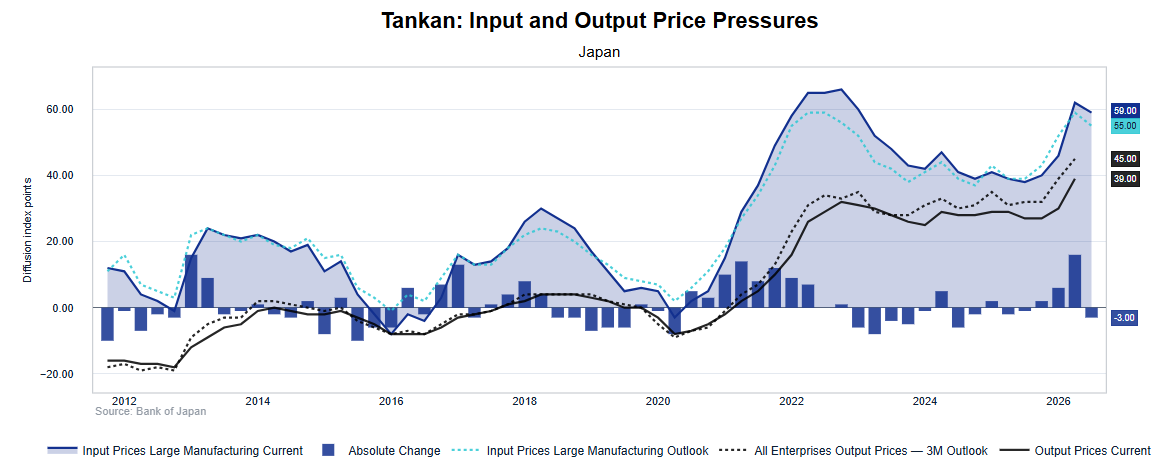
Price pressures also remain elevated, even if manufacturers expect some moderation in their input costs. The large-manufacturer input-price index eased to 59, with firms expecting it to fall to 55 next quarter. Yet the broader output-price index remains firm, with businesses expecting selling-price pressures to rise further.
That is an important detail for the BOJ. Easing upstream costs would be welcome, but rising output-price intentions suggest firms still expect to pass higher costs through to customers.

Inflation Expectations Keep BOJ Tightening in Play
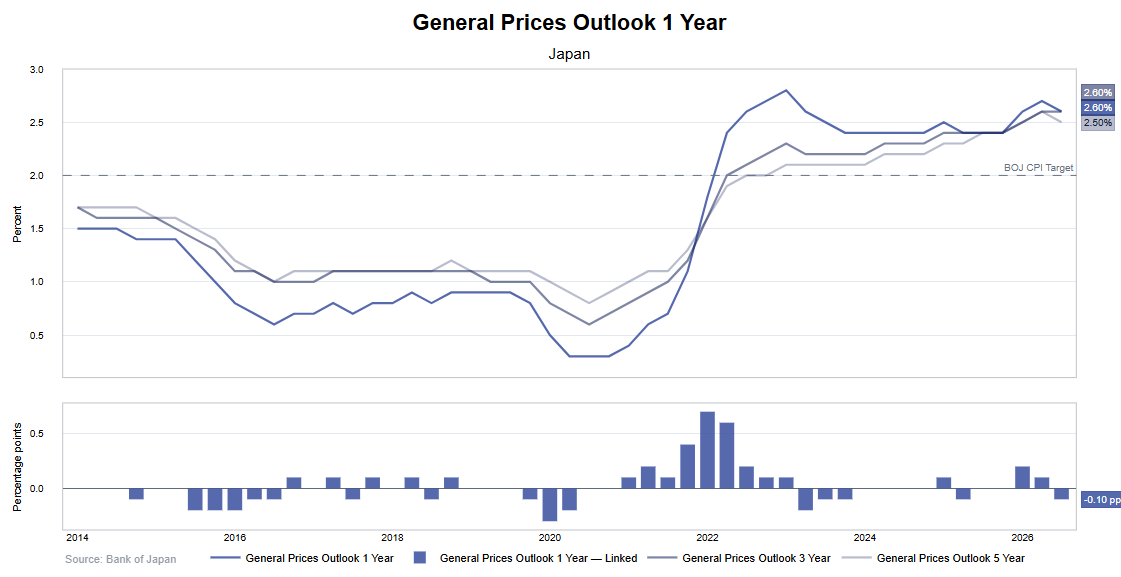
Inflation expectations also remain above the BOJ’s 2% target across the one-, three- and five-year horizons, with the one-year outlook easing only slightly to 2.6%.
Combined with persistent labour shortages and stronger output-price expectations, that should keep further policy normalisation on the table. But with inflation expectations showing little renewed acceleration and manufacturers expecting some moderation in conditions, the Tankan does not necessarily argue for a faster pace of tightening.
Softer BOJ Rate Pricing Could Limit Yen Support
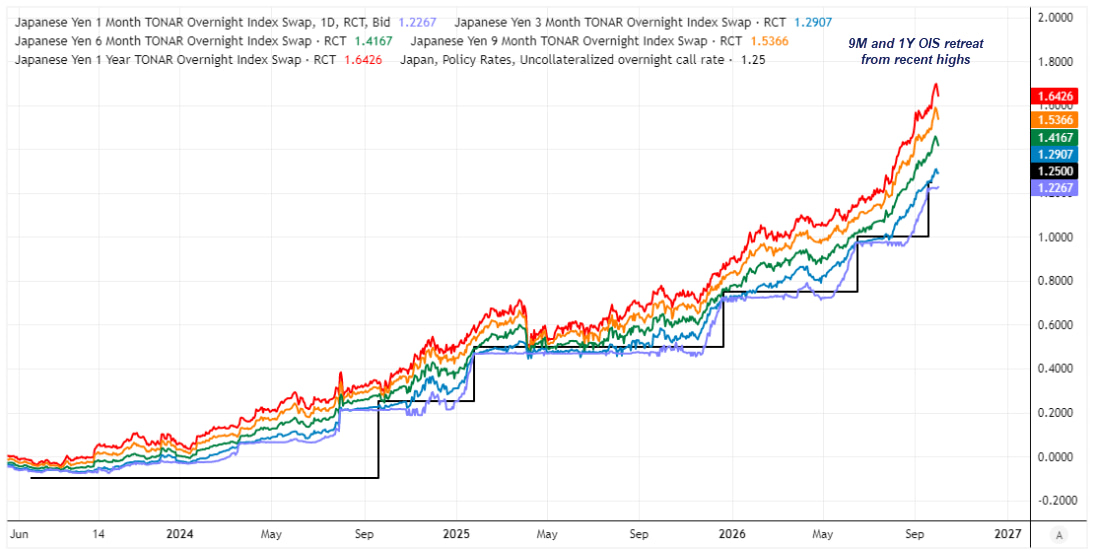
Despite the Tankan keeping further BOJ tightening in play, money markets have become less aggressive about the path ahead. JPY OIS rates have eased from recent highs, particularly across the six-month to one-year tenors, suggesting traders are trimming expectations for the pace of future hikes rather than abandoning the prospect of further tightening altogether.
That matters for the yen. Further BOJ tightening should remain supportive at the margin, but a softer implied rate path reduces one of the more obvious sources of support for JPY. A renewed rise in OIS pricing would strengthen the policy case for the yen, while further declines could leave it vulnerable even if the BOJ maintains a tightening bias.
The dashboard below summarises the main Tankan trends across business conditions, demand, labour, pricing, financial conditions and inflation expectations. It highlights a firmer manufacturing backdrop alongside persistent labour shortages, elevated price pressures and inflation expectations that remain above the BOJ’s 2% target.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

USD/CAD Forecast: Canadian Dollar Gains Ground After U.S. Midterm Elections
The trading week continues to unfold and the recovery in the Canadian dollar has once again become a relevant theme in the short term. This can be clearly seen in the recent performance of USD/CAD, which is down nearly 0.4% during the session, reflecting a consistent recovery in the CAD against the U.S. dollar.


Euro Technical Outlook: EUR/USD Support Reversal Sets Up Breakout Test Ahead of NFP 11 4 2026
Euro bulls are attempting to build on the rebound from recent lows, but pivotal resistance still stands in the way of a larger EUR/USD recovery.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.