



US CPI Preview: Amid Political Pressure, Fed Likely to Hold Through Q1 Unless Inflation Drops
The DOJ’s subpoena of Fed Chairman Powell raises risks for Fed independence, though the central bank is still seen as likely to hold interest rates unless inflation falls dramatically in Q1 - what does that mean for markets?
Share this:
US CPI KEY TAKEAWAYS:
- US CPI expectations: 2.7% y/y headline inflation, 2.7% y/y core inflation
- The DOJ’s subpoena of Fed Chairman Powell raises risks for Fed independence, though the central bank is still seen as likely to hold interest rates unless inflation falls dramatically in Q1.
- USD/JPY remains in a longer-term uptrend, tilting the odds of an upside breakout above 158.00 if inflation comes in above expectations.
When is the US CPI report?
The US CPI report for December will be released at 8:30ET (13:30 GMT) on Tuesday, January 13.
What are the US CPI Report Expectations?
Traders and economists are projecting both headline and core (ex-food and -energy) CPI to come in at 2.7% y/y. This reading, if seen, would match the headline price pressures seen last month and represent a 0.1% uptick from last month’s core CPI reading.
US CPI Forecast
As numerous Federal Reserve officials have noted in recent weeks, monetary policy is in a precarious position with inflation still above the central bank’s 2% target and signs that the labor market is cooling off.
Broadly speaking, US consumer inflation has seen its decline toward the Fed’s 2% target stall for well over a year now, with headline CPI readings stuck between the 2.3% and 3.0% y/y range for that period. Meanwhile, Core CPI, which filters out more volatile food and energy prices to better show the underlying trend in prices, remains stubbornly in the mid- to upper-2% range as well.
Despite this prolonged period of above-target inflation, the Fed’s concerns about the jobs market are still seen as more urgent and accordingly the Fed Funds rate is expected to fall further this year, though the implied probability of another cut by the central bank’s March meeting is only about 25% (markets are pricing in a hold with high confidence at the Fed meeting later this month):
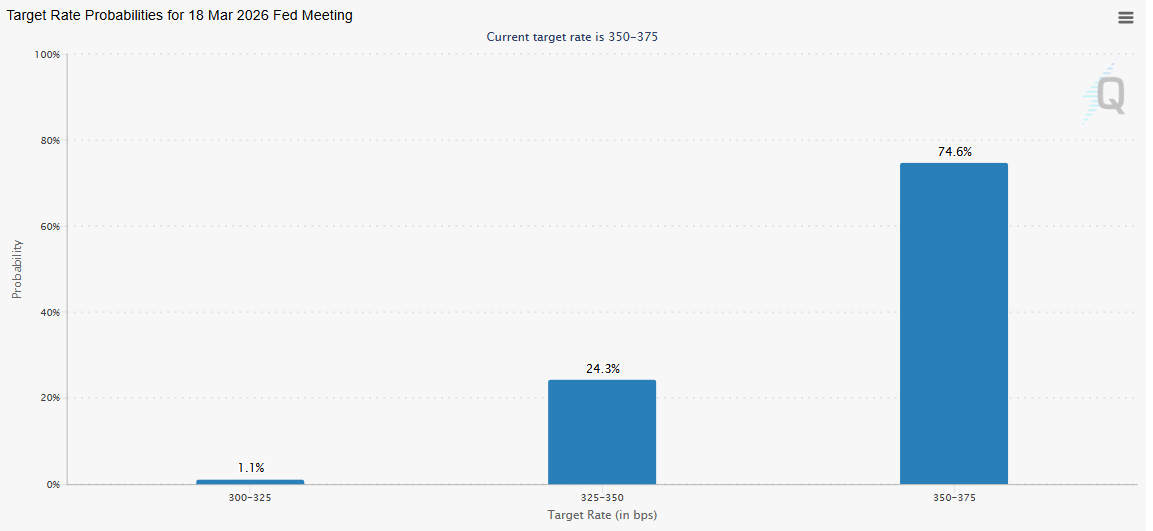
Source: CME FedWatch
This weekend’s news that the Department of Justice has subpoenaed Fed Chairman Powell raises further risks for the Fed’s independence, raising the (low) probability that President Trump will install a new Chairman at the central bank sooner rather than later. In that (still unlikely) scenario, we could see more aggressive interest rate cuts, regardless of current inflation numbers.
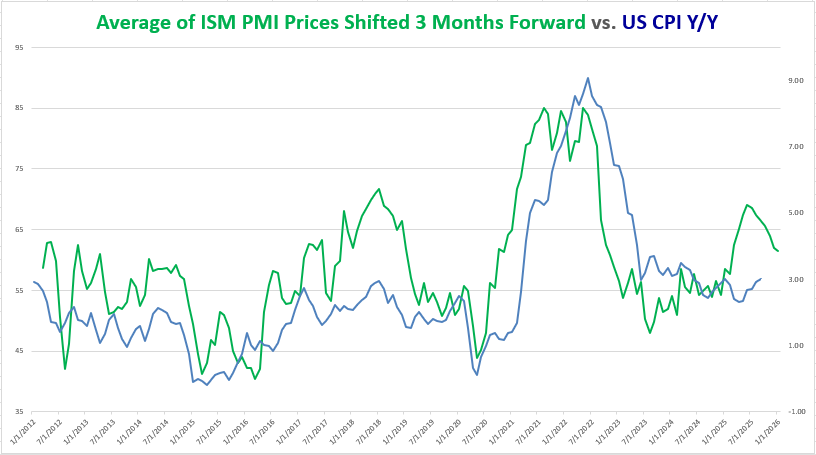
As many readers know, the Fed technically focuses on a different measure of inflation, Core PCE, when setting its policy, but for traders, the CPI report is at least as significant because it’s released weeks earlier. As we noted above, CPI has generally ticked lower so far this year, but it remains stubbornly above the Fed’s 2% target:
Source: TradingView, StoneX
Looking at the chart above, the “Prices” components of the PMI reports have started to roll over in recent months, but inflation nonetheless remains below where those readings would historically imply, hinting that there may be limited potential for inflation to fall toward 2% in the immediate term.

US Dollar Technical Analysis – USD/JPY 4-Hour Chart
Source: TradingView, StoneX
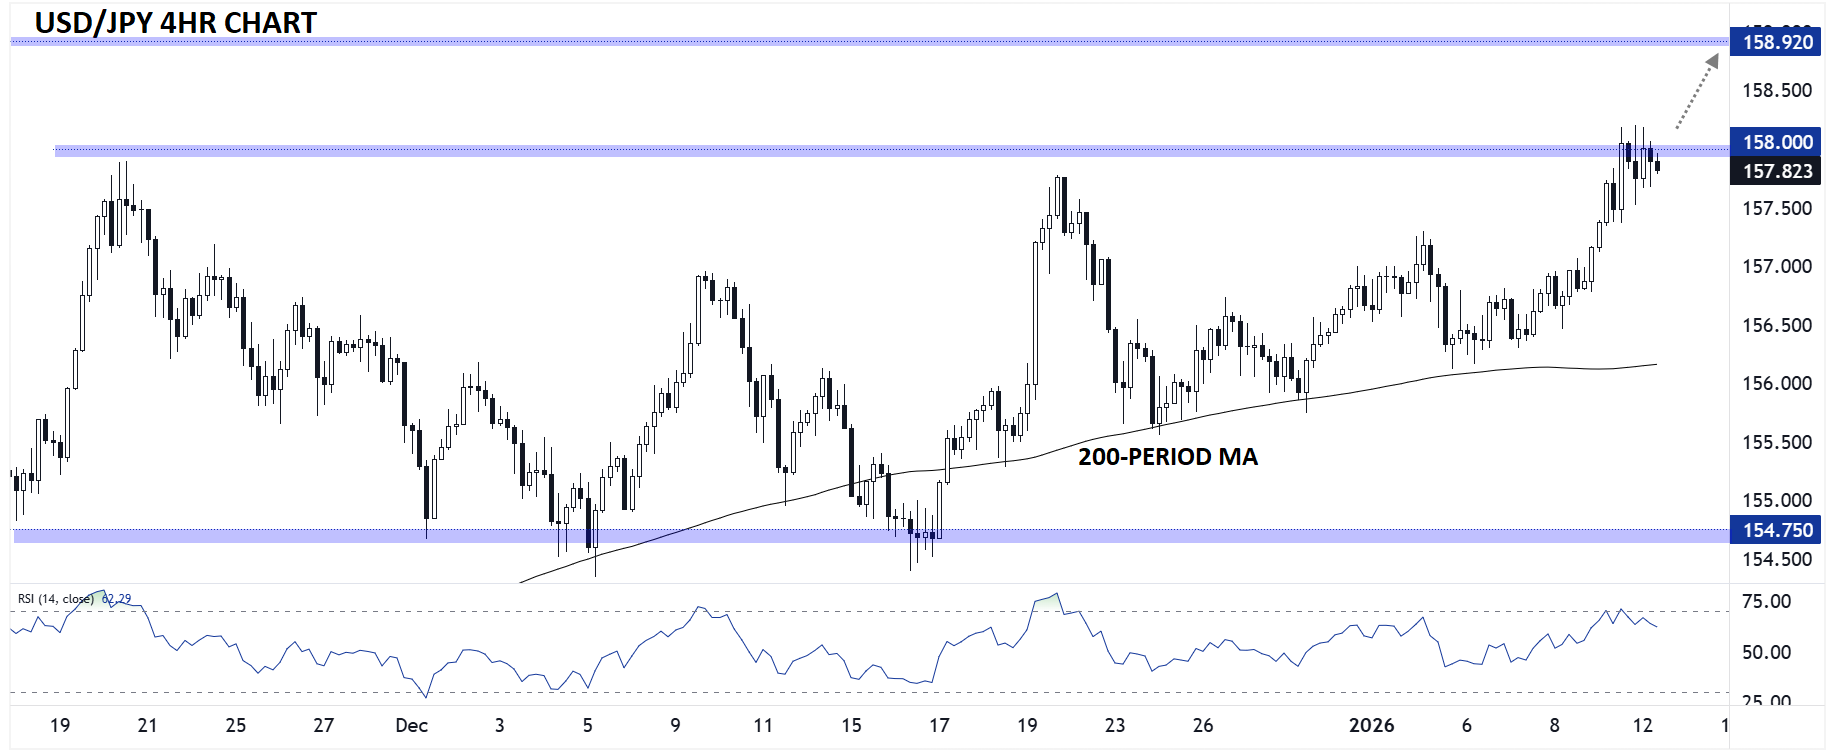
USD/JPY is in focus ahead of the CPI report. The pair typically sees the “cleanest” reaction to US data, and with USD/JPY testing previous resistance near the 158.00 level, a bullish breakout is in play if inflation comes in higher than anticipated.
Technically speaking, the pair remains in a longer-term uptrend, tilting the odds of an upside breakout (though readers should be wary of the potential for Japan’s MoF to intervene directly into the market if USD/JPY approaches 159). If inflation comes in cooler-than-anticipated, a pullback is possible as traders bring forward expectations of a Fed interest rate cut; in that scenario, a dip to 157.00 or lower is possible independent of any developments in Japan itself.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Analysis: Resilient U.S. Labor Market Continues to Pressure XAU/USD
Recent trading sessions have not been particularly favorable for gold in the short term. XAU/USD has fallen nearly 2.5% over the last three sessions, reflecting that selling pressure is once again gaining relevance and that the metal continues to struggle to regain momentum.
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.

USD/JPY Analysis: Rising U.S. Yields Leave the Yen on the Defensive
As the first week of November progresses, renewed weakness in the Japanese yen is once again becoming evident in the short term. This dynamic can be seen in the recent performance of USD/JPY, which has posted two consecutive bullish sessions and gained more than 0.7%, reflecting a return of buying interest in the dollar while the yen continues to lose momentum.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.