



US Open: Stocks rise cautiously ahead of the FOMC minutes
Stocks edge higher after steep losses yesterday as the markets fretted that the Fed could raise rates higher for longer. Will the Fed minutes fuel those fears or will they be considered outdated given the strong data came in after the Fed's February meeting?
Share this:

US futures
Dow futures +0.1% at 33170
S&P futures +0.13% at 4003
Nasdaq futures +0.22% at 12093
In Europe
FTSE -0.72% at 7920
Dax -0.05% at 15380
- Will FOMC minutes fuel bets of more rate hikes?
- Baidu rises 7% after upbeat results
- USD rises EUR & GBP show resilience
- Oil falls for a third day on fears of rate hikes slowing growth
FOMC minutes in focus
US stocks are set to open modestly higher after steep losses in the previous session and as investors look ahead to the release of the minutes from the February Fed meeting for more clues on the future path of rate hikes.
While January proved to be a strong month for US equities, February has been a flop, with the S&P500 down almost 2% so far this month. A series of stronger-than-expected U.S. economic data, including hotter-than-expected inflation, a blowout jobs report, and a rebound in business activity to an 8 month high, has fuelled bets that the Federal Reserve will need to raise interest rates higher for longer in order to tame inflation.
In the February meeting, the Fed slowed the pace of rate hikes to 25 basis points. Investors will be scrutinizing the minutes for clues as to how much support there was for a 50 basis point rate hike. This comes after two hawkish policymakers have recently said they would prefer a return to outsized hikes. Any sense of an more hawkish stance at the Fed could pull stocks and gold lower while lifting the USD.
It’s worth keeping in mind that the stronger data was released after the February fed meeting took place. As a result, the market may consider that the meeting minutes are already outdated.
Corporate news
Palo Alto rises pre-market after the cyber security firm posted better-than-expected Q2 results and raised its earnings guidance.
Baidu ADRs surge 7% Chinese search engine reported a big jump in Q4 profits and announced a $5 billion share buyback programme. Net income almost tripled to RMB 4.95 billion.
Nvidia, eBay an Lucid are due to report after the close.
Where next for the S&P500?
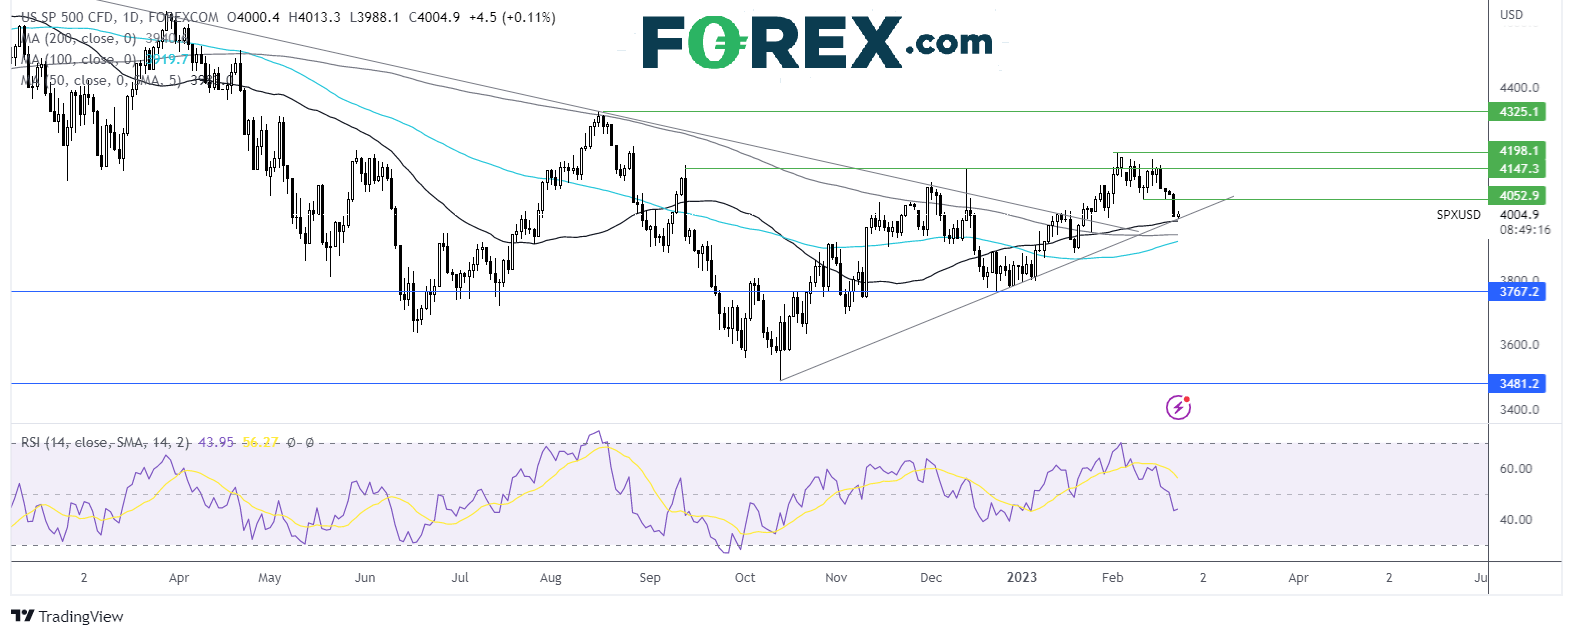
The S&P500 broke aggressively below the 4050 support, which had been respected across the past two weeks, and then the 4000 psychological level to test support at 3985. This is a confluence of the 50 sma and the multi-month rising trendline support, which could prove to be a tough nut to crack. A break below here exposes the 200 sma at 3940. Below here the 50 sma could offer support at 3920 before the December low at 3760 comes into play. On the flip side, should buyers successfully defend the 3985 level, the next hurdle would be 4050, last week’s low.
FX markets – USD rises, GBP, EUR hold steady
The USD is rising, extending gains from the previous session as investors look cautiously ahead to the release of the FOMC minutes. A hawkish tone, coupled with strong US data yesterday, could see the US dollar index rise back above 104.00
EUR/USD is showing some resilience against the stronger U.S. dollar after German Ifo business climate data improved in February to 91.1. The data comes after figures yesterday showed that the German private sector returned to growth thanks to a sharp pickup in service sector activity. The improving trend in business sentiment supports further rate hikes from the ECB.
GBP/USD is flat above 121, holding onto yesterday's strong gains following the unexpected return to growth in business activity. However, sterling hasn't been able to extend those gains as attention shifts to the Northern Ireland post-Brexit trade agreement impasse. While the UK & the EU are moving closer to resolving the dispute, discussions for new terms are still ongoing.
EUR/USD -0.01% at 1.0645
GBP/USD +0.01% at 1.2110
Oil falls for a third day
Oil prices are heading lower for a third consecutive day amid concerns about a more hawkish Fed and higher interest rates, which could dampen the oil demand.
Looking ahead, the API oil inventory data is due and is expected to show another build in inventories, which would draw more attention to perceived demand concerns in the US, the world’s largest consumer of oil.
That said, losses are being limited by upbeat data from Europe, which suggests that the region could avoid a recession thanks to surprisingly strong business activity growth. The reopening of the Chinese economy also continues to lend support to oil prices.
China’s oil demand is expected to reach a record high this year. Furthermore, imports could rise between 500k to 1 million bpd to 11.8 million bpd.
WTI crude trades -0.5% at $75.90
Brent trades at -0.47% at $82.34
Looking ahead
19:00 Fed minutes
US futures
Dow futures +0.1% at 33170
S&P futures +0.13% at 4003
Nasdaq futures +0.22% at 12093
In Europe
FTSE -0.72% at 7920
Dax -0.05% at 15380
Learn more about trading indices
- Will FOMC minutes fuel bets of more rate hikes?
- Baidu rises 7% after upbeat results
- USD rises EUR & GBP show resilience
- Oil falls for a third day on fears of rate hikes slowing growth
FOMC minutes in focus
US stocks are set to open modestly higher after steep losses in the previous session and as investors look ahead to the release of the minutes from the February Fed meeting for more clues on the future path of rate hikes.
While January proved to be a strong month for US equities, February has been a flop, with the S&P500 down almost 2% so far this month. A series of stronger-than-expected U.S. economic data, including hotter-than-expected inflation, a blowout jobs report, and a rebound in business activity to an 8 month high, has fuelled bets that the Federal Reserve will need to raise interest rates higher for longer in order to tame inflation.
In the February meeting, the Fed slowed the pace of rate hikes to 25 basis points. Investors will be scrutinizing the minutes for clues as to how much support there was for a 50 basis point rate hike. This comes after two hawkish policymakers have recently said they would prefer a return to outsized hikes. Any sense of an more hawkish stance at the Fed could pull stocks and gold lower while lifting the USD.
It’s worth keeping in mind that the stronger data was released after the February fed meeting took place. As a result, the market may consider that the meeting minutes are already outdated.
Corporate news
Palo Alto rises pre-market after the cyber security firm posted better-than-expected Q2 results and raised its earnings guidance.
Baidu ADRs surge 7% Chinese search engine reported a big jump in Q4 profits and announced a $5 billion share buyback programme. Net income almost tripled to RMB 4.95 billion.
Nvidia, eBay an Lucid are due to report after the close.
Where next for the S&P500?
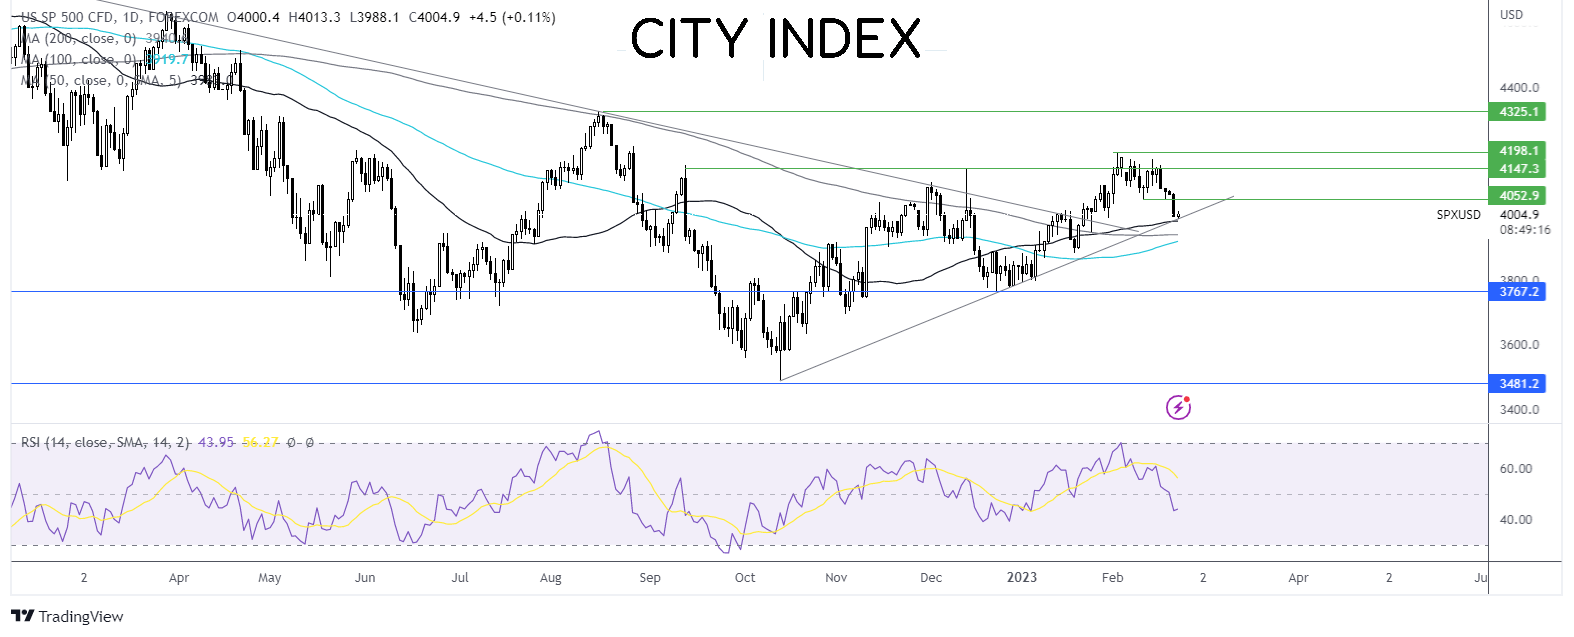
The S&P500 broke aggressively below the 4050 support, which had been respected across the past two weeks, and then the 4000 psychological level to test support at 3985. This is a confluence of the 50 sma and the multi-month rising trendline support, which could prove to be a tough nut to crack. A break below here exposes the 200 sma at 3940. Below here the 50 sma could offer support at 3920 before the December low at 3760 comes into play. On the flip side, should buyers successfully defend the 3985 level, the next hurdle would be 4050, last week’s low.
FX markets – USD rises, GBP, EUR hold steady
The USD is rising, extending gains from the previous session as investors look cautiously ahead to the release of the FOMC minutes. A hawkish tone, coupled with strong US data yesterday, could see the US dollar index rise back above 104.00
EUR/USD is showing some resilience against the stronger U.S. dollar after German Ifo business climate data improved in February to 91.1. The data comes after figures yesterday showed that the German private sector returned to growth thanks to a sharp pickup in service sector activity. The improving trend in business sentiment supports further rate hikes from the ECB.
GBP/USD is flat above 121, holding onto yesterday's strong gains following the unexpected return to growth in business activity. However, sterling hasn't been able to extend those gains as attention shifts to the Northern Ireland post-Brexit trade agreement impasse. While the UK & the EU are moving closer to resolving the dispute, discussions for new terms are still ongoing.
EUR/USD -0.01% at 1.0645
GBP/USD +0.01% at 1.2110
Oil falls for a third day
Oil prices are heading lower for a third consecutive day amid concerns about a more hawkish Fed and higher interest rates, which could dampen the oil demand.
Looking ahead, the API oil inventory data is due and is expected to show another build in inventories, which would draw more attention to perceived demand concerns in the US, the world’s largest consumer of oil.
That said, losses are being limited by upbeat data from Europe, which suggests that the region could avoid a recession thanks to surprisingly strong business activity growth. The reopening of the Chinese economy also continues to lend support to oil prices.
China’s oil demand is expected to reach a record high this year. Furthermore, imports could rise between 500k to 1 million bpd to 11.8 million bpd.
WTI crude trades -0.5% at $75.90
Brent trades at -0.47% at $82.34
Learn more about trading oil here.
Looking ahead
19:00 Fed minutes
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Update: SPX Records Its Biggest Selloff of the Year Ahead of NFP
The trading week has not been particularly favorable for risk appetite in the short term, and this is now becoming increasingly evident in the performance of the S&P 500. During today's session, the index is down nearly 4.2%, marking its largest intraday decline of 2026.
Canadian Dollar Short-term Outlook: USD/CAD Plunge Stalls at Pivotal Support—Range Break in Focus 11 5 2026
Friday’s U.S. and Canadian employment reports could trigger a decisive USD/CAD move as bulls and bears battle for control at critical support.

US Dollar Technical Outlook: DXY Bulls Fight to Hold Critical Support Ahead of NFP 11 5 2026
DXY bulls are attempting to defend a pivotal technical threshold, with the next reaction likely to determine whether the broader recovery survives.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.