



NFP Recap Multigenerational Low in Unemployment Still Not Enough to Raise Wages
As my colleague Fawad Razaqzada astutely highlighted in yesterday’s NFP Preview report, “wage growth has taken on increased importance than the actual jobs number given concerns about rising levels of inflation and in turn interest rates.” That dynamic is playing out in spades as traders digest today’s jobs report.
Share this:

As my colleague Fawad Razaqzada astutely highlighted in yesterday’s NFP Preview report, “wage growth has taken on increased importance than the actual jobs number given concerns about rising levels of inflation and in turn interest rates.” That dynamic is playing out in spades as traders digest today’s jobs report.
On a headline basis, the US economy created 134k new jobs in September, well below the median expectation of +185k jobs. While the headline figure looks disappointing, it was more than made up for by positive revisions to the previous two months’ reports, which totaled +87k jobs. In addition, a subcategory of the accompanying household survey showed that employees “not at work due to bad weather” (read: Hurricane Florence, primarily) came in at nearly 300k, well above the historical average for September, though below last year’s anomalous result .
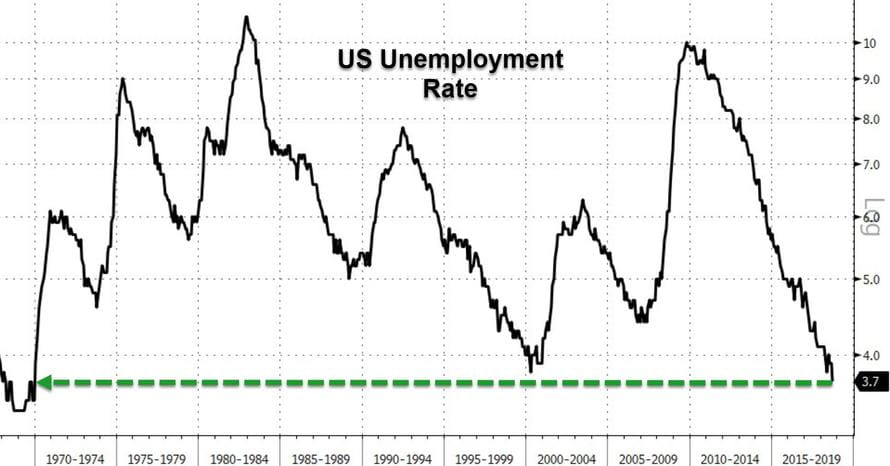
In an event that few observers thought they’d see in their lifetime (yours truly included), the unemployment rate dropped to just 3.7%, its lowest level in 49 years! Of note, this drop was not driven by a decline in the labor force participation rate, which held steady at 62.7%. Taken together, these data points suggest that the overall quantity of jobs created remains strong, despite the slightly disappointing headline figure.
Source: Zerohedge
When it comes to the quality of those jobs, there’s not much to write home about. Average hourly earnings rose 0.3% m/m, as expected, causing the year-over-year growth rate in wages to tick down to 2.8%. This isn’t the 3.0%+ rate that bulls were hoping for, but wage growth is nonetheless holding steady near the top of the post-GFC range. Meanwhile, average hours worked held steady at 34.5 per week.
For the market, and the Federal Reserve, the big takeaway from today’s jobs figures is that the labor market still appears to have plenty of “slack.” In other words, job growth continues apace, without a corresponding increase in wages, a full nine-plus years into the recovery from the Great Financial Crisis. As the Federal Reserve continues to normalize interest rates toward their long-term “neutral” level, today’s jobs report may, at the margin, consider raising interest rates slightly more slowly in 2019 than if we had seen job growth slow and wage growth rise further.
Market Reaction
As we go to press, US stocks are poised for a flat-to-slightly-positive open while the US dollar is falling by 15-20 pips against most of its major rivals in the wake of the jobs data. The yield on the benchmark 10-year Treasury bond is rising by 3-4 bps to 3.22%, building on its gains from earlier this week. Both gold and oil (WTI) are trading slightly higher on the day.




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Outlook: Historic yield squeeze leaves Aussie bears in control
Australian bond yields have fallen below their US equivalents as the Fed's hawkish repricing gathers momentum. With the Aussie weakening broadly, technical signals suggest sellers remain in control.
GBP/USD approaches breaking point as US yields surge
A historic repricing of US interest rate expectations has propelled the dollar higher, leaving GBP/USD testing a crucial support level ahead of UK GDP.
EUR/USD, DXY, Silver Price Outlook: Bullish Rebounds on Hold?
EUR/USD, DXY, Silver Price Outlook: Bullish rebounds across currency markets, precious metals, and risk assets are facing renewed pressure as U.S. CPI comes in above expectations and oil-tanker attacks persist in the Strait of Hormuz.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.