the US out on Monday for Presidents’ Day and China celebrating Spring Festival all week, it makes sense to focus on European markets to start the week off. So the FTSE 100 forecast is in focus for this week’s weekend indices outlook. We have plenty of UK, European and US earnings to look forward to as the week progresses, while key data from the UK and US will make rate cut expectations a key talking point on both sides of the pond.
The week that was
It was a pretty choppy week for the major indices last week, with US tech weakness being the highlight but overall nothing too significant to report with major indices holding key support levels. A strong US jobs report was followed by US inflation data coming in weaker than expected at 2.4% year-on-year, falling relatively sharply from the previous month’s 2.7% reading.
That soft inflation print has pushed markets to start pricing in more aggressive Fed easing, again, with traders seeing around a 30% chance of a rate cut by April, and more than an 80% chance of easing by June.
Meanwhile, the FTSE 100 continued to trade near record highs as expectations for Bank of England rate cuts increased thanks to some further signs of weakness in the UK economy, while the resulting weakness in the pound also helped the cause. The UK economy certainly ended 2025 on a fairly weak note. Construction and business investment were particularly soft, which highlights ongoing growth concerns. However, this wasn’t really new information for the Bank of England. Policymakers already knew the economy was slowing, which explains why the pound didn’t sell off aggressively after the data. That said, the pound remains fundamentally fragile, especially against commodity dollars like the Aussie or kiwi.
FTSE 100 forecast: Looking ahead to the new week
Looking ahead, we’ve got plenty of market-moving data coming up. In the UK, we get wages data on Tuesday and CPI on Wednesday – both crucial for shaping expectations around future BoE rate cuts, putting the FTSE 100 forecast into focus. Among other data highlights, we’ll see global PMIs, followed by US GDP and core PCE inflation, the Fed’s preferred inflation measure, all on Friday.
Top 10 Company Earnings This Week
The results of UK companies will undoubtedly impact the FTSE 100 forecast in the week ahead. But it is not just UK companies reporting. Looking at the broader market, we have some interesting earnings coming up from other major markets too.
Here’s the top 10 list of U.S. & European companies reporting earnings in the week ahead:
Tuesday, Feb 10
1. BP
2. AstraZeneca
3. Barclays
4. S&P Global
5. The Coca-Cola Company
6. Robinhood Markets
Wednesday, Feb 11
7. Cisco Systems
8. McDonald’s
Thursday, Feb 12
9. Unilever
10. Anheuser-Busch InBev
What are the key data highlights this week?
Monday, Feb 9
- Japan GDP
- Eurozone industrial production
Tuesday, Feb 10
- UK Jobless claims, average earnings index and employment data
- German ZEW Economic Sentiment
- Canadian CPI
- US Empire State Manufacturing Index
Wednesday, Feb 11
- RBNZ interest rate decision - no change expected
- UK CPI - expected to ease to 3.0% from 3.4%
- US durable goods orders, housing starts, building permits and FOMC minutes
Thursday, Feb 12
- Australia employment data
- US Jobless Claims, Philly Fed Manufacturing Index and Pending Home Sales
Friday, Feb 13
- Global PMIs
- UK retail sales
- Canada retail sales
- US Advance GDP, Core PCE Price Index and New Home Sales
FTSE 100 Key levels
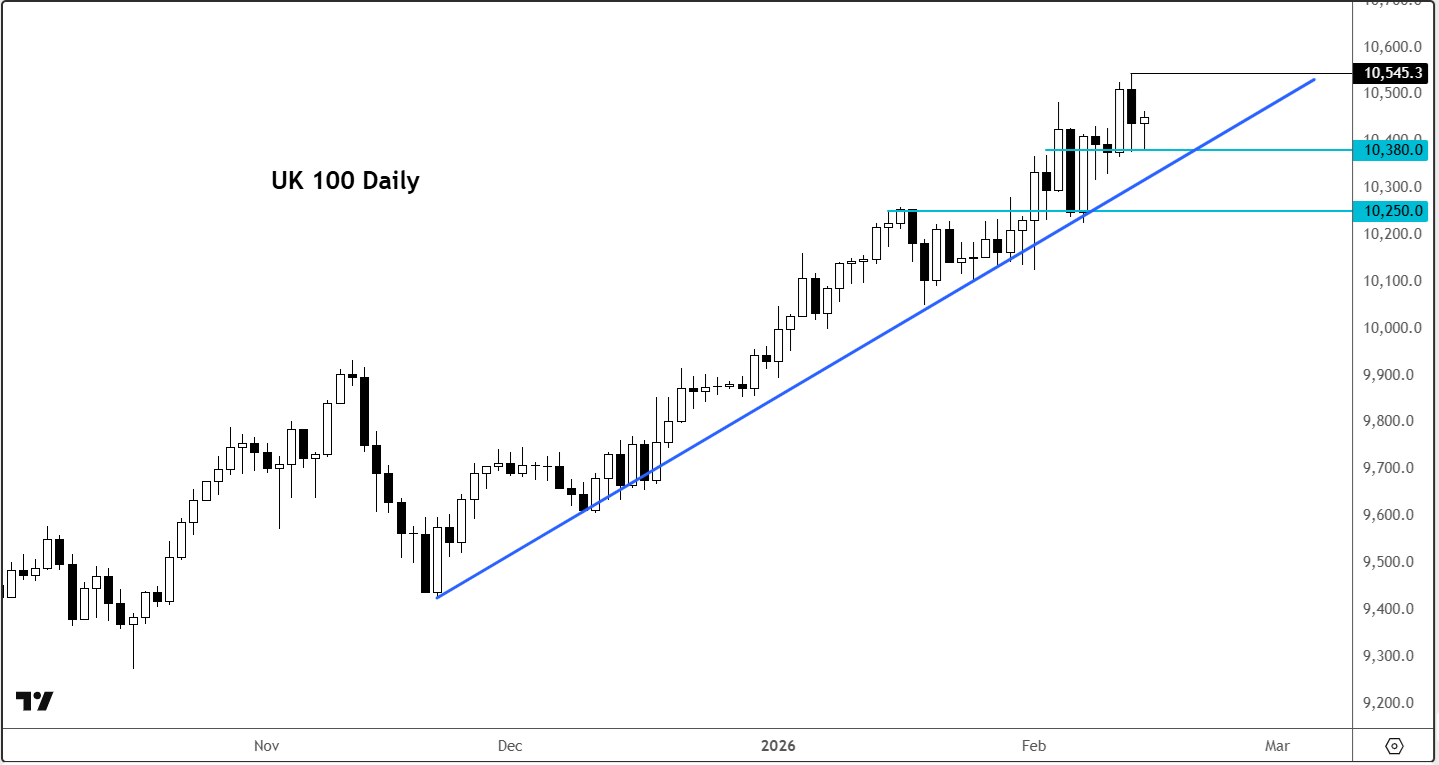
Aggressive recent dip buying means we don’t have to look too far below to identify key short term levels, unless an unexpected stimulus drives markets sharply lower. Among support levels to watch, 10,400 is important, below which 10,375 comes into focus next, followed by 10,300 and 10,280. Resistance is in short supply, with the exception of 10,480ish - above which is the all time high at 10,545.

What about the pound?
Everything you need to know in this video:
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R