US futures
Dow futures -0.13%, S&P futures -0.14% & Nasdaq futures -0.13%
In Europe
FTSE -0.02% & DAX -0.35%
- U.S. stocks hover around record highs
- President Trump rejects Iran's response to the U.S. peace proposal.
- U.S. inflation data and the Trump-Jinping summit are in focus this week.
- Oil jumps as hopes for a US-Iran deal fade

US stocks hover near record highs despite renewed US-Iran tensions
US stocks are trading near record highs at the start of the week despite Donald Trump rejecting Iran’s latest peace counterproposal, as enthusiasm surrounding AI and strong earnings momentum continue to support risk appetite.
The S&P 500 is now up 16.5% from this year’s low and has posted eight consecutive weeks of gains — its longest winning streak since October 2024.
Equities continue to trade at elevated levels even as the US-Iran conflict enters its eleventh week and the Strait of Hormuz remains effectively closed. Markets had rallied on hopes that the conflict would soon move towards resolution. However, the absence of a deal highlights the fragility of the geopolitical backdrop.
Oil prices are rising again, pushing Treasury yields higher and limiting further upside in equities.
In the US, the bullish case for stocks has been underpinned by optimism surrounding geopolitics, strong corporate earnings growth, and renewed enthusiasm around the AI trade. Until one of those drivers weakens materially, the broader trend in equities appears biased to the upside.
Attention this week will remain on developments between Washington and Tehran, alongside US inflation data due tomorrow. CPI is expected to tick higher to 3.4% year-on-year from 3.3%. Combined with Friday’s stronger-than-expected non-farm payrolls report, the data supports expectations that the Federal Reserve will leave interest rates unchanged for now.
Investors will also closely watch Trump’s upcoming meeting with Xi Jinping in Beijing later this week. Markets are hoping China could use its influence over Tehran to help de-escalate tensions and support the reopening of the Strait of Hormuz.
Corporate movers
Moderna was up almost 9% after a US citizen tested positive for hantavirus. Last week, the biotech firm announced it was in the early stages of developing a vaccine targeting the virus.
monday.com is rising 26% after reporting Q1 earnings and revenue ahead of expectations. The company said the launch of its AI platform helped drive revenue growth of 24% year-on-year to $351.3 million.
Intel is up 5.5% as momentum following its April Q1 earnings report continues. The stock has now nearly doubled from levels seen before its earnings release after the close on April 23.
Micron Technology is gaining another 6% on Monday after surging 15% on Friday. An AI-driven memory shortage has helped lift the stock more than 77% over the past month.
Energy stocks are also moving higher after Iran rejected the latest US peace proposal and Donald Trump dismissed Tehran’s counteroffer, boosting oil prices and supporting the sector.
S&P 500 forecast – Technical analysis
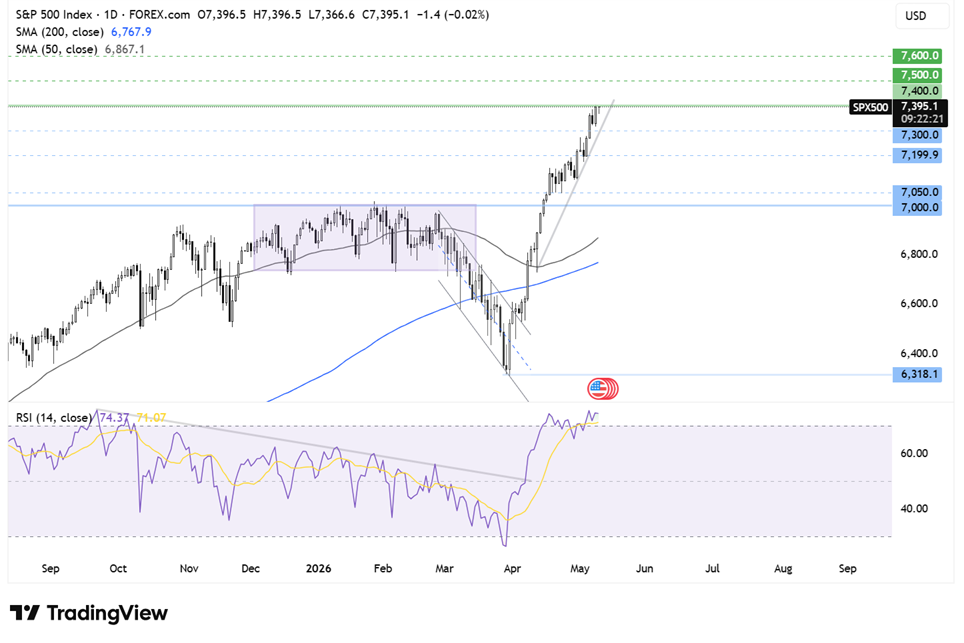
The S&P 500 has extended its rebound from the 6,310 low, climbing to a fresh record high around 7,400, where the index is consolidating at the start of the week.
The RSI remains firmly in overbought territory, suggesting that some consolidation or a short-term pullback could occur before the next move higher.
Buyers will look for a break above 7,400 to extend gains towards 7,500 and potentially 7,600.
Immediate support is seen at 7,300, near the round number and rising trendline support. Below here, attention turns to 7,200, followed by 7,050, the April 23 swing low. A break below 7,000 would be needed to meaningfully weaken the broader bullish trend.
FX markets – USD rises, GBP/USD falls
The US dollar is strengthening alongside Treasury yields as hopes for an imminent peace agreement between the US and Iran continue to fade, keeping oil prices elevated and reinforcing inflation concerns.
EUR/USD is edging lower amid the firmer dollar and rising crude prices. Europe’s dependence on imported energy is reviving stagflation concerns as higher oil costs threaten growth and inflation simultaneously. Attention later this week will turn to final German CPI data and Eurozone GDP figures.
GBP/USD is also under pressure as sterling weakens against the stronger dollar and political uncertainty in the UK intensifies. Keir Starmer is facing growing pressure following Labour’s poor local election performance, with increasing unrest inside the party weighing on sentiment towards the pound.
Oil rises as hopes for a breakthrough fade
Oil prices are rising again on Monday after Trump described Iran’s response to the latest US peace proposal as unacceptable, raising concerns over the fragile ceasefire while the Strait of Hormuz remains shut.
WTI crude briefly rose above $100 per barrel before easing back towards $97, still up around 2% on the day.
Crude had fallen roughly 6% last week on hopes the conflict could move towards resolution and allow shipping through the Strait of Hormuz to normalise. Those expectations have weakened sharply at the start of the new week.
Markets will now focus on Trump’s summit with Xi later this week for any indication China may push Tehran towards de-escalation and support the reopening of the key shipping route.