





AUD/USD weekly outlook: Upside may be capped, but a cycle low could be in
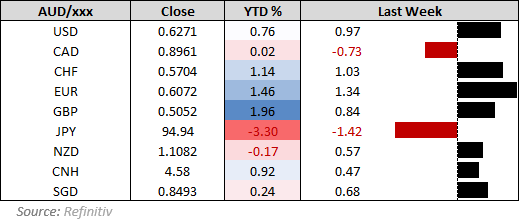
The breakout to a 5-year low on Monday was short lived, before AUD/USD went on to recover as much as 3.5% by the day's high. Given the extended bearish period seen since Q4, perhaps an important cycle low has been set.
Share this:

- Monday’s 5-year low amid tariff headlines was short-lived, with AUD/USD recovering as much as 3.5% last week
- Hawkish BOJ bets and safe-haven flows into the Japanese yen has sent AUD/JPY down to a 21-week low
- In the last full week before the RBA’s interest rate decision, money markets effectively see a 25bp cut as a done deal next week
- US CPI and Jerome Powell’s semi-annual testimony to the House Financial Services Committee are the calendar highlights
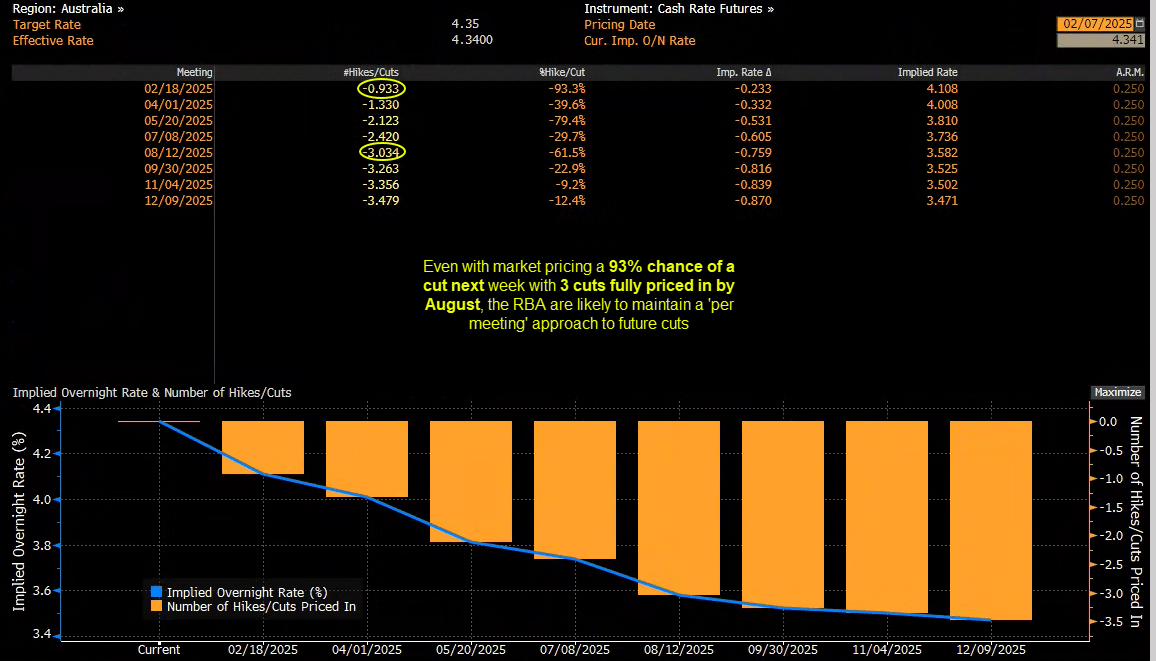
This is the last full week before the RBA’s next interest rate decision, though I do not see any data points of significance that could change whichever route the RBA takes. Money markets continue to imply a cut is a done deal, with RBA cash rate futures pricing in a 95% chance of a 25bp cut on February 18. Bloomberg estimates a February cut at 93%, is fully priced in for April with another fully priced for May. Three cuts are expected to have arrived by August.
While a cut is favoured, I’m not convinced it really is a slam dunk given the robust employment figures and pockets of strength elsewhere. I am also doubtful of three cuts arriving by August. At the very least they may signal an April cut at their next meeting. But if they do cut next week, future cuts are likely to be decided on a ‘per meeting’ basis. We should also be vigilant for headline, in case they decide to telegraph any incoming cut via media interviews this week, particularly over the weekend (which used to be standard practice under Governor Lowe).
New Zealand accounts for the baulk of the more interesting data between the antipodean nations, with recent employment data opening the door for another 50bp cut. So, any further signs of weakness in NZ retail sales, business PMI or (most importantly) inflation expectations could seal the deal for a jumbo cut, and help AUD/NZD catch a bid.
The early hours of Thursday morning will be the highlight of the week from the calendar, with US inflation data for January released 90 minutes ahead of Jerome Powell’s testimony to the House Financial Services Committee. With that said, it is usual for Powell to release his pre-prepared remarks on the day, so this could prompt some movement for currencies late on Wednesday night. Clearly, traders will be looking for clues over policy and whether the Fed deem Trump’s trade wars to be inflationary. I expect Powell to strike a cautious tone, steering away from cuts while not igniting concerns over any hikes.
AUD/USD futures – market positioning from the COT report:
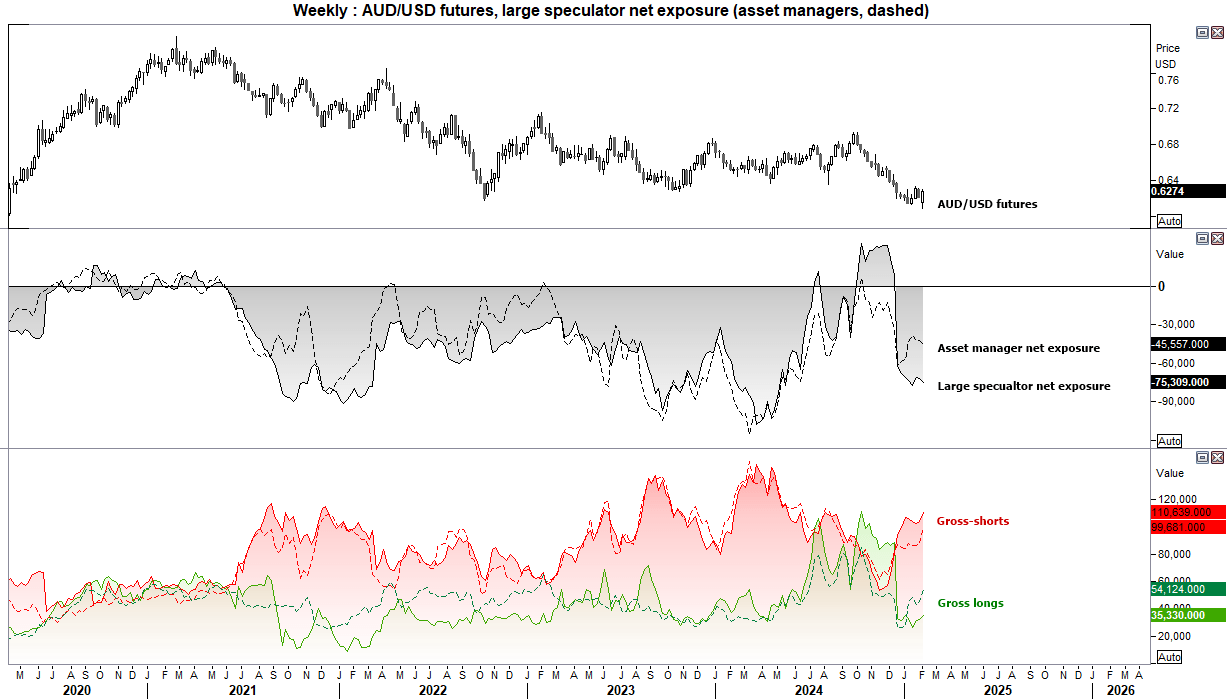
- Net-short exposure to AUD/USD futures increased by 3.5k contracts among large speculators and 3.2k contracts among asset managers
- This means net-long exposure has risen eight of the past nine weeks among large speculators
- However, there seems to be a certain degree of heading going on given longs and shorts increased among both sets of traders
- And despite the rise of net-bearish exposure, AUD/USD went on to form a prominent bullish reversal after reaching its lowest level since the pandemic last Monday morning, which raises the prospects of a significant swing low
AUD/USD technical analysis
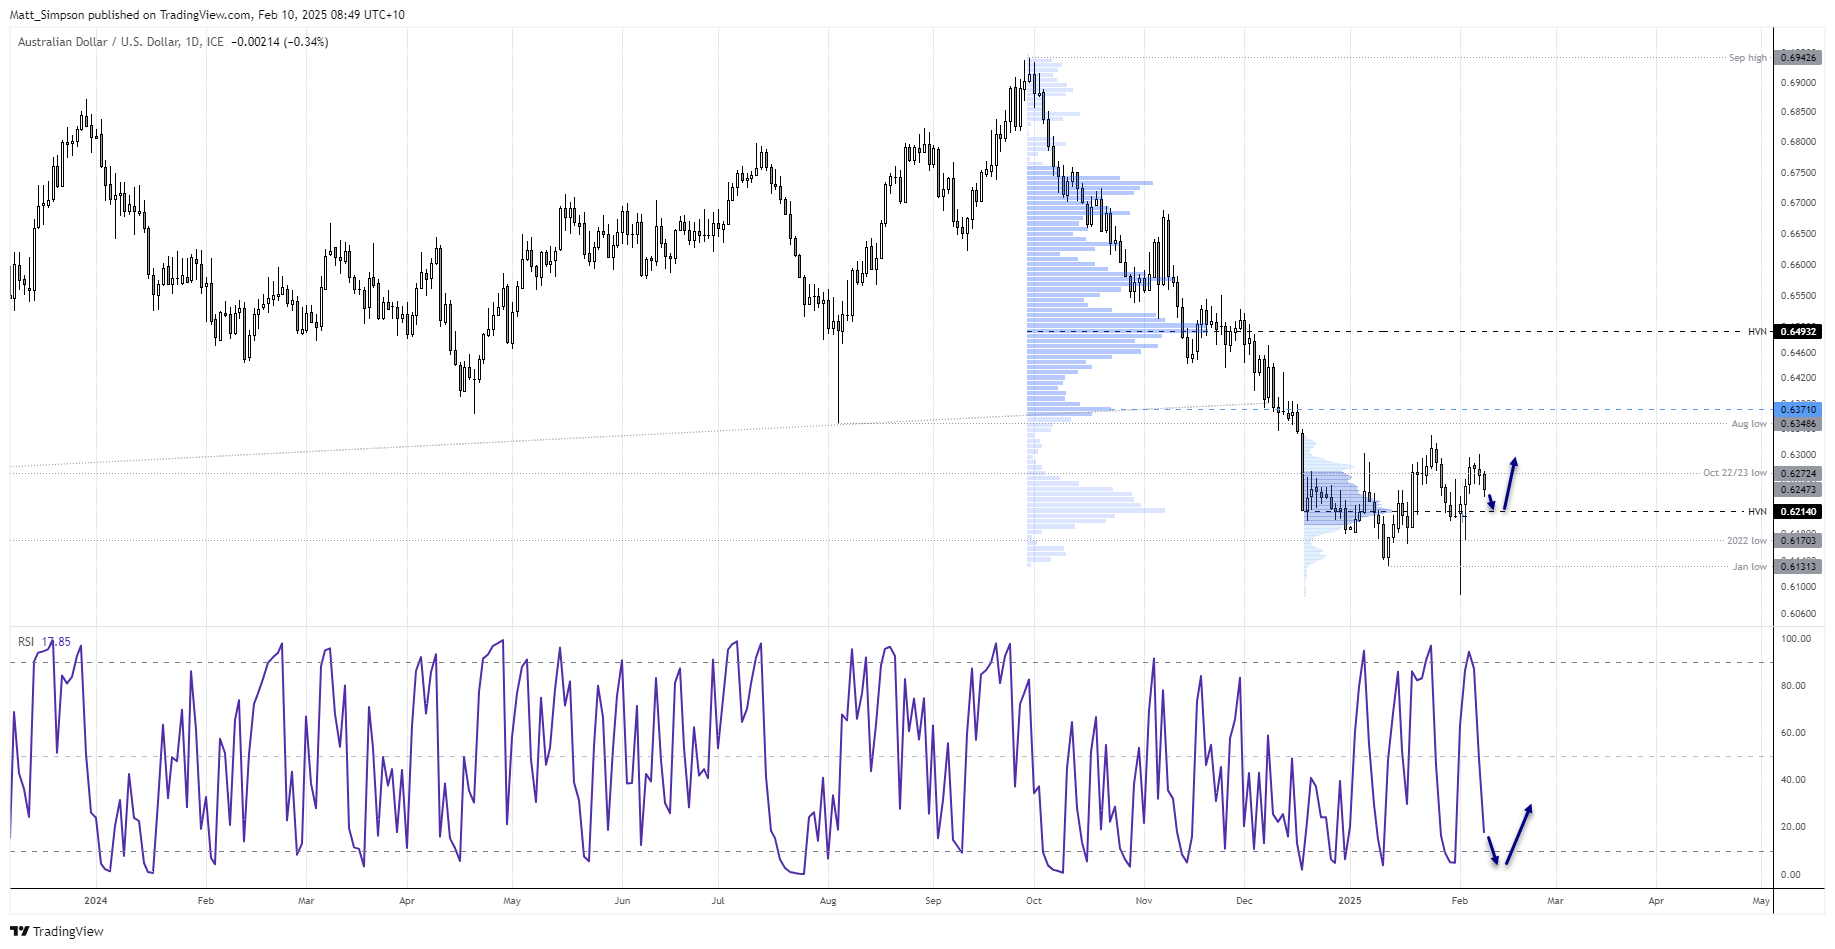
The Australian dollar had fallen -12.3% from the September 30 high to Monday’s low, before closing the day with a prominent bullish pinbar. This deems the breakout to the 5-year low as a fakeout, or bear trap. Tariff headlines (good and bad) are clearly the bigger driver for AUD/USD over rate-cut bets, but then it has already been argued that AUD/USD downside could be limited given it was mostly sold throughout Q4.
We could be in for some rangebound trading, given its reluctance to test 60c and lack of a true bullish catalyst. I still think a retest of the August low at 0.6348 is possible. But unless we are treated to a dovish Fed, less-dovish-than-expected RBA or positive trade headlines, it upside potential seems likely to remain capped.
Bulls could seek dips towards the 0.6214 high-volume node (HVN) in anticipation of a move up to 63c. A break below 62c invalidates this near-term bullish bias.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.
US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.


AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.