

Australian Dollar Outlook: AUD/USD Mulls Pullback Despite RBA Hike Bets
AUD strength looks stretched as multiple crosses stall near resistance, leaving AUD/USD vulnerable to a pullback even as markets price an RBA hike.
Share this:

View related analysis:
View related analysis:
Australian Dollar Performance
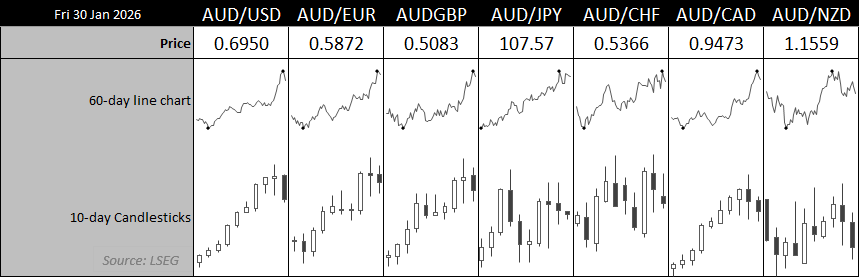
It has been a very strong start to the year for the Australian dollar overall. However, with several AUD crosses at or near resistance — or already retracing — it suggests any hawkish surprise from this week’s RBA meeting may already be priced in.
Source: LSEG
- AUD/USD snapped a nine-day winning streak on Friday, its strongest daily run in nine years
- AUD/CAD printed a weekly shooting star at the 2023 high, warning of potential trend exhaustion
- AUD/JPY formed an inside week and spinning-top doji, signalling hesitancy to break above the 2024 high near the 110 handle
- AUD/NZD retraced for a third consecutive week, though price action still looks corrective rather than a trend reversal
- EUR/AUD suffered its worst monthly decline in 3.5 years as the Aussie rose against the euro for a sixth straight week
- GBP/AUD fell to a 13-month low and closed decisively below 2.00
Australia This Week: Economic Data and Events for AUD/USD Traders
|
Date |
AEDT (GMT +11) |
Event |
|
Mon 2 Feb |
09:00 |
AU PMIs |
|
|
11:30 |
AU ANZ Job Advertisements (Jan) |
|
|
12:45 |
CN Caixin Manufacturing PMI (Jan) |
|
Tue 3 Feb |
01:45 |
US S&P Global Manufacturing PMI (Jan) |
|
|
02:00 |
US ISM Manufacturing Prices (Jan) |
|
|
04:30 |
FOMC Member Bostic Speaks |
|
|
11:30 |
AU Building Consents (MoM) (Dec) |
|
|
14:30 |
RBA Cash Rate Decision (No Change Expected), Monetary Policy Statement |
|
Wed 4 Feb |
00:00 |
FOMC Member Barkin Speaks |
|
|
01:40 |
FOMC Member Bowman Speaks |
|
|
02:00 |
JOLTS Job Openings |
|
|
16:10 |
RBA Assistant Governor Jones Speaks |
|
Thu 5 Feb |
00:15 |
US ADP Nonfarm Employment Change (Jan) |
|
|
02:00 |
US ISM Non-Manufacturing PMI (Jan) |
|
Fri 6 Feb |
00:30 |
Jobless Claims |
|
|
02:50 |
FOMC Member Bostic Speaks |
|
|
09:30 |
RBA Gov Bullock Speaks |
|
Sat 7 Feb |
00:30 |
US Nonfarm Payrolls (Jan) |
|
|
02:00 |
US Michigan Consumer Sentiment, Inflation Expectations (Feb) |
RBA Policy Outlook: Big Four Banks Brace for a Rate Hike
Over the past couple of weeks, Australia’s jobs report has beaten expectations while quarterly inflation landed broadly in line with consensus — the issue being that those estimates were already pitched at a higher inflation outcome. As a result, trimmed mean CPI rose to 3.3% y/y, remaining above the Reserve Bank of Australia’s 2–3% target band. That contrasts with the RBA’s November forecast, which pencilled in a moderation to 2.7% y/y by Q4.
Still, market reaction suggests positioning had leaned toward an even hotter inflation print, with the three-year yield falling 11bp following the release. Even so, economist forecasts and market pricing currently favour a 25bp hike on Tuesday, which would lift the cash rate to 3.85%.
RBA cash rate futures implied a 67% probability of a 25bp hike on Friday, and all Big Four banks have now updated their forecasts to expect tightening. While ANZ view a single 25bp move this week as “insurance” rather than the start of a sustained hiking cycle, NAB also expects a second 25bp hike in May, which would take the cash rate to 4.10%.
I may be left with egg on my face by Tuesday’s close, but my base case is that the RBA holds rates at 3.6% while delivering a clearly hawkish undertone. Even if the RBA does hike this week, it is difficult to see sufficient appetite for another move in May unless inflation re-accelerates in the late-April CPI report.
Take note that the RBA will also release its Monetary Policy Statement, including updated economic and inflation forecasts.


ISM, NFP and FOMC Speakers on Standby
The key risk from this week’s ISM and NFP reports is that they fail to soften enough to revive rate-cut discussions. That leaves markets exposed to upside surprises — and the potential for less-dovish commentary from FOMC members.
That risk is amplified by Friday’s rebound in the US dollar following confirmation that President Trump has nominated Kevin Warsh to replace Jerome Powell as Fed Chair. The dollar sell-off has now lost an important dovish narrative. Markets had assumed Trump would opt for a more rate-cut-friendly replacement, but Warsh has previously argued that the Fed was too loose during Covid.
If US data shows renewed resilience, Warsh could ultimately prove more inclined to keep rates higher for longer than Powell. That leaves the US dollar vulnerable to a broader rebound — a dynamic that could weigh on AUD/USD over the near term.
AUD/USD Futures Positioning | COT Report
Large speculators flipped to net-long exposure for the first time since December 2024. While net longs of 7.1k contracts are not a sentiment extreme, gross long exposure sits just below a nine-year high, warning of near-term crowding risk.
With signs already emerging that the Australian dollar rally is pausing for breath, AUD/USD could be vulnerable to further losses if this week’s RBA hike is viewed as a one-and-done — or if the RBA holds altogether. That said, potential inflection points in precious metals and the US dollar may prove to be the bigger drivers of any near-term retracement, before AUD/USD’s broader bullish trend resumes.
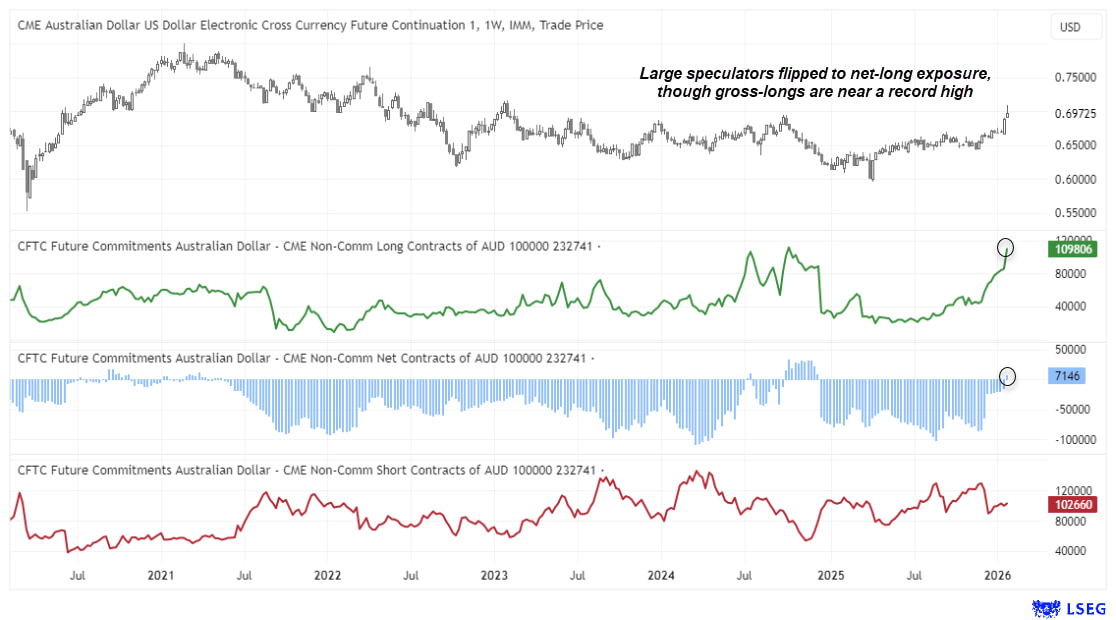
Chart prepared by Matt Simpson - Source: ABS, LSEG
AUD/USD Correlations
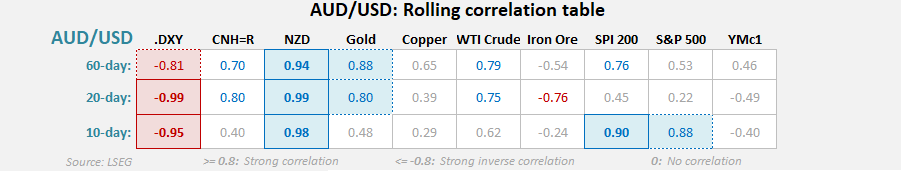
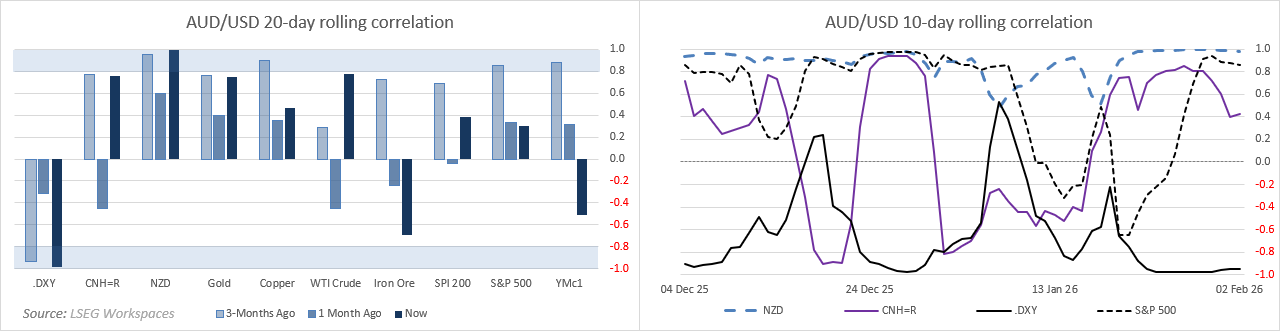
Chart prepared by Matt Simpson - Source: LSEG
AUD/USD Technical Analysis: Australian Dollar vs US Dollar
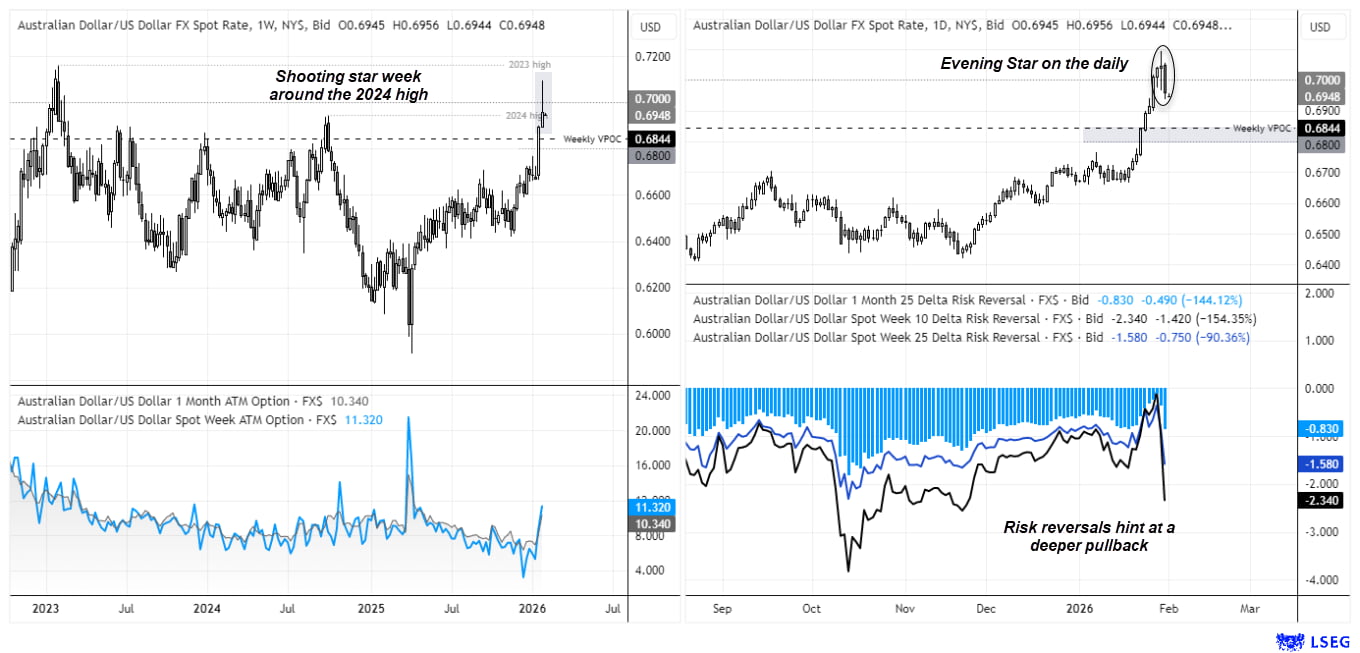
The sharp sell-off in gold and silver, alongside a late-week rebound in the US dollar index, has weighed on the Australian dollar. A shooting star formed on the AUD/USD weekly chart, while an evening star reversal appeared on the daily, with price closing back below 70c. With risk reversals pointing lower — as demand for puts rises relative to calls — a pullback now looks overdue.
The weekly VPOC just above the 68c handle stands out as a potential support zone for a modest near-term retracement. I doubt AUD/USD pushes down to 67c, but even if it did, the broader bullish trend would remain intact.
Ultimately, bulls are likely to view dips as opportunities, with scope for the Australian dollar to challenge 72c in the weeks ahead.
Source: LSEG
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Outlook: A Rates Trade Disguised as a Stock Market?
Australian bond futures have exhibited a far stronger relationship with the ASX 200 than Wall Street over recent months. Now both markets are displaying remarkably similar price structures.

AUD/USD Bulls Fight Back After Australian Jobs Shock
AUD/USD has been hit by another ugly Australian employment report, sending RBA rate hike expectations sharply lower. Yet the relationships driving the currency have shifted since quarter-end, and improving risk appetite could provide the fuel for a recovery.
USD/JPY Update: Can the Japanese Yen Sustain Its Recovery?
Short-term price action around the Japanese yen has started to show some relative improvement over recent sessions. This can be seen in the recent performance of USD/JPY, which has now recorded three consecutive daily declines in favor of the Japanese currency, resulting in a depreciation of roughly 0.35% over the period.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.