



FOMC Fallout: 5 Signs Chairman Warsh’s Honeymoon at the Fed is Over
The bear steepening in the Treasury markets, decision outsourcing to the bond market, three hawkish dissents, dollar weakness, and simultaneous drop in stocks and bonds are warning signs for new FOMC Chairman Warsh - volatility ahead?
Share this:

FOMC, Fed Key Takeaways
- There are at least five signs that the market is starting to lose confidence in FOMC Chairman Warsh’s inflation fighting bona fides.
- The bear steepening in the Treasury markets, decision outsourcing to the bond market, three hawkish dissents, dollar weakness, and simultaneous drop in stocks and bonds are warning signs.
- Upcoming NFP and CPI reports, as well as Chairman Warsh’s Jackson Hole speech, will likely drive more market volatility than usual given the uncertainty around the Fed’s framework.
Traders were treated to a full slate of US economic data this morning with the first reading of Q2 GDP coming in at 1.5%, well below the 2.1% print expected by economists, Core PCE near expectations at 3.3% y/y, and initial jobless claims below 200K for the second straight week.
Despite these updates on the US economy, the far more important takeaways come from FOMC Chairman Warsh’s press conference yesterday and the market’s reaction to it. Reading between the lines, there are at least five signs that the market is starting to lose confidence in Warsh’s inflation-fighting bona fides:
1. Long-Term Yields Surged While Short-Term Yields Fell
The clearest warning comes from the Treasury market.
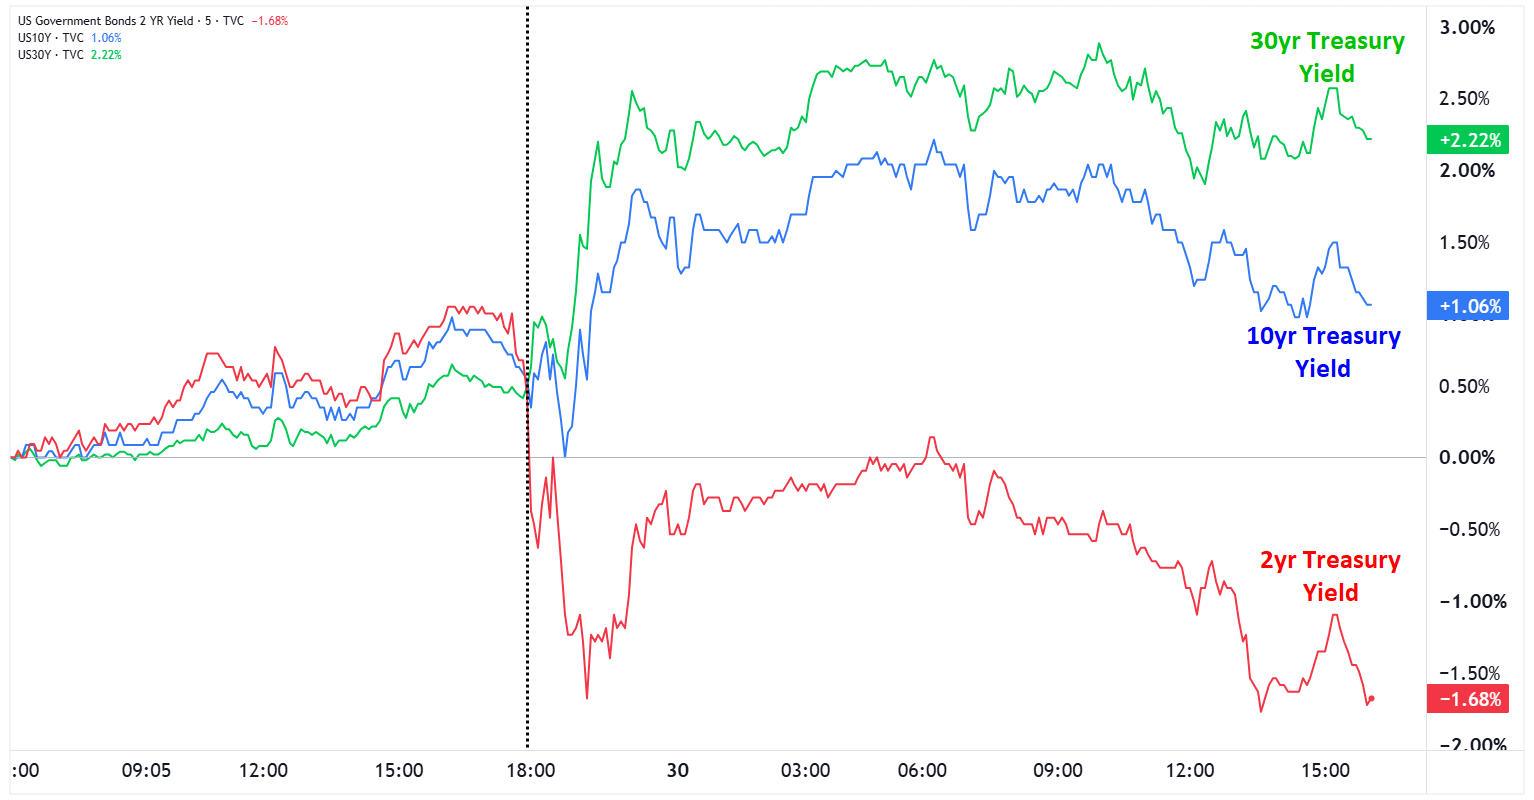
The two-year yield, which is highly sensitive to near-term Fed policy, declined after the meeting, signaling that traders are pushing back expectations for an imminent interest rate increase from the FOMC. Meanwhile, the 10-year yield rose sharply and the 30-year yield posted an even larger increase.
Source: Tradingview, StoneX
To put it plainly, this is not the typical reaction to a dovish Fed surprise. If traders believed the Fed had correctly concluded that less tightening was necessary, yields would likely have declined across the curve, or at least remained relatively stable at the long end.
Instead, the bond market move suggests investors became less confident in an imminent rate hike while demanding more compensation to hold longer-term bonds. In other words, markets may believe the Fed will remain patient now, but that inflation will consequently stay higher for longer.
2. Warsh Appeared to Rely on the Bond Market to Tighten Policy
Showing unusual deference to the bond market, Warsh repeatedly pointed to the rise in market interest rates as a reason the Fed could afford to wait. His argument was that higher Treasury yields had already tightened financial conditions, reducing the immediate need for another rate increase.
There are two problems with this view. First, Warsh’s explanation risks appearing outcome-dependent. At Sintra earlier this month, he suggested falling bond yields showed that markets understood inflation would decline. This week, he argued that rising yields were tightening financial conditions enough to reduce the need for immediate Fed action. Treating both falling and rising yields as validation of the Fed’s stance makes his reaction function difficult for traders to understand.
The other issue is that yields may be rising precisely because investors are worried about inflation and Fed credibility, creating a potentially risky feedback loop. Inflation concerns push long-term yields higher, the Fed cites those higher yields as a reason not to act, and investors become even more concerned that policymakers are falling behind the curve.
3. Three Policymakers Dissented in Favor of a Rate Increase
The decision to hold rates steady passed by a 9–3 vote, with three officials preferring an immediate 25-basis-point increase. Dissents are not necessarily rare, and Warsh has encouraged more open debate within the committee.
According to the St. Louis Fed’s database, at least three members have dissented at only 56 meetings since comparable records begin in March 1936, roughly 6.5% of all meetings. Even more notable, all three July dissenters favored the same alternative: an immediate 25-basis-point hike.
The dissents make the decision to wait look less like a strong consensus and more like a judgment call by the chairman and the majority.
4. The Dollar Fell Despite Higher Treasury Yields
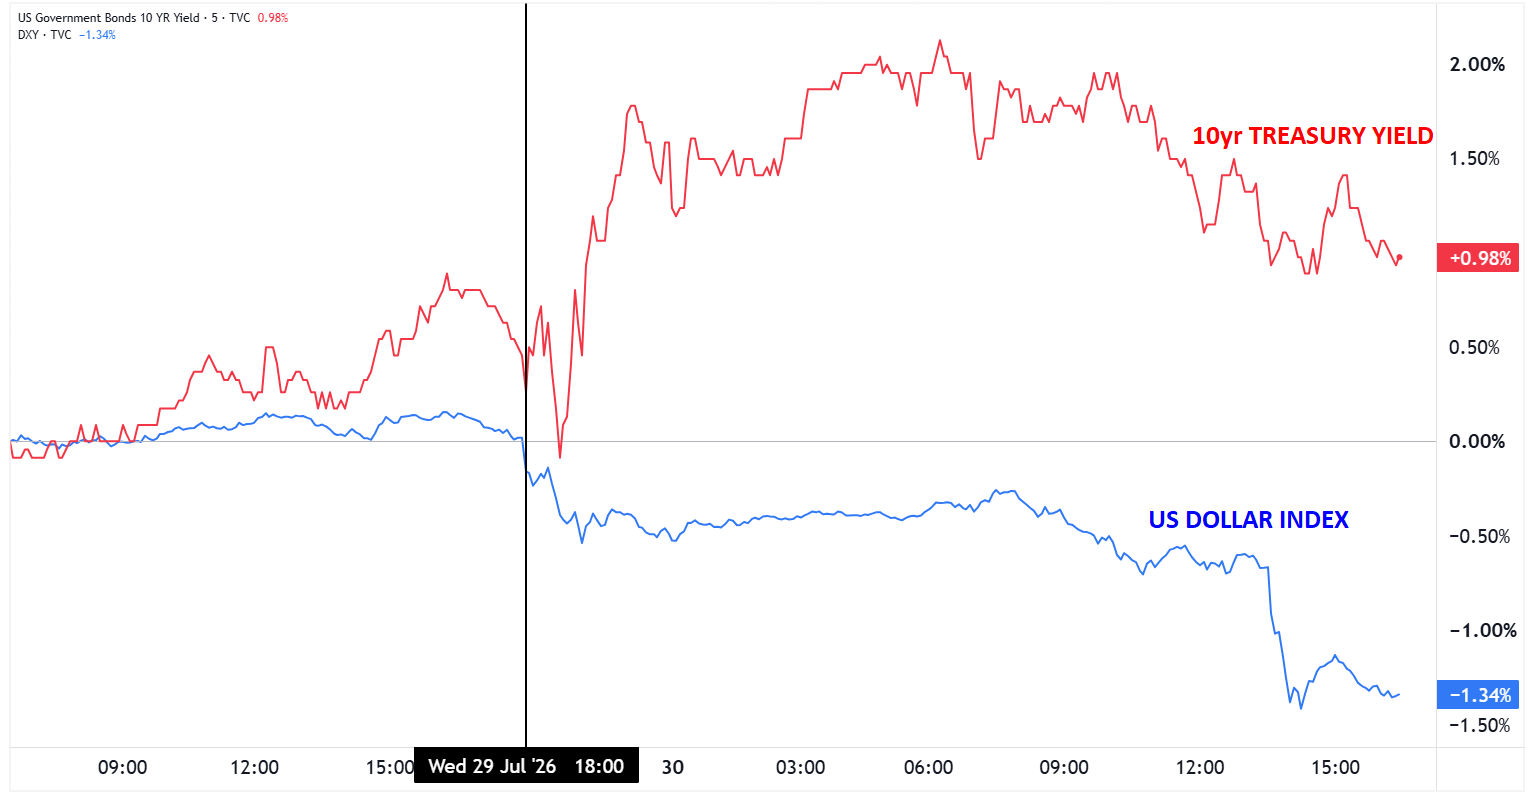
Rising Treasury yields usually provide some support for the US dollar by making dollar-denominated assets more attractive. In the wake of yesterday’s FOMC meeting, the dollar weakened even as longer-term yields climbed:
Source: Tradingview, StoneX
The move suggests currency traders don’t necessarily see the rise in yields as a positive reflection of stronger growth or credible monetary tightening. Instead, the move could be interpreted as compensation for inflation risk, fiscal uncertainty or less predictable Fed policy.
5. Stocks and Long-Term Bonds Sold Off Together
Source: Tradingview, StoneX
The simultaneous decline in equities and long-duration Treasuries is another notable warning. Typically, when investors fear recession, stocks often fall while long-term bonds rally. When yields rise because growth expectations are improving, stocks can sometimes absorb the increase; this yin and yang is the basis of using a classic 60% stocks / 40% bonds investment portfolio to diversify risk.
The post-Fed move fits neither of these patterns.
The combination of falling stocks and bonds is more consistent with an increase in inflation uncertainty, term premium or policy risk. In other words, investors are demanding a higher return for holding both risky assets and long-term government debt.
Why The Fed Has Not Lost Control (Yet), Despite These Warning Signs
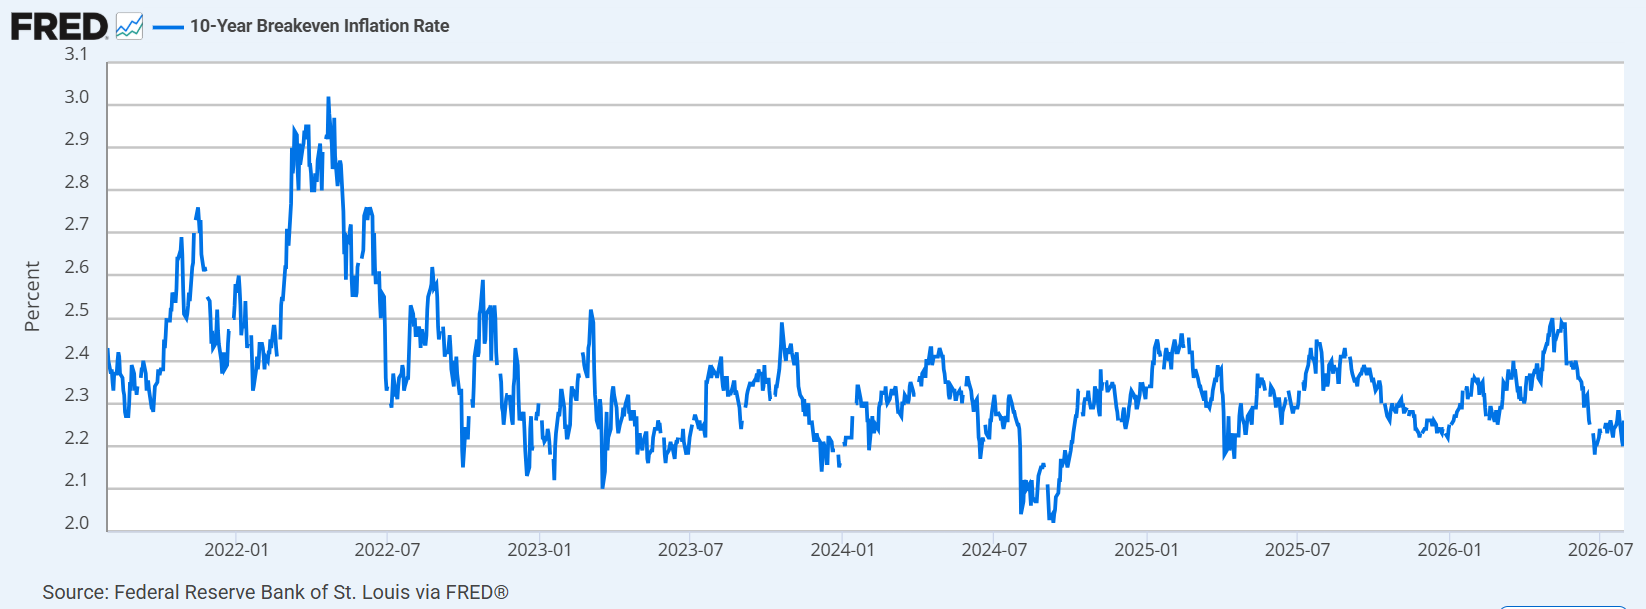
Despite this week’s setback, it’s still too early to conclude that Warsh has lost the market’s confidence. Factors like higher oil prices, further escalation in the US-Iran conflict, fiscal deficits, and heavy Treasury issuance are also contributing to the rise in long-term yields. Indeed, longer-run inflation expectations remain far below levels that would indicate a full-scale credibility crisis:
Source: FRED
Still, the market reaction to the FOMC meeting suggests that traders are beginning to question whether the Fed’s ostensibly hawkish rhetoric will be matched by action.
The next test will be whether inflation continues to run well above target while the Fed remains on hold. If long-term yields and inflation expectations keep rising without a corresponding increase in expected policy rates, concerns that the central bank is falling behind the curve are likely to become much harder to ignore.
The pressure cooker of managing the world’s largest and most important central bank will only rachet up from here. Traders should pay particular attention to the next two employment reports on August 7 and September 4, the CPI releases on August 12 and September 11, and Warsh’s Jackson Hole address on August 27–29. Together, those events will shape expectations ahead of the highly anticipated September 16 FOMC decision and could generate greater-than-usual market volatility.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Midterm Forecast: The Key Risks for Traders to Watch Through the US Elections
Prediction markets are pricing in nearly 75% odds of a Democratic sweep in this week’s US midterm elections, a development that would result in a split from the single party Republican rule of the past two years - what will it mean for markets?
Nasdaq 100 Forecast: NDX rebounds as oil prices fall and ahead of Apple earnings
U.S. stock indices are moving higher on Monday as tech and AI-related stocks steady following a shocking October. The mood remains cautious following the AI wobble, with more tech earnings due this week, U.S. midterm elections and a full U.S. economic data calendar.

Have Markets Found a Turning Point Ahead of the Elections?
Fed rate-hike bets topping 70% have pressured markets, including precious metals and U.S. indices, toward key support levels. Could these levels signal a turning point ahead of the U.S. midterm elections?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.